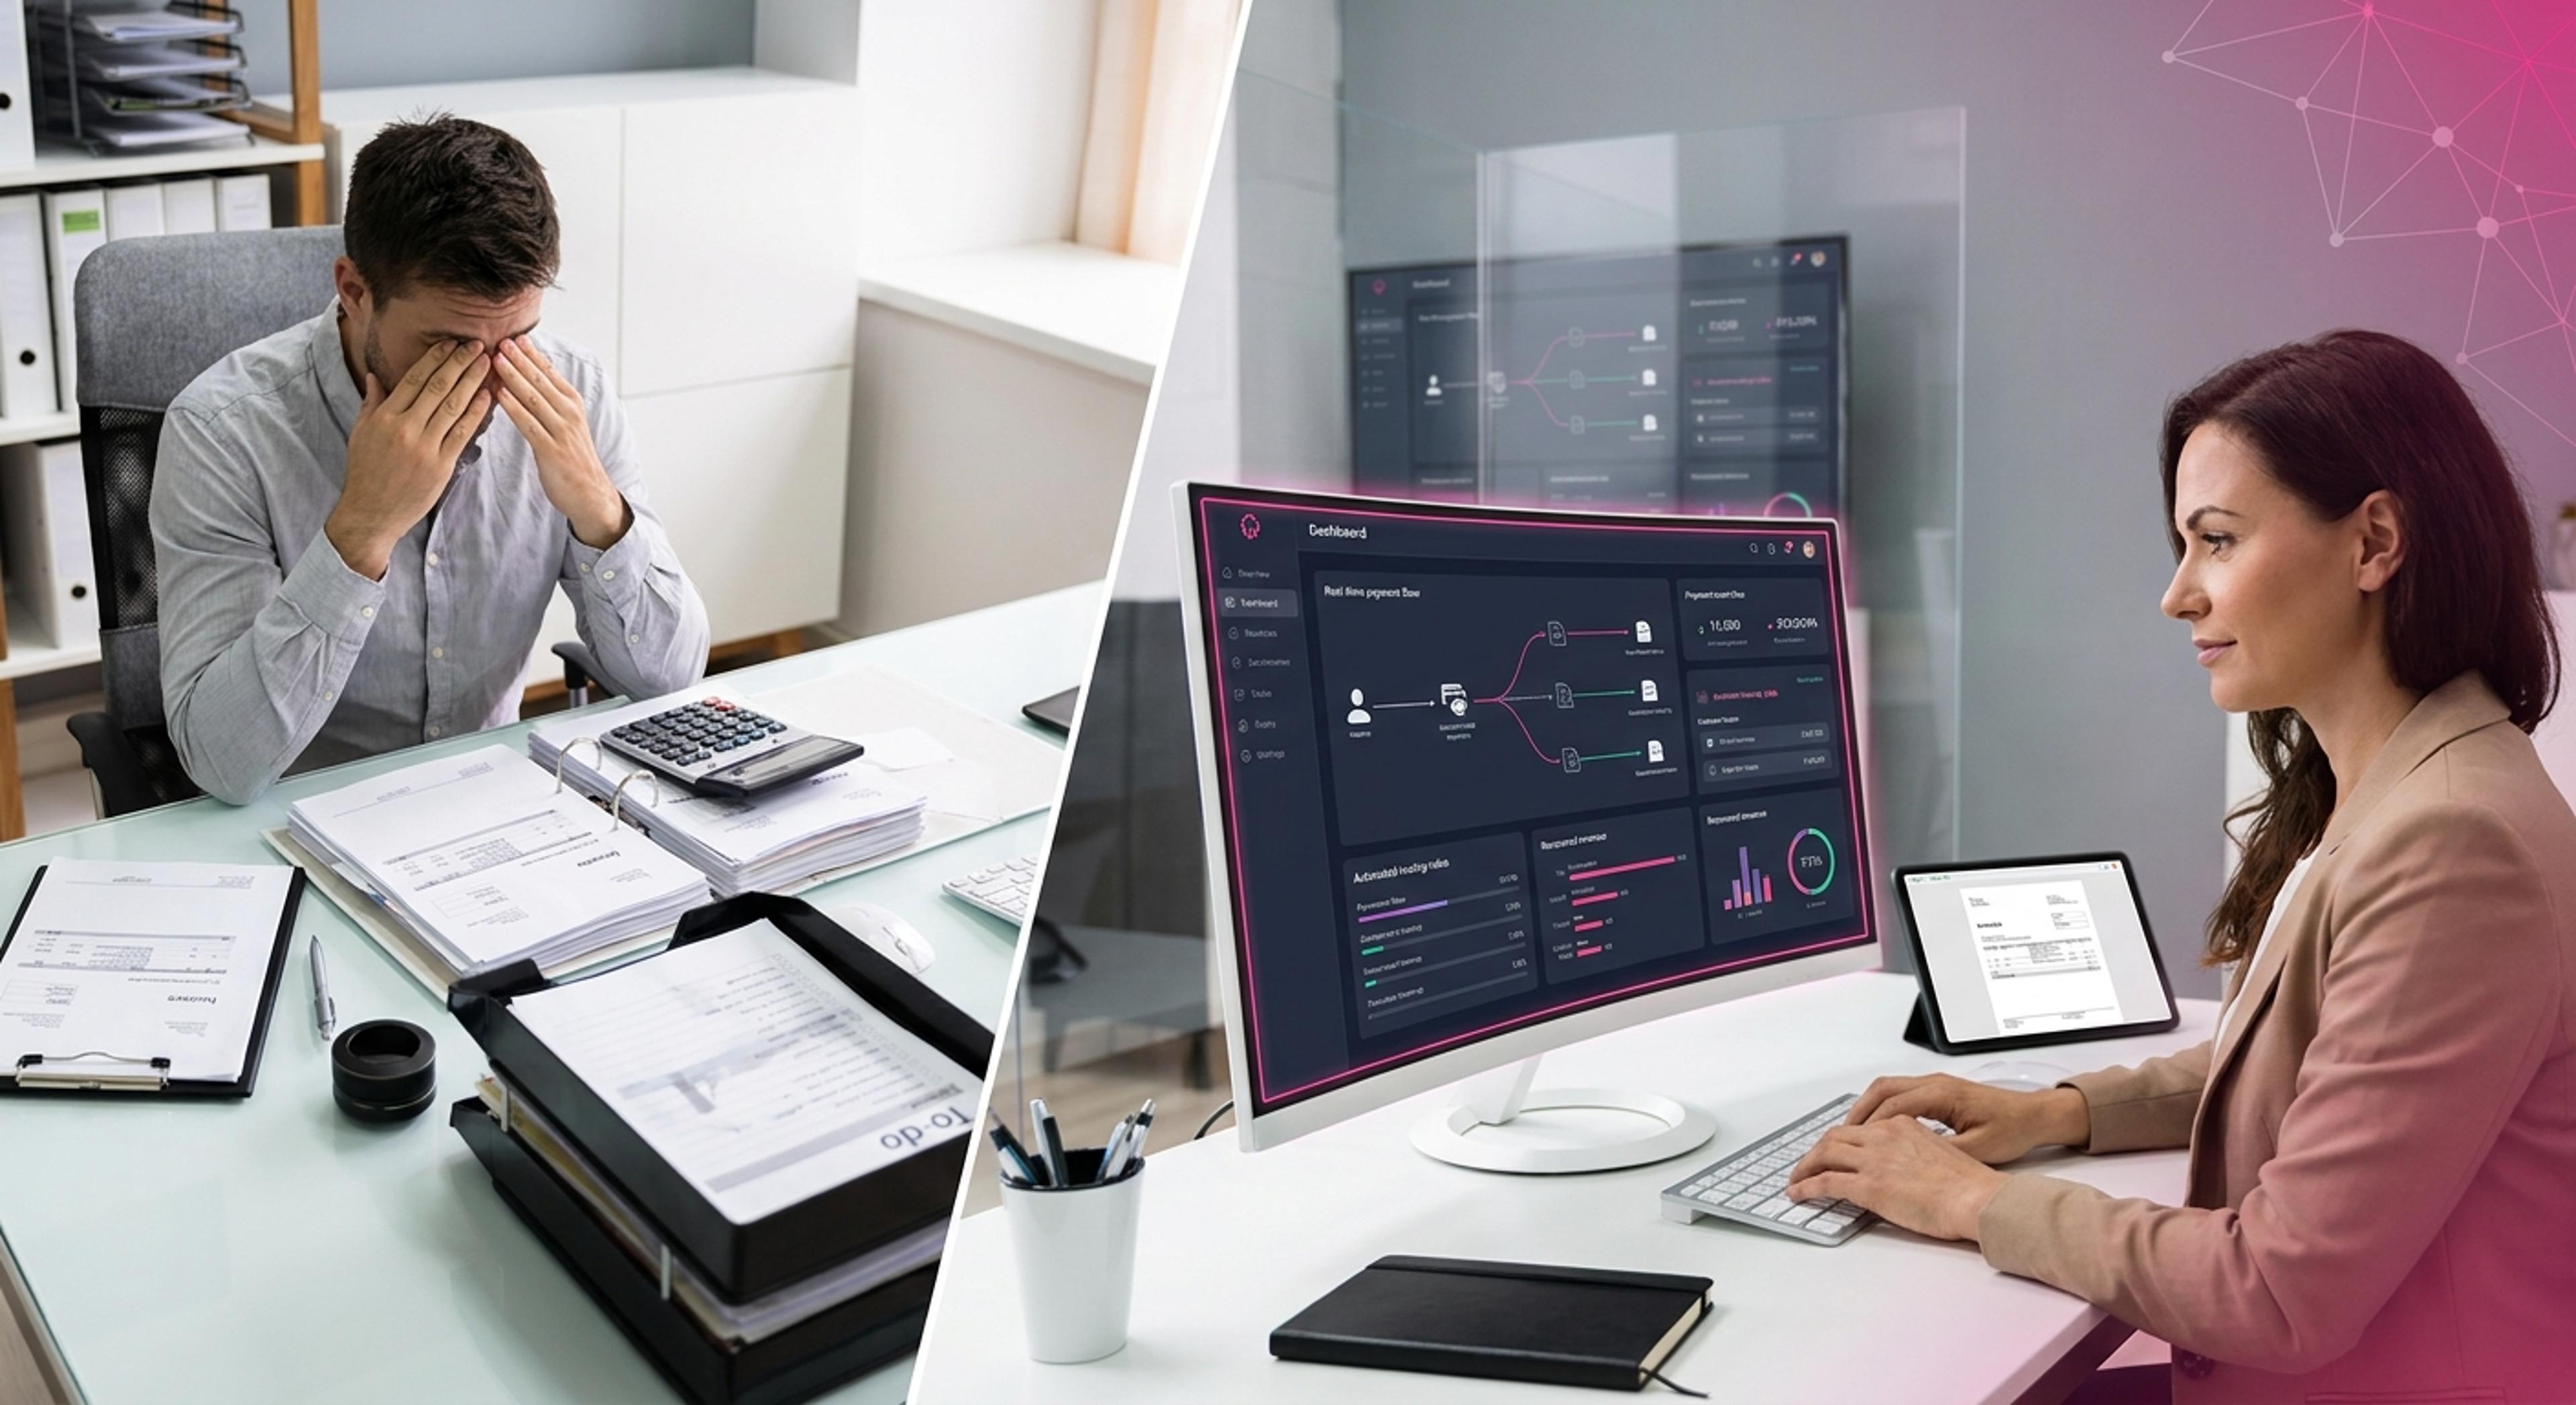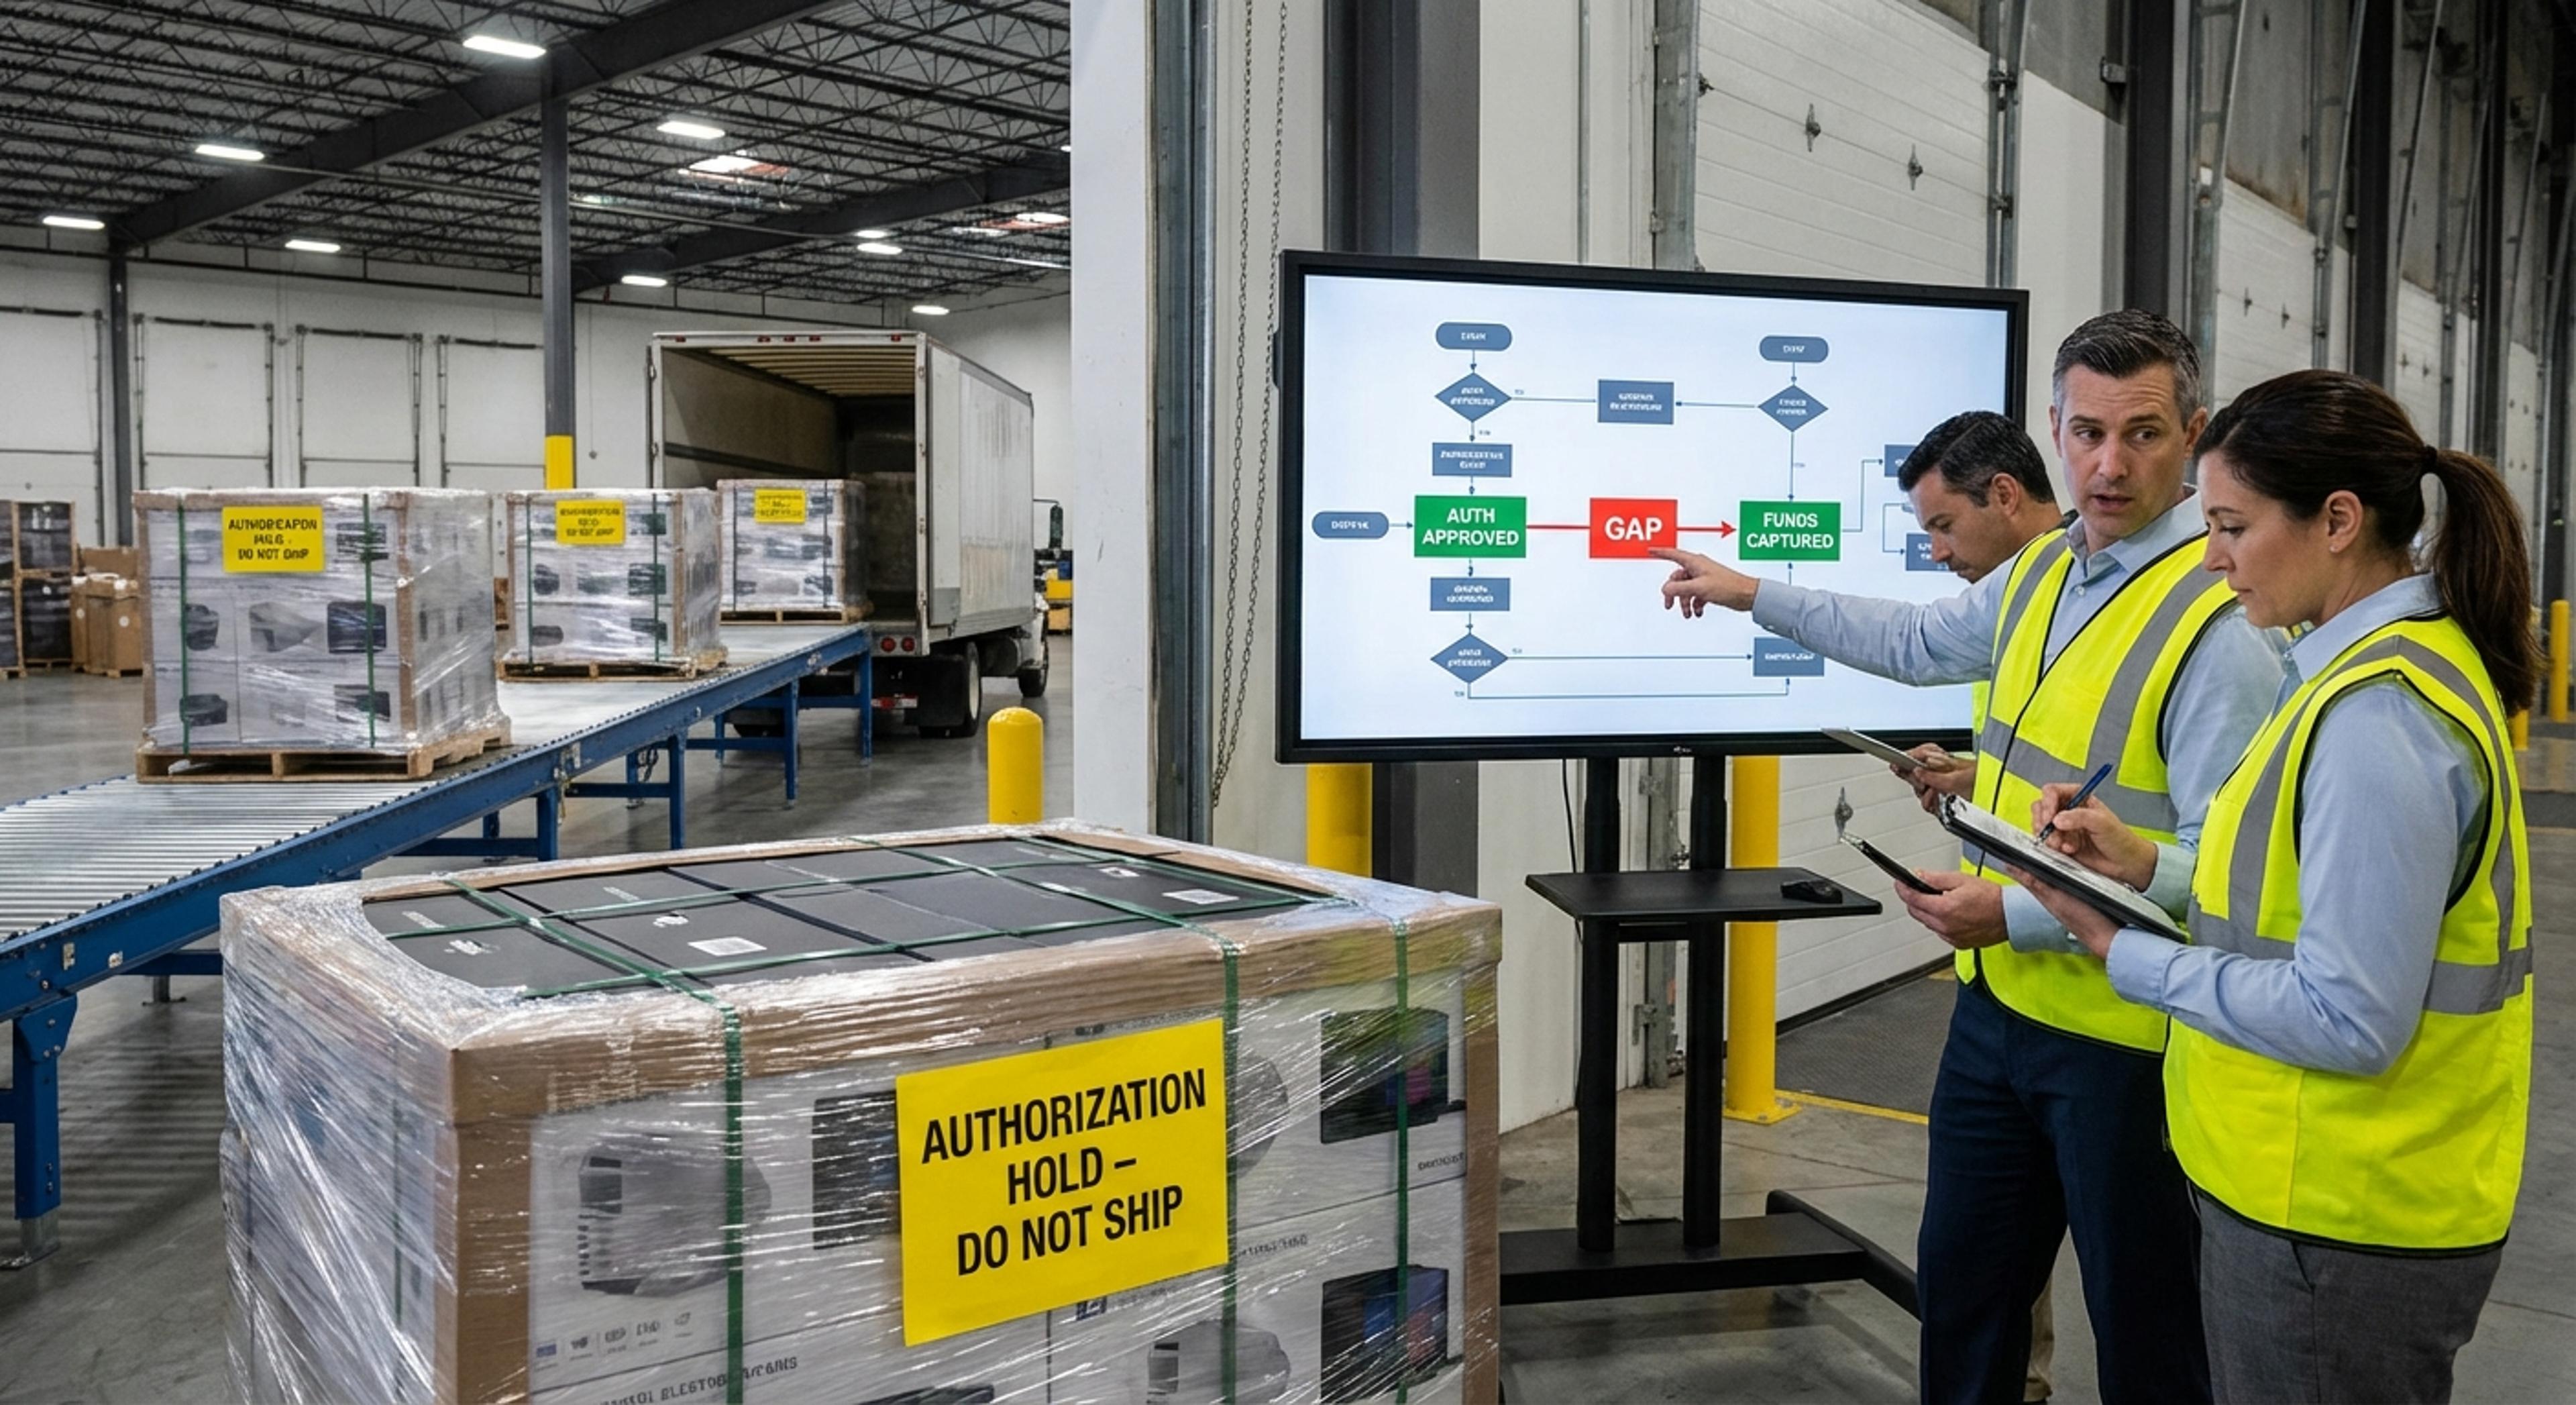

Payment reconciliation is the accounting process of comparing internal transaction records against external bank statements, acquirer settlement files, and payment service provider reports to verify that every authorized, captured, refunded, or retried payment matches the actual net funds deposited into the merchant’s bank account.
How does Payment Reconciliation work?
Payment reconciliation operates by ingesting data from three primary sources: the merchant’s internal order management or billing system, the payment gateway or processor transaction logs, and the acquiring bank’s settlement statements. Because payment capture and bank settlement happen asynchronously, reconciliation engines must match individual transaction identifiers across different timestamps and batch summaries.
In a standard card payment flow, the merchant authorizes and captures a transaction on day one, the acquirer batches and clears the transaction via the card networks on day two, and the net funds settle into the merchant’s bank account on day three or later. During this window, interchange fees, scheme assessments, processor markups, refunds, and chargeback deductions are subtracted from the gross settlement amount. Furthermore, when declined transactions enter an automated retry workflow, multiple authorization attempts may be logged before a single capture succeeds.
To reconcile accurately, the system links the original invoice or order ID to the successful payment attempt ID, validates the gross captured amount against the processor’s clearing file, accounts for exact fee deductions and foreign exchange conversions, and confirms that the sum of net transactions equals the lump-sum payout recorded on the bank statement. Any unmatched records are flagged as exceptions for manual investigation by finance or payment operations teams.
Why does Payment Reconciliation matter for payment teams?
Accurate payment reconciliation is essential for preventing revenue leakage, maintaining audit readiness, and verifying that payment processors and acquirers are charging contractually agreed fees. When merchants scale across multiple payment service providers, local acquirers, and alternative payment methods, settlement delays and inconsistent reporting formats create significant operational friction.
Manual matching across fragmented systems consumes substantial engineering and finance bandwidth. Currently, only 34% of surveyed executives report that their businesses have automated their reconciliation and reporting processes (American Express). Without automated transaction matching, payment teams struggle to distinguish between true settlement shortfalls, unapplied retries, and timing differences across banking cut-off windows.
What are common use cases for Payment Reconciliation?
- SaaS and subscription merchants: Matching recurring billing invoices against multi-day intelligent retry cycles to ensure a single customer renewal is not double-counted or prematurely written off when an initial charge declines and a subsequent retry settles days later.
- Multi-PSP ecommerce retail: Consolidating daily payout batches from multiple regional acquirers and digital wallets into a unified general ledger entry while separating gross sales from interchange-plus fee deductions.
- Utility and municipal billing platforms: Reconciling recurring customer schedules, such as an equalized payment plan or a monthly water bill payment, where partial captures, ACH return codes, and card retries must align with customer ledger balances.
- Mobility and travel merchants: Matching high-volume, low-ticket micro-transactions, such as an automated toll road payment or transit tap, where delayed batch aggregations and offline captures create timing gaps between usage and settlement.
Payment Reconciliation vs Payment Settlement
| Attribute | Payment Reconciliation | Payment Settlement |
|---|---|---|
| Primary Definition | The accounting verification process that matches internal ledgers against external payout records. | The actual movement of funds from the cardholder’s issuing bank to the merchant’s acquiring bank. |
| Owner | Merchant finance, accounting, and payment operations teams. | Card networks, issuing banks, acquiring banks, and payment processors. |
| Timing | Performed post-settlement (daily, weekly, or monthly close). | Occurs after transaction capture, typically within T+1 to T+5 business days. |
| Core Output | Verified general ledger entries and an exception report of unmatched transactions. | Net funds deposited into the merchant’s bank account alongside a settlement report. |
What are best practices for Payment Reconciliation?
- Enforce persistent idempotency and parent-child transaction IDs: Assign a unique, immutable parent order ID that persists across the initial payment attempt and all downstream retries, ensuring that five declined attempts and one successful capture reconcile back to a single customer invoice.
- Ingest raw processor settlement files via API or SFTP: Rely on T+1 clearing and settlement webhooks or raw batch files (such as EPX, EPA, or ISO 20022 formats) rather than synchronous authorization responses, as authorized transactions can still fail to clear or be adjusted prior to payout.
- Reconcile at the gross and net levels separately: Unbundle net bank deposits by parsing out scheme fees, interchange, acquirer markups, and reserve withholdings at the transaction level so fee discrepancies do not break automated matching rules.
- Account for rolling cut-off windows and currency conversion: Normalize all internal order timestamps and processor settlement files to UTC, and lock the exact foreign exchange rate applied by the acquirer at the moment of clearing.
How does SmartRetry help with Payment Reconciliation?
SmartRetry simplifies payment reconciliation for recurring and retry-heavy payment flows by maintaining clean parent-child transaction lineage across every recovery attempt. When a declined transaction enters a retry sequence across one or multiple payment processors, SmartRetry preserves the original merchant reference ID and maps every subsequent authorization attempt back to the root invoice. Payment operations and finance teams get unified visibility into which recovered transactions have cleared and settled, eliminating duplicate ledger entries and orphaned retry records. Explore SmartRetry’s recovery analytics and reporting engine to see how intelligent retries integrate cleanly into your reconciliation workflows.