

It happens every second of every day. A customer navigates your platform. They find what they want. They hit the buy button, and then the transaction stops cold. A payment failure is rarely just a localized glitch. It represents a complex cascade of friction that directly impacts the bottom line, and resolving these checkout issues requires far more than simply prompting the user to try another card. In fact, 45% of consumers refuse to continue with a purchase after a false decline (Source).
For revenue leaders and payment operations teams, the gap between a customer clicking “pay” and funds settling in the bank is heavily scrutinized. Yet despite sophisticated checkout flows and optimized front-end experiences, a notable percentage of legitimate transactions still end with a transaction declined message. Datos Insights estimated that global lost sales due to false declines reached US$174.4 billion in 2024 (Source).
The immediate instinct is often to blame the customer’s funds or the payment gateway. In reality, the payment processing flow is a delicate sequence of handoffs between the merchant, the acquirer, the card network, and the issuing bank. Any slight misalignment in formatting, risk scoring, or timing can trigger a rejection. Understanding why these rejections occur, and more importantly, how to systematically recover them, is the foundation of modern payment optimization.
The Invisible Conversation Behind Every Transaction
When a cardholder initiates a purchase, a data payload is generated and sent through a payment gateway to the acquiring bank. The acquirer formats this request and routes it through the relevant card network (like Visa or Mastercard) to the customer’s issuing bank.

The issuer then has a fraction of a second to evaluate the payment authorization request. The bank’s automated systems look at available funds, the card’s status, historical spending patterns, the merchant’s category code (MCC), and various fraud indicators. Based on this rapid assessment, the issuer sends back a response code.
If the response is an approval, the transaction proceeds. If the issuer detects a problem, it returns a response code indicating a decline. These codes are the primary diagnostic tools payment teams use to understand what went wrong, but they are notoriously cryptic and occasionally misleading.
Decoding the Issuer’s Decision
Payment declines generally fall into two broad categories: hard declines and soft declines. Distinguishing between the two is the first step in deciding whether a transaction can be saved.
Hard declines represent a permanent barrier to the transaction. These occur when a card is reported lost or stolen, the account is closed, or the card is entirely invalid. In these scenarios, the relationship between the card network and that specific primary account number (PAN) is effectively severed. Attempting to retry a hard decline is not only futile but can actively harm a merchant’s standing with card networks, potentially incurring fees or lowering the merchant’s overall trust score.
Soft declines, on the other hand, are temporary roadblocks. In fact, they make up between 80% to 90% of all declines (Source). They occur for reasons that might change over time, such as insufficient funds, temporary holds, technical timeouts, or overly aggressive fraud filters at the issuing bank. Because the underlying account is still valid, a soft decline presents an opportunity: if the merchant can present the transaction again under more favorable conditions, the issuer might approve it.
The Problem with “Do Not Honor”
Historically, this code was intended to signal that the merchant should physically confiscate the card. Today, it’s largely used by issuers as a catch-all bucket for rejections that don’t neatly fit into other categories.
An issuer might return a “Do Not Honor” code because of a suspected fraud rule, a temporary velocity limit on the cardholder’s account, or even internal system maintenance at the bank. Because the code lacks specificity, payment operations teams are forced to rely on historical data, BIN (Bank Identification Number) intelligence, and behavioral patterns to determine the actual reason for the failure and whether a retry is viable.
Why Blind Retries Backfire
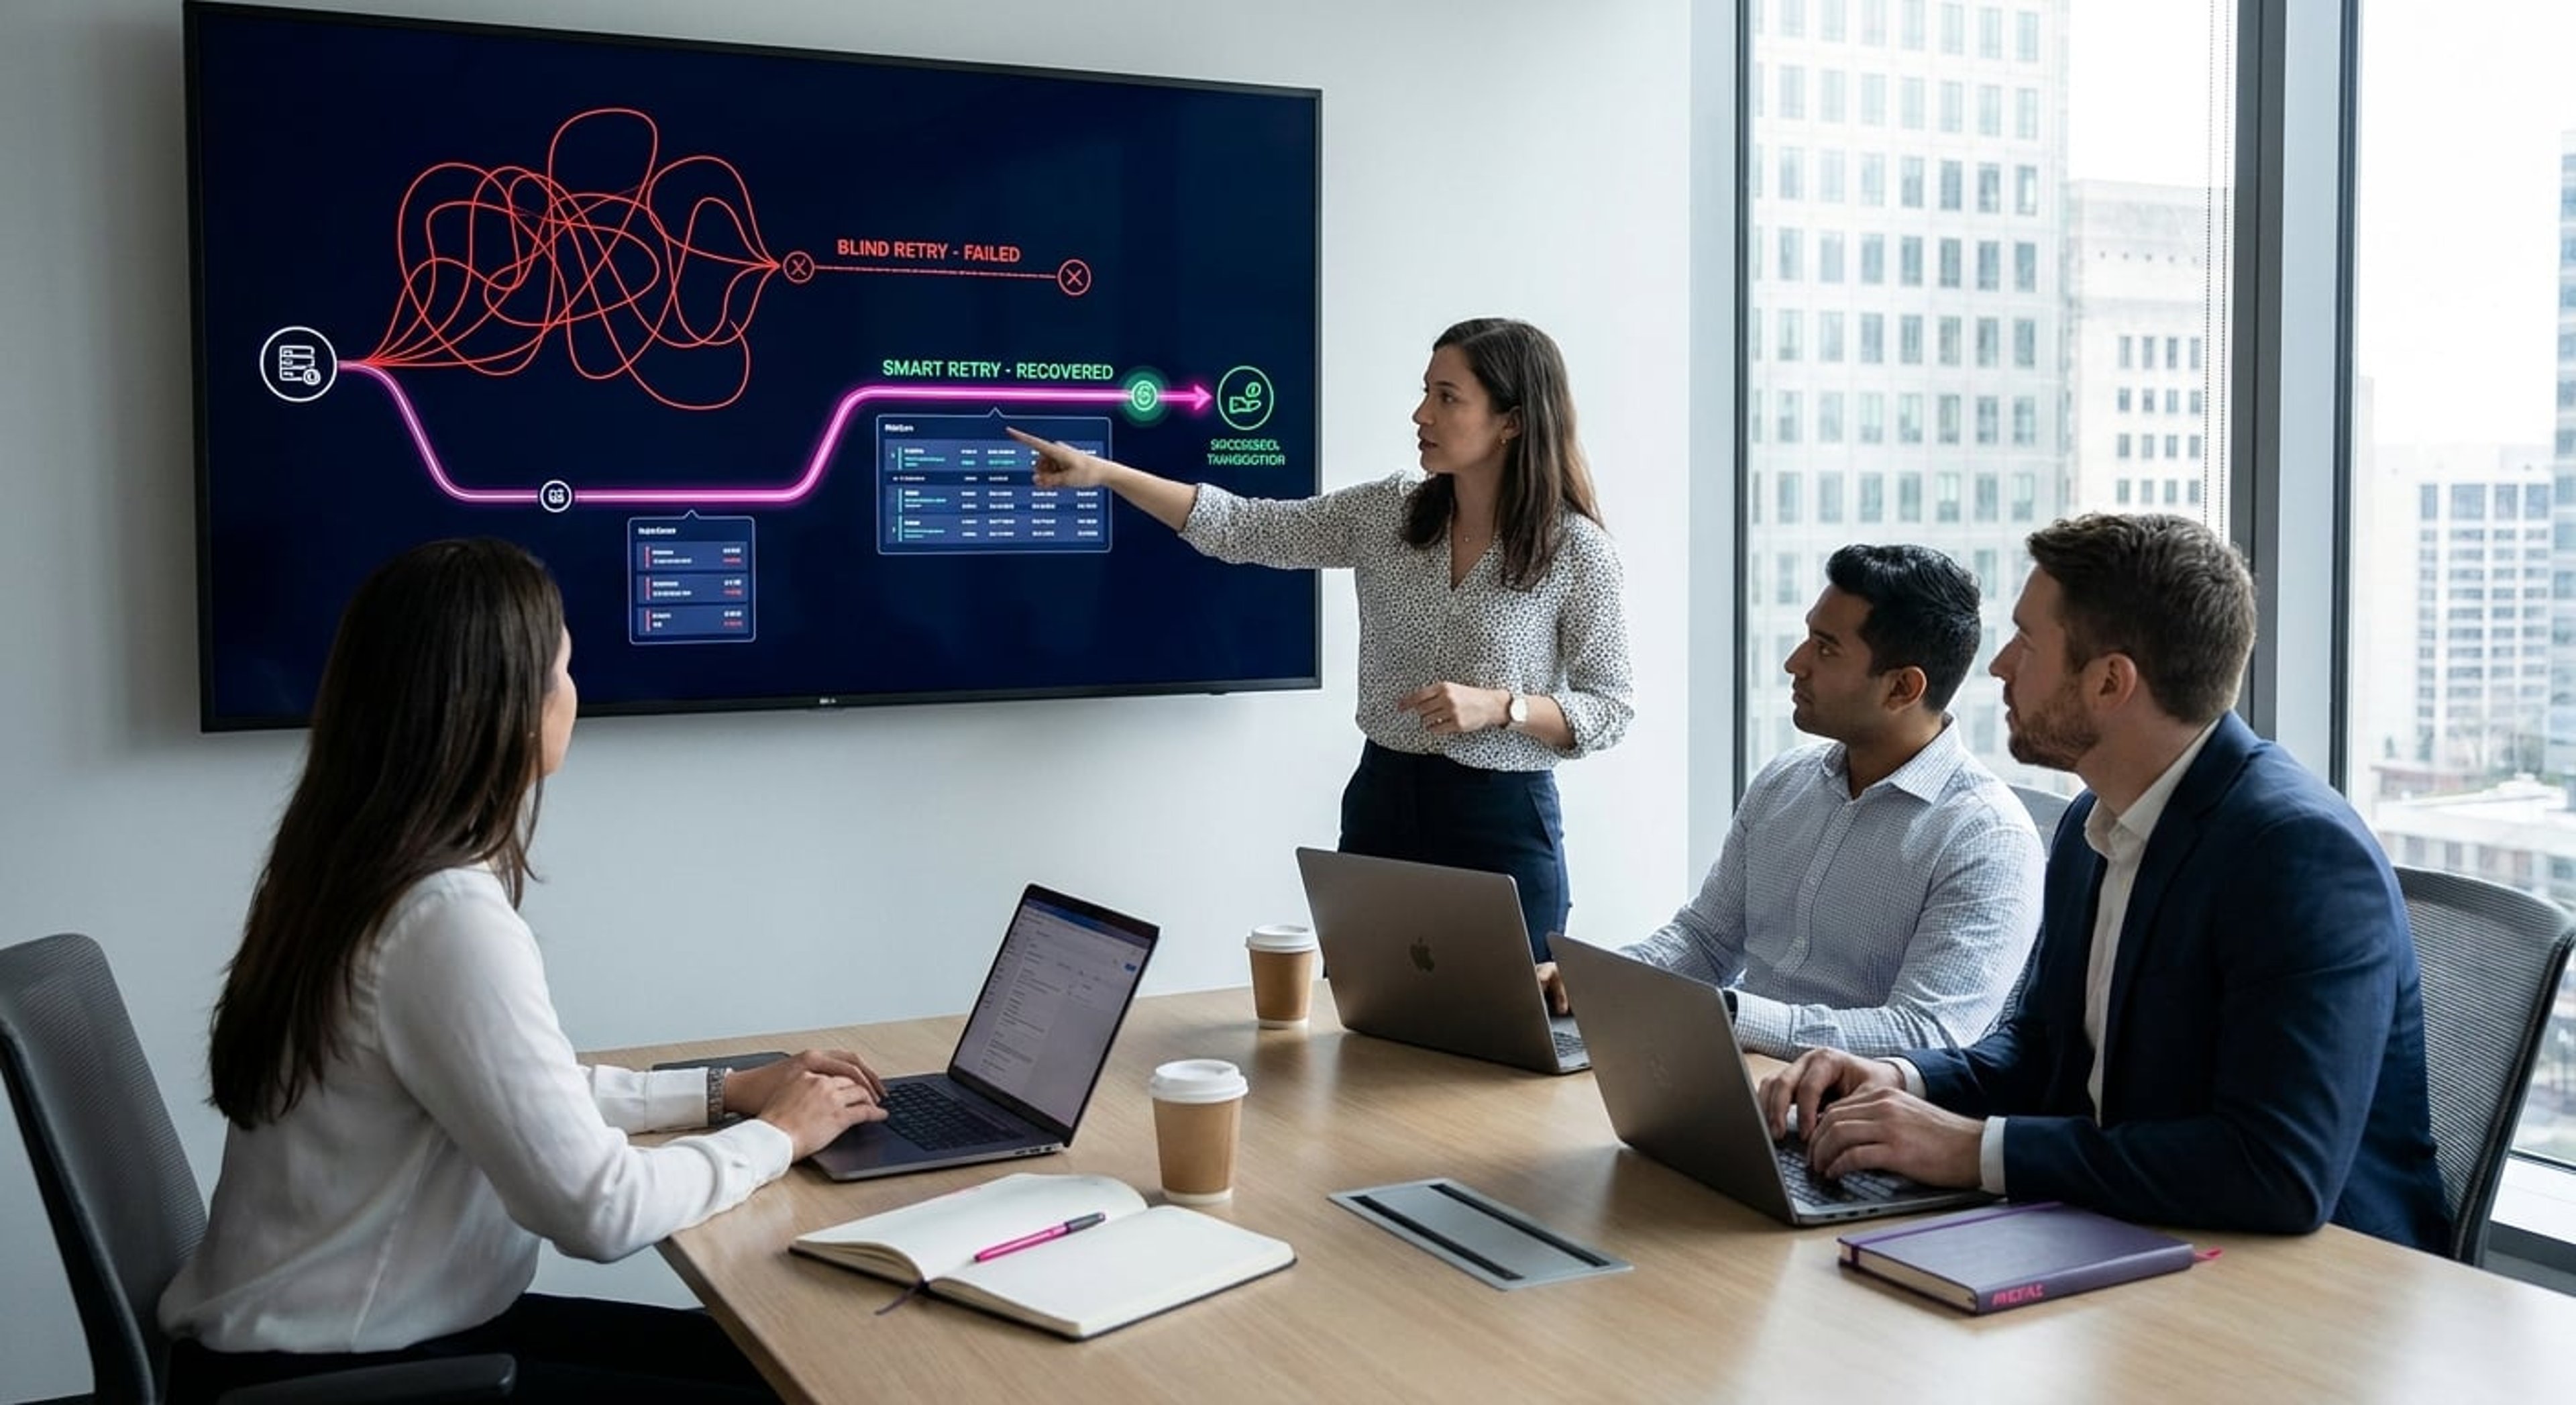
When faced with a soft decline, the simplest technical response is to loop the transaction and try again immediately. Many legacy billing systems default to this approach, hammering the gateway with the same authorization request every few hours or days.
This brute-force approach to retrying payments creates several compounding problems. First, every authorization attempt costs money. Network fees and gateway transaction costs accrue regardless of whether the transaction is approved or declined, so running blind retries on thousands of failed payments can quietly inflate operational costs.
Second, issuing banks monitor merchant behavior. If an issuer sees a merchant repeatedly submitting the exact same transaction payload for a card that was just declined for insufficient funds, its risk models take notice. The merchant appears unsophisticated or, worse, potentially fraudulent. Over time, this behavior can degrade the merchant’s reputation with that specific issuer, leading to a higher baseline decline rate across all transactions.
To reduce payment declines sustainably, merchants have to move away from rigid, rule-based loops and adopt strategies that respect the issuer’s constraints and the cardholder’s reality.
The Mechanics of Intelligent Payment Recovery
To retry failed payments effectively, teams must introduce variance and timing into their requests. An intelligent recovery strategy acknowledges that a soft decline is often a matter of timing rather than a permanent lack of intent or funds.
Timing and Behavioral Economics
The timing of a retry is arguably the most critical variable. If a card is declined for insufficient funds on a Tuesday afternoon, retrying it on Wednesday morning is unlikely to yield a different result. Retrying the transaction on a Friday morning, particularly the first or fifteenth of the month when payroll deposits typically clear, presents a much higher probability of success.
Time-of-day matters too. Issuers in different regions process batch updates and clear temporary holds at different local times. Structuring retry attempts to align with the local business hours of the issuing bank, rather than the merchant’s server time, can yield incremental improvements in the transaction approval rate.
Leveraging Network Tools
Beyond timing, the actual data payload can be optimized. Card networks offer tools specifically designed to keep payment credentials fresh and secure, which inherently reduces failure rates.
Account Updater services automatically poll the card networks for new expiration dates or replacement card numbers when a user’s physical card is reissued. Running a declined card through an Account Updater before attempting a retry can salvage transactions that failed due to stale credentials.
Network tokens offer another layer of optimization. By replacing the raw PAN with a merchant-specific cryptographic token, merchants signal a higher degree of security to the issuer. Issuers generally apply less friction to network tokenized transactions, making them a valuable asset when re-presenting a previously declined charge.

The Unique Challenge of Recurring Billing
While one-off e-commerce purchases suffer from declines, subscription businesses face an entirely different magnitude of risk. In a recurring revenue model, a payment failure isn’t just a lost sale, it’s the trigger for involuntary churn.
Subscription payment issues require a bifurcated approach to recovery: silent retries and active dunning.
Silent retries happen entirely in the background. The billing engine evaluates the decline code, waits for the optimal window, and attempts to authorize the card again without notifying the customer. The goal is to recover the revenue without introducing friction or reminding the customer they’re paying for a service they might not be actively using.
If silent retries exhaust their optimal windows without success, the strategy shifts to active dunning. This involves communicating with the customer, via email, SMS, or in-app notifications, requesting they update their payment method. The transition from silent retries to active dunning must be carefully calibrated. Reaching out too early causes unnecessary friction; reaching out too late means the merchant provides services unpaid for an extended period.
Automating the Decision Tree
Building the infrastructure to handle this logic internally requires substantial engineering resources. Payment teams have to ingest and normalize decline codes across multiple acquirers, build predictive models for retry timing based on historical BIN performance, and maintain integrations with network tools like Account Updater. Because the payment landscape is constantly shifting, these internal tools require continuous maintenance.
This complexity is why many scaling businesses look to specialized infrastructure to handle recovery. According to the Merchant Risk Council, more than 90% of merchants employ at least one tool or technique designed to boost payment authorization rates, such as automated retries or intelligent payment routing (Source). Utilizing a platform like SmartRetry allows merchants to implement intelligent retries of declined payment transactions without dedicating internal sprint cycles to building the logic from scratch. By analyzing vast datasets of issuer behavior and standardizing the recovery process, these platforms help merchants naturally recover revenue and improve their overall approval metrics while freeing up internal teams to focus on core product development.
Moving Beyond the Baseline
Treating declined payments as an unavoidable cost of doing business leaves a significant amount of revenue on the table. The gap between an initial decline and a final, unrecoverable failure is an active optimization surface.
Improving payment performance requires a shift in perspective. It means viewing the issuer not as a black box that randomly dispenses approvals and rejections, but as a counterpart in a highly structured conversation. When an issuer says no, it’s providing a data point.

By analyzing those data points, respecting the rules of the card networks, and applying thoughtful, data-informed retry strategies, merchants can systematically reclaim lost revenue. The goal isn’t to force every transaction through, but to ensure that every legitimate, fundable transaction is given the optimal environment to succeed. In a landscape where acquisition costs continue to rise, mastering the mechanics of payment recovery is one of the most effective levers available for sustained operational health.


 Find me on Linkedin