
Embedded finance is the integration of financial services such as payments, lending, banking, and card issuing directly into a non-financial software platform or merchant checkout flow via APIs, allowing users to execute transactions and access capital natively without redirecting to a traditional bank or third-party payment portal.
How does Embedded Finance work?
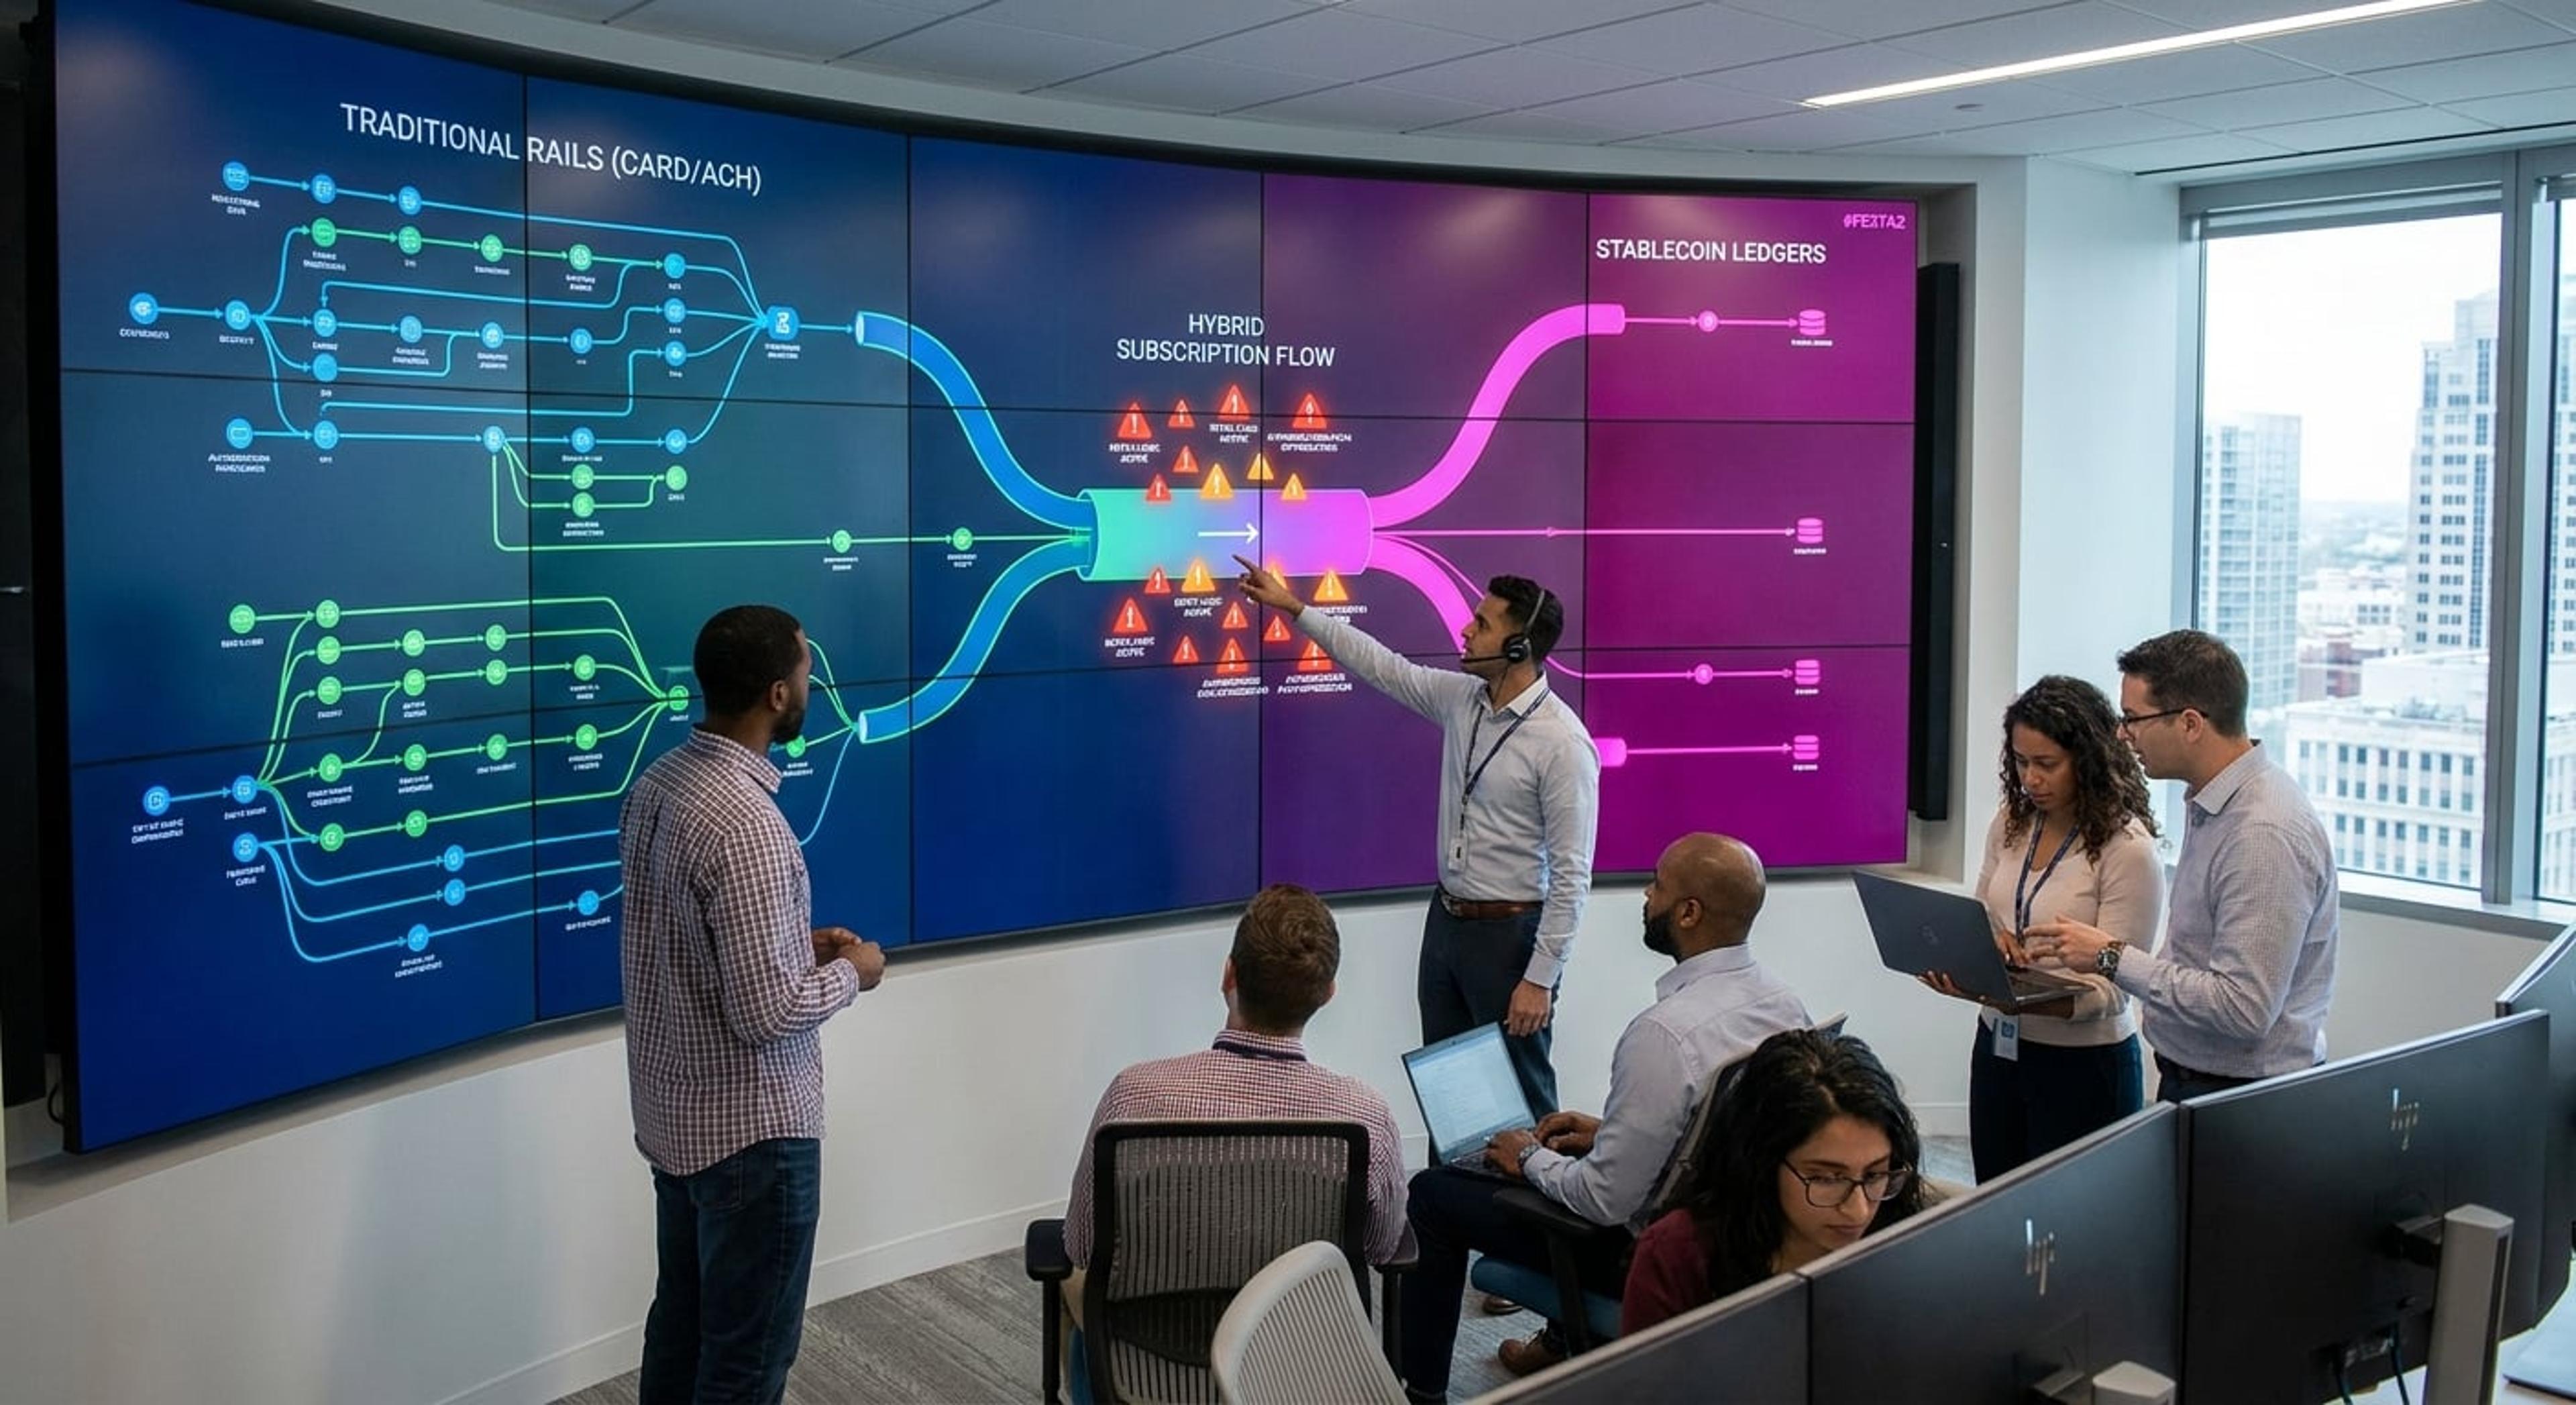
Embedded finance operates through a three-layer architecture connecting licensed financial institutions, infrastructure providers, and non-financial platforms. At the base, regulated banks and card networks provide the balance sheet, compliance framework, and settlement rails required to move funds and issue credit legally. In the middle, Banking-as-a-Service (BaaS) platforms and payment facilitators (PayFacs) abstract these banking functions into modular APIs.
At the top layer, the non-financial platform-such as a vertical SaaS provider or marketplace-integrates these APIs into its native user interface. When a user initiates an action like accepting a customer card payment, drawing down a working capital loan, or funding a virtual wallet, the platform sends an API call to the infrastructure layer. The infrastructure provider orchestrates KYC/KYB verification, fraud screening, and authorization routing with the underlying sponsor bank or acquirer.
Because the platform controls the front-end experience and holds rich operational data-such as a merchant’s daily sales volume, inventory turnover, and refund rates-it can pass contextual signals to the financial provider. This proprietary data improves underwriting accuracy for embedded lending and optimizes transaction routing for embedded payments. Settlements, fee splits, and ledger updates happen automatically in the background, keeping the user inside the host software environment.
Why does Embedded Finance matter for payment teams?
For payment and revenue operations teams, embedding financial services shifts payment processing from a cost center into a primary revenue stream and retention lever. By owning the payment and financial stack, platforms capture interchange revenue, transaction markups, and lending origination fees while eliminating the checkout drop-off caused by third-party redirects. Global transaction value from embedded payments is forecast to increase by 134% between 2024 and 2028, rising from $1.1 trillion to surpass $2.5 trillion (Juniper Research, 2024).
However, operating an embedded finance model introduces complex operational obligations. Platforms that embed payments for sub-merchants or offer native BNPL and wallet funding become directly responsible for authorization performance, involuntary churn, and payment failure recovery across their entire user base. If an embedded subscription billing engine or automated loan repayment sweep suffers high false declines due to rigid retry rules, both the sub-merchant and the host platform lose revenue immediately.
What are common use cases for Embedded Finance?
- Vertical SaaS and Subscription Platforms: Field service, gym management, and healthcare software platforms embed payment processing and automated recurring billing directly into their workflows, monetizing transaction volume while handling card-on-file updates and decline recovery for their business users.
- B2B and B2C Marketplaces: Ride-sharing and freelance marketplaces provide embedded bank accounts and instant payout cards to gig workers and sellers, allowing them to receive earnings immediately after a job completes and spend funds without waiting for standard ACH clearing.
- Ecommerce Retail Merchants: Online retailers integrate white-labeled Buy Now, Pay Later (BNPL) financing and point-of-sale credit directly inside the native checkout container, underwriting buyers in real time without redirecting them to an external lender’s website.
- Travel and OTA Platforms: Online travel agencies embed virtual card issuing to pay hotels and airlines instantly upon booking, while offering consumers embedded travel insurance and currency wallets inside the booking flow.
Embedded Finance vs Banking-as-a-Service (BaaS)
| Dimension | Embedded Finance | Banking-as-a-Service (BaaS) |
|---|---|---|
| Core Definition | The front-end delivery of financial products inside a non-financial customer experience. | The back-end API infrastructure and regulatory licensing that powers embedded financial products. |
| Primary Owner | Non-financial brands (SaaS platforms, marketplaces, ecommerce retailers). | Licensed banks, sponsor banks, and middleware fintech infrastructure providers. |
| User Interaction | Directly visible to the end consumer or sub-merchant inside the software UI. | Invisible to the end user; accessed strictly by engineers via APIs and webhooks. |
What are best practices for Embedded Finance?
- Decouple payment orchestration from a single BaaS or PayFac provider: Avoid single-acquirer lock-in by building an abstraction layer that allows you to route transactions across multiple processors and local acquirers as your platform scales internationally.
- Standardize decline taxonomy across embedded flows: Normalize raw issuer decline codes from underlying processors so your platform can distinguish between hard declines (such as stolen cards) and recoverable soft declines (such as insufficient funds or issuer timeouts).
- Automate network tokenization and Account Updater: Ensure all stored credentials used for embedded recurring billing, wallet top-ups, or loan repayments are provisioned with network tokens to prevent avoidable expirations, while utilizing an Account Updater service to keep cards current.
- Align retry schedules with funding cycles: For embedded lending repayments and SaaS billing, time retry attempts around known payroll dates or sub-merchant payout schedules rather than using static intervals.
How does SmartRetry help with Embedded Finance?
Platforms offering embedded payments, recurring billing, or automated repayment collections lose platform fees and sub-merchant retention whenever transactions fail due to soft declines. SmartRetry integrates via API into your payment flow to analyze issuer decline responses in real time, predicting the exact optimal moment and message format to retry failed transactions without triggering scheme retry penalties. Explore SmartRetry’s intelligent payment recovery engine to increase approval rates and recover lost revenue across your embedded payment flows.