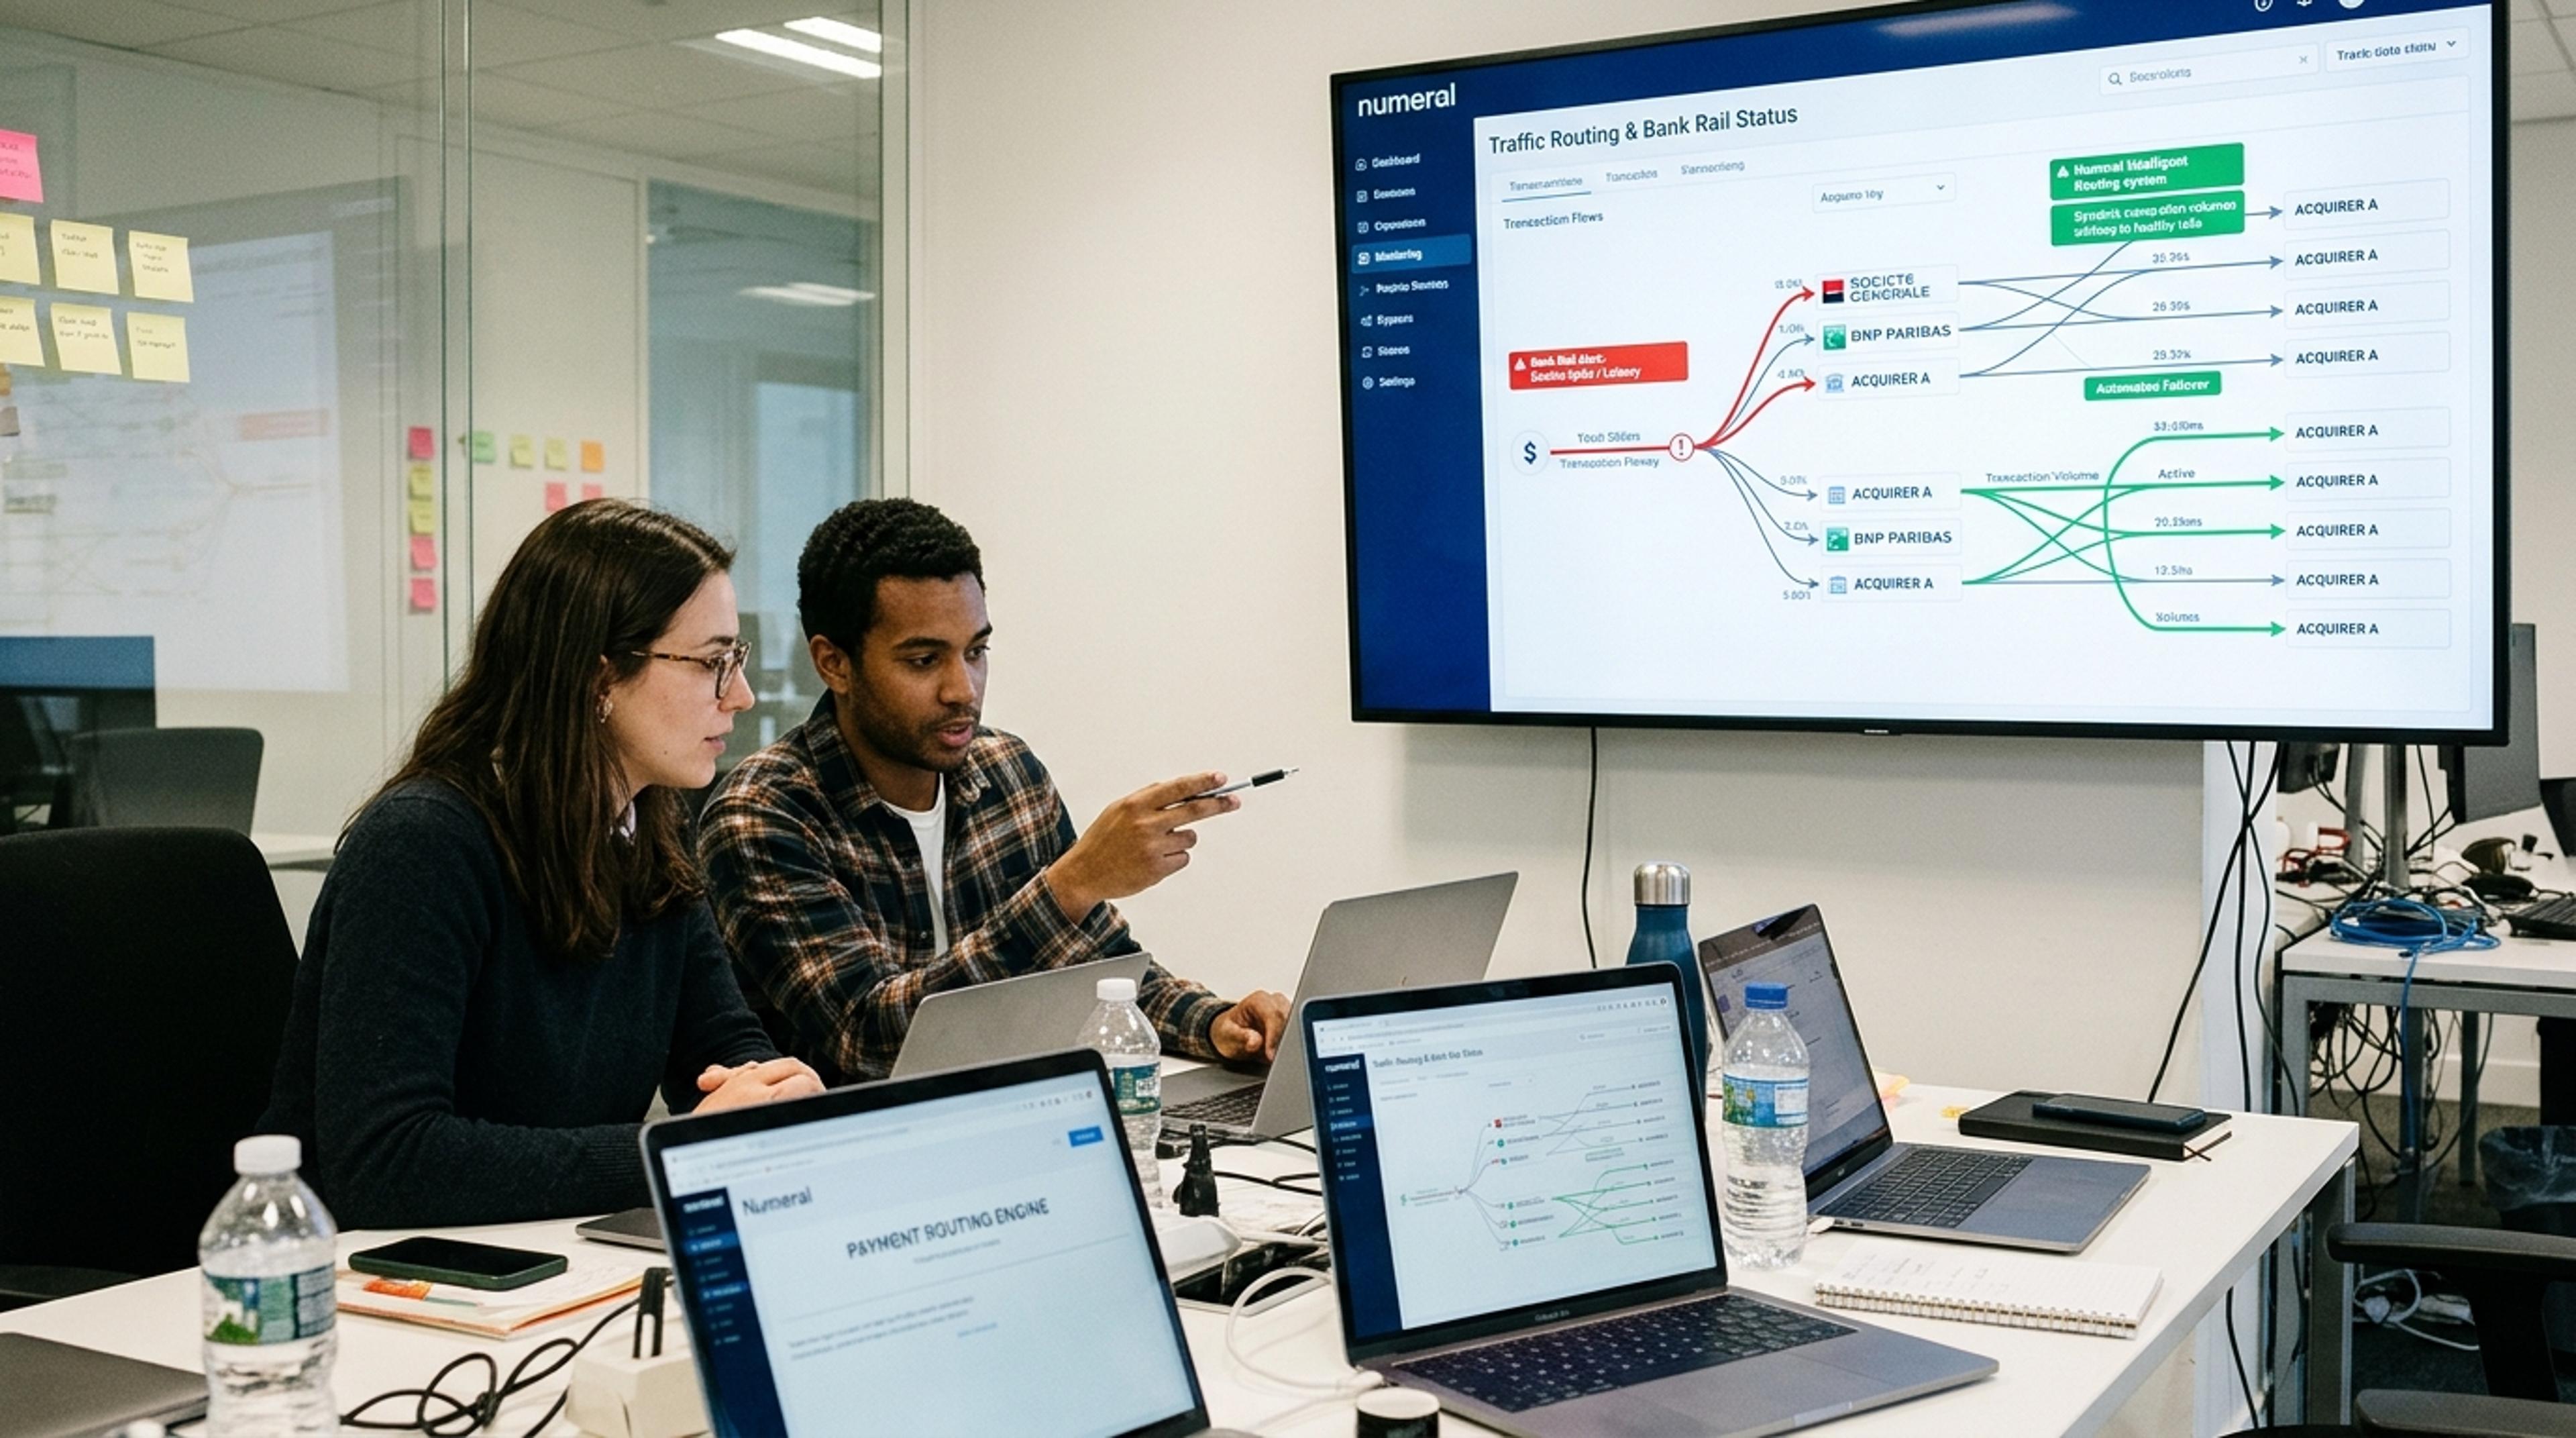

Static payment routing is a rule-based transaction directing method where payments are sent to specific payment service providers or acquiring banks based on fixed, predetermined parameters such as currency, card brand, or geography. Unlike dynamic routing, it does not adjust automatically to real-time authorization rates, processor latency, or system outages.
How does Static Payment Routing work?
Static payment routing operates on deterministic if-then logic configured within a payment gateway, orchestration layer, or merchant vault. When a customer initiates a checkout or a recurring billing cycle triggers, the routing engine inspects the transaction payload for basic metadata. Typical attributes evaluated include the Bank Identification Number (BIN), issuing country, transaction currency, payment method, and transaction amount.
The routing engine matches these attributes against a prioritized hierarchy of hardcoded rules. For example, a rule might state that all Euro-denominated Visa transactions must route to Acquirer A, while all US Dollar American Express transactions must route to Acquirer B. If a transaction matches Rule 1, it is immediately sent to the designated processor without evaluating downstream rules.
Because the logic is static, the system assumes the target acquirer is healthy and performing optimally at the moment of the request. It does not ingest real-time telemetry such as recent issuer decline spikes, API response timeouts, or shifting interchange qualification rates. If the primary processor experiences a brownout or begins rejecting valid cards due to an internal risk rule update, a purely static router continues sending traffic down that path until an engineer or payment operations manager manually alters the configuration or triggers a pre-set sequential failover rule.
Why does Static Payment Routing matter for payment teams?
Static payment routing provides foundational control for multi-processor payment architectures. It allows merchants to enforce contractual volume commitments with acquirers, ensure transactions are processed via local acquiring entities to avoid cross-border scheme fees, and route specific payment methods to the gateways that actually support them.
However, relying strictly on static rules creates operational blind spots during processor degradation or issuer-specific outages. Even with widespread investment in payment orchestration, 68% of companies still rely on manual intervention to switch providers during outages (PYMNTS, 2026). When payment teams must manually rewrite routing tables during an incident, merchants suffer immediate revenue loss, increased cart abandonment, and unrecovered soft declines.
What are common use cases for Static Payment Routing?
- Global Ecommerce Retail: Routing transactions based on customer billing country or currency so that UK shoppers are processed through a UK-domiciled acquirer and European shoppers through an EU entity, securing domestic interchange rates.
- SaaS and Subscription Platforms: Splitting recurring billing volume across two primary payment service providers on a fixed 70/30 percentage split to meet minimum monthly volume commitments required for tiered pricing discounts.
- Online Travel Agencies (OTAs): Directing high-ticket corporate cards and American Express transactions to a specialized processor with favorable commercial card processing rates, while sending standard consumer debit cards to a low-cost domestic rail.
- Digital Goods and Gaming: Enforcing BIN-based routing so that prepaid cards or specific regional debit schemes (like Cartes Bancaires in France or EFTPOS in Australia) are directed exclusively to the local gateway capable of authorizing them.
Static Payment Routing vs Dynamic Payment Routing
| Attribute | Static Payment Routing | Dynamic Payment Routing |
|---|---|---|
| Decision Logic | Fixed if-then rules based on transaction metadata (currency, BIN, country). | Algorithmic or machine-learning models using real-time performance data. |
| Adaptation to Outages | Requires manual rule changes or relies on rigid, pre-configured failover cascades. | Automatically reroutes traffic away from degraded processors in real time. |
| Primary Goal | Contract compliance, regional tax/entity mapping, and baseline cost control. | Maximizing authorization rates and minimizing processing latency and cost. |
| Maintenance Effort | Low setup complexity, but requires manual intervention when performance shifts. | Higher initial integration, but self-optimizing once deployed in production. |
What are best practices for Static Payment Routing?
- Audit BIN tables regularly: Issuers frequently reassign BIN ranges and launch new card products. Outdated BIN tables cause static routers to misidentify domestic cards as cross-border or debit cards as credit, leading to suboptimal routing and higher fees.
- Pair static rules with automated health checks: Never leave a static route without a safety net. Configure automated circuit breakers that temporarily bypass a static rule if an acquirer returns consecutive HTTP 5xx errors or timeouts.
- Keep rule hierarchies flat and mutually exclusive: Complex webs of overlapping static rules create race conditions where transactions hit unintended default routes. Document the exact priority order and test edge-case payloads before deploying changes.
- Separate initial routing from retry logic: While static rules are effective for directing the first charge attempt to the lowest-cost local acquirer, subsequent retries of soft declines should use intelligent, data-driven logic rather than repeating the same static path.
How does SmartRetry help with Static Payment Routing?
Many merchants use static payment routing to manage baseline processor allocations and regional entity compliance, but struggle when those fixed routes return soft declines. SmartRetry complements existing static routing setups by intercepting failed transactions and applying machine learning to the recovery flow. Instead of blindly retrying a declined card on the same static path or immediately cascading to a backup gateway, SmartRetry analyzes the exact issuer decline code, card metadata, and historical approval patterns to determine the optimal processor and precise timestamp for the retry attempt. Explore SmartRetry’s intelligent retry engine to see how your team can recover more declined transactions without overhauling your primary routing rules.