
An ACH payment is an electronic bank-to-bank funds transfer routed through the Automated Clearing House network in the United States. Governed by Nacha, it processes credit pushes and debit pulls in scheduled batches, offering merchants a low-cost alternative to credit cards for recurring billing, payroll, and high-value B2B invoicing.
How does an ACH Payment work?
To understand what is payment by ACH, payment teams must distinguish between its two transaction flows: Direct Deposit (ACH credit, where funds are pushed to a recipient) and Direct Payment (ACH debit, where funds are pulled from a payer). Unlike real-time card networks, the ACH network operates as a batch processing system managed by two central clearinghouses: the Federal Reserve and The Clearing House (EPN).
A transaction begins when an Originator (such as a merchant or employer) collects authorization to debit or credit a Receiver’s bank account. The Originator submits the transaction instructions to its bank, the Originating Depository Financial Institution (ODFI). The ODFI aggregates these instructions with other requests into a standard Nacha file format and transmits the batch to an ACH Operator at designated clearing windows.
The ACH Operator sorts the batched entries and routes them to the customer’s bank, known as the Receiving Depository Financial Institution (RDFI). The RDFI receives the file and debits or credits the Receiver’s account accordingly. Because transactions move in batches rather than individually in real time, the RDFI does not immediately confirm whether the target account is open or holds sufficient funds at the moment of checkout.
What is the typical ACH payment processing time?
Standard ACH payment processing time ranges from one to three business days for settlement, though Same Day ACH windows allow transactions to clear within hours for an additional network fee. Crucially for payment operations, ACH debits carry asynchronous failure risk. If an account lacks funds (Return Reason Code R01) or is closed (R02), the RDFI typically sends a return notice back through the network 24 to 48 hours after the transaction was initiated.
Why does an ACH Payment matter for payment teams?
Choosing the payment method ACH significantly reduces payment acceptance costs and involuntary churn. Card transactions incur percentage-based interchange and scheme fees that scale up with transaction value, whereas ACH transactions usually carry a flat fee ranging from a few cents to a few dollars. Furthermore, bank accounts do not expire like physical credit and debit cards, eliminating a major source of recurring billing declines.
Because of this reliability and cost efficiency, the volume of US B2B payments made via ACH reached 8.7 billion in 2024 (Federal Reserve Bank of Kansas City, 2026). However, payment teams must manage the operational trade-offs of asynchronous returns. A merchant that provisions high-value goods before the 48-hour return window closes risks fulfillment losses if an R01 (Insufficient Funds) or R10 (Customer Advises Unauthorized) return arrives later.
What are common use cases for an ACH Payment?
- B2B SaaS and Enterprise Software: Collecting five- and six-figure annual contract invoices where a typical credit card processing fee of between 1% and 3.5% (Source) would severely erode profit margins.
- Two-Sided Marketplaces and Gig Platforms: Disbursing bulk seller payouts and contractor earnings via ACH credit transfers without paying instant card push-to-debit fees.
- Consumer Subscription and Utility Providers: Automating monthly recurring billing for memberships, telecommunications, and insurance policies to avoid card expiration churn.
- Proptech and Real Estate Management: Processing high-ticket monthly residential and commercial rent collections through automated bank debits.
How do EFT payment vs ACH and ACH vs wire payment compare?
Payment teams frequently evaluate EFT payment vs ACH and ACH vs wire payment when designing treasury and checkout flows. An Electronic Funds Transfer (EFT) is the broad umbrella term for any digital movement of money, including cards, wires, and bank transfers. ACH and wire transfers are specific types of EFTs with distinct clearing speeds, costs, and revocability rules.
| Feature | ACH Payment | Wire Transfer | EFT (Umbrella Term) |
|---|---|---|---|
| Relationship | A specific US batch bank transfer network | A real-time gross settlement bank transfer | Category covering ACH, wires, cards, and P2P |
| Direction | Credit (push) and Debit (pull) | Credit (push) only | Varies by specific payment rail |
| Settlement Speed | Same day to 3 business days | Minutes to a few hours (real-time) | Instant to several business days |
| Cost | Low ($0.10 to $1.50 per transaction) | High ($15 to $50 per transaction) | Varies widely by rail |
| Reversibility | Subject to returns and consumer disputes | Irrevocable once settled | Depends on underlying network rules |
What are best practices for ACH Payments?
- Comply with Nacha WEB Debit Account Validation: Use instant open-banking connections (such as Plaid or Finicity) or micro-deposits to verify account ownership and check real-time balances before initiating a debit.
- Adhere strictly to Nacha retry limits: For R01 (Insufficient Funds) and R09 (Uncollected Funds) returns, Nacha rules permit a maximum of two reinitiation attempts within 180 days of the settlement date of the original entry.
- Automate Notification of Change (NOC) updates: When an RDFI returns a NOC with updated routing or account numbers, automatically update the customer vault within six banking days or prior to the next entry to prevent administrative returns.
- Monitor return rate thresholds: Keep unauthorized return rates (codes R05, R07, R10, R29, R51) below Nacha’s 0.5% (Source) threshold and overall return rates within acceptable limits to avoid acquirer fines and suspension.
How does SmartRetry help with ACH Payments?
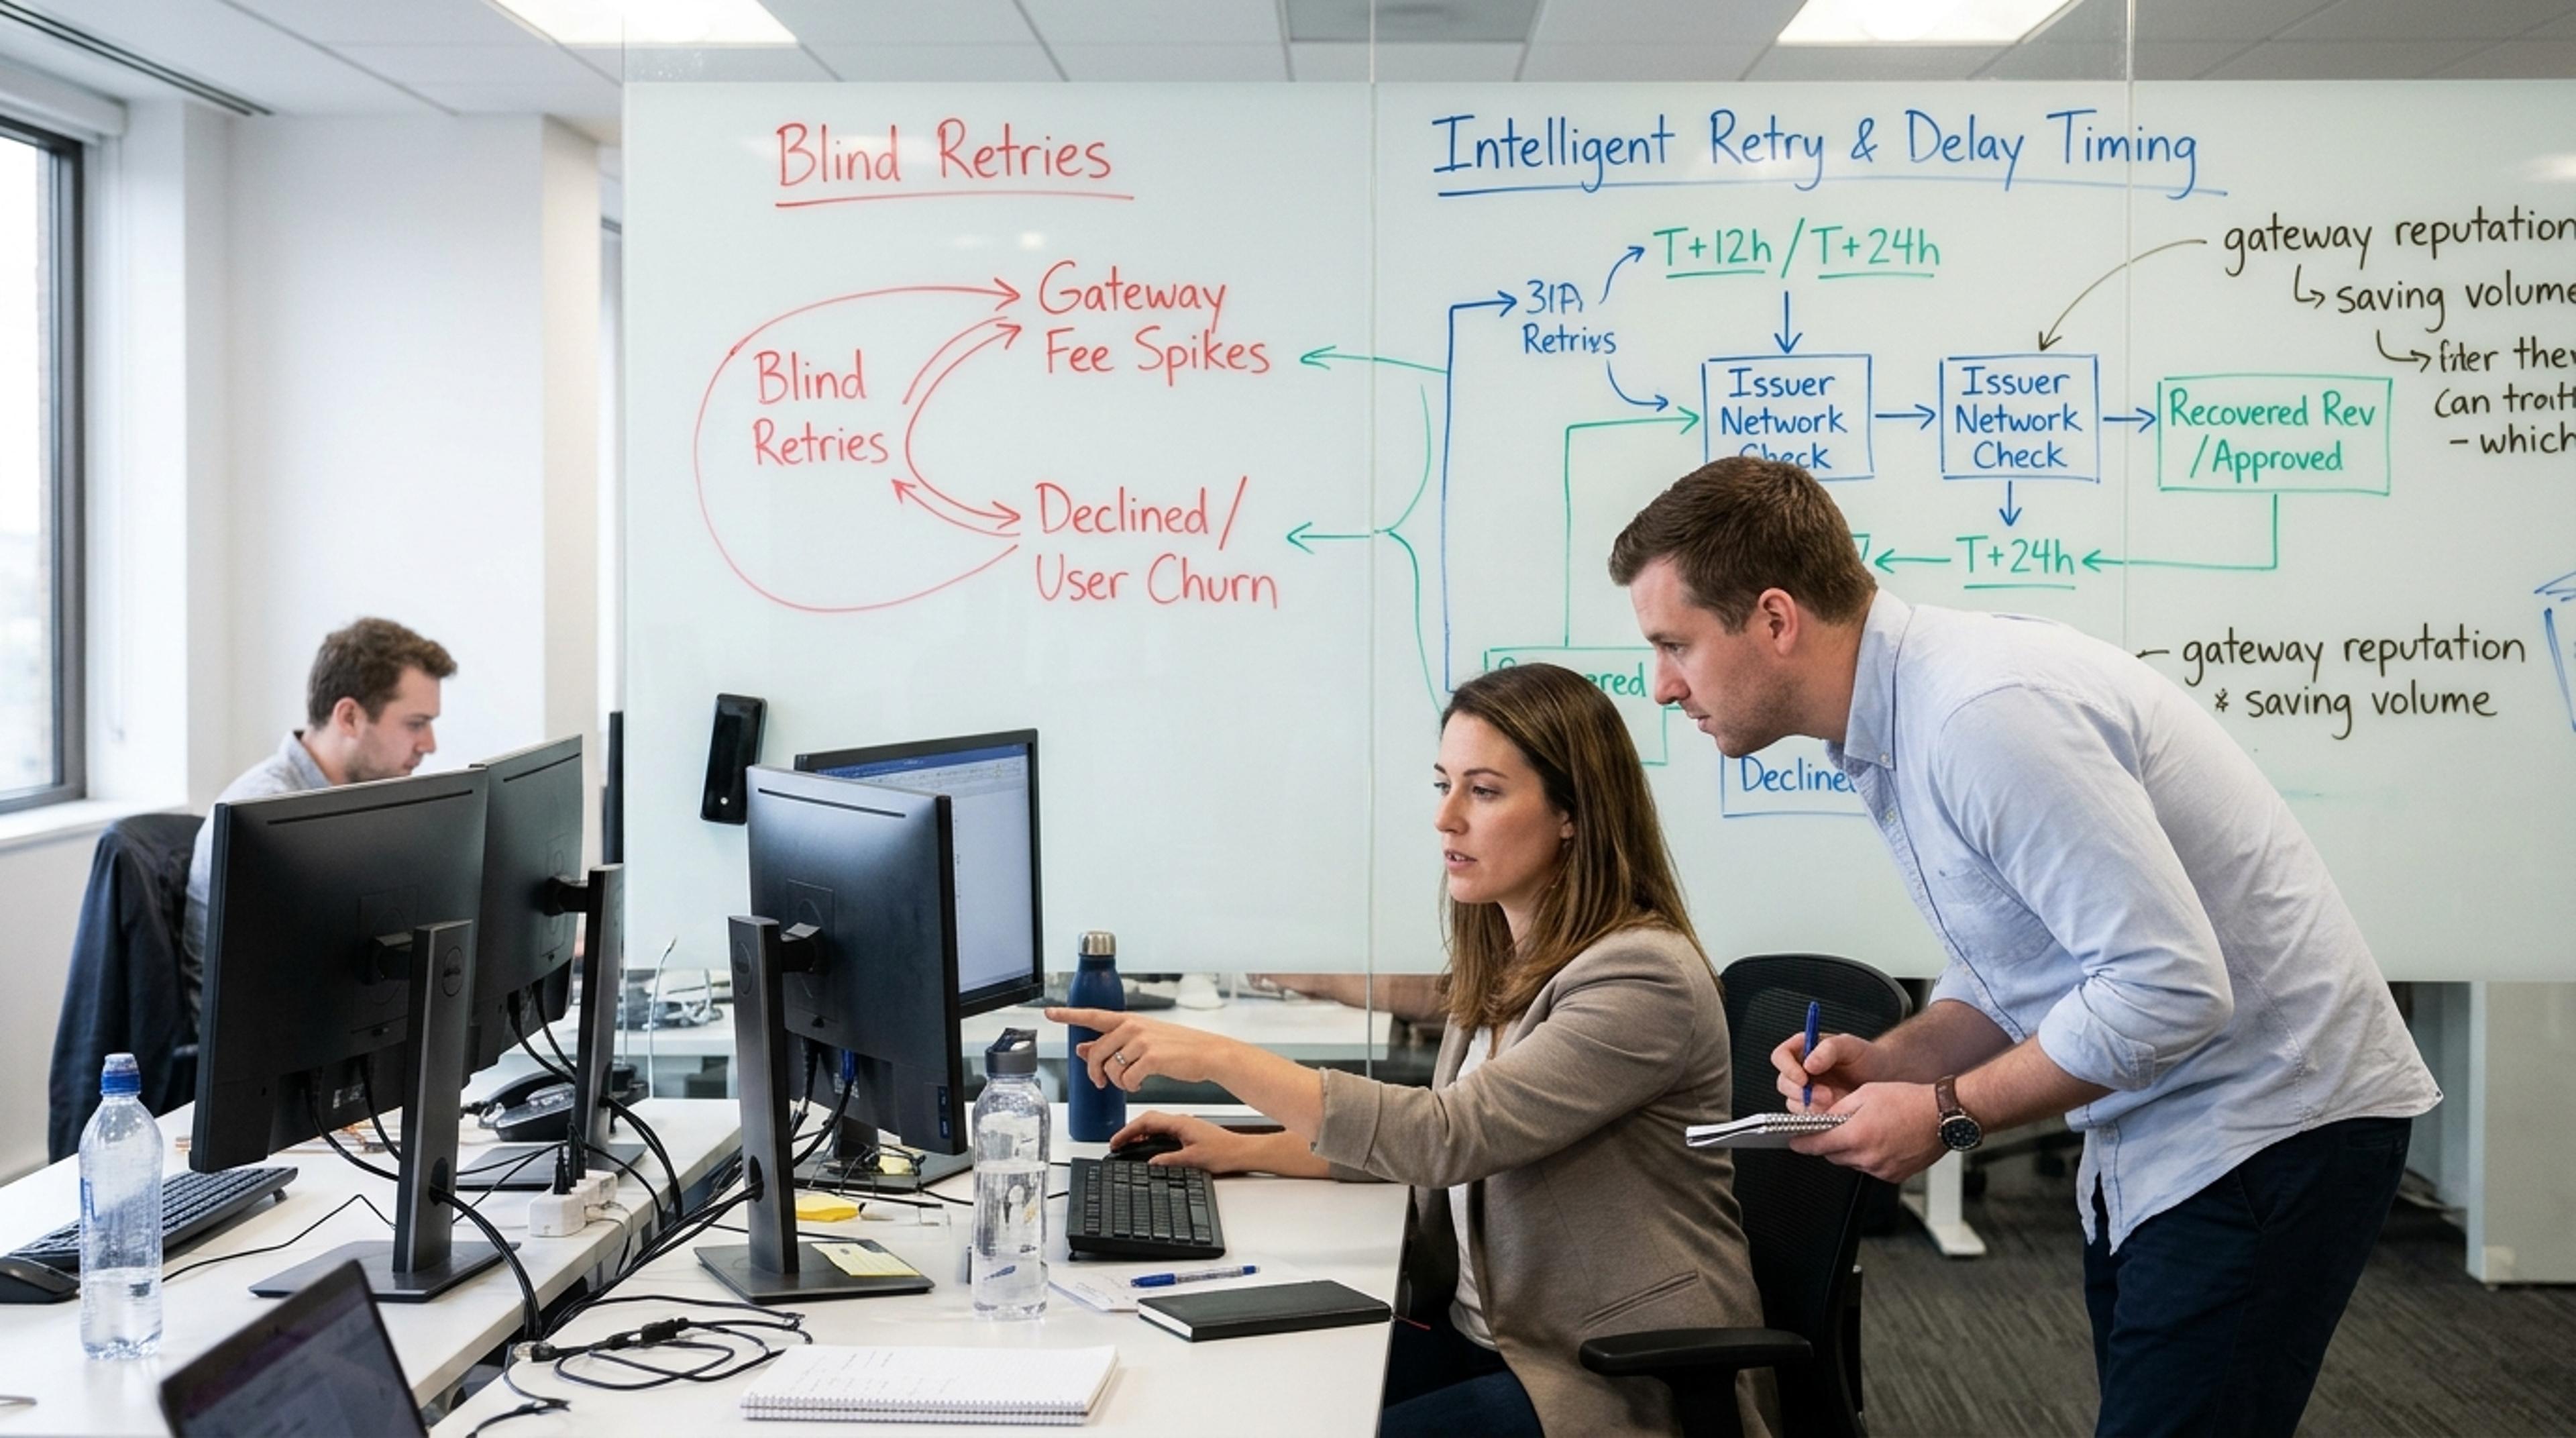
While ACH debits avoid card expiration declines, failed bank pulls due to insufficient funds (R01) still cause significant revenue leakage for recurring merchants. Blindly retrying a returned ACH debit the next day frequently fails and wastes one of the two permitted Nacha reinitiation attempts. SmartRetry leverages context-aware retry logic to analyze transaction context, historical pay cycles, and return codes to schedule ACH retries on dates when customer bank accounts are most likely to be funded, such as standard payroll days. Explore SmartRetry’s payment recovery software to recover failed bank debits while maintaining strict compliance with Nacha reinitiation rules.