
A merchant account is a specialized commercial bank account established with an acquiring bank that enables a business to accept electronic credit and debit card payments, temporarily holding settled transaction funds to account for processing fees, refunds, and chargebacks before transferring net payouts to the business’s corporate checking account.
What is a merchant account and how does it work?
To understand what is a merchant account, payment teams must view it as an underwriting line of credit rather than a standard checking account. Because cardholders can dispute transactions months after a purchase, an acquiring bank or merchant account provider assumes financial liability when onboarding a business. During underwriting, the acquirer evaluates the business’s credit history, processing volume, fulfillment model, and chargeback risk before issuing a unique Merchant Identification Number (MID).
Once live, the account acts as the financial clearinghouse for card transactions. When a customer initiates a checkout, the front-end technology captures the card details and routes the request to the processor. After the cardholder’s issuing bank approves the authorization and the transaction is captured at end-of-day batching, the card networks clear the transaction. The issuing bank transfers the funds to the acquiring bank, which deposits them into the merchant account.
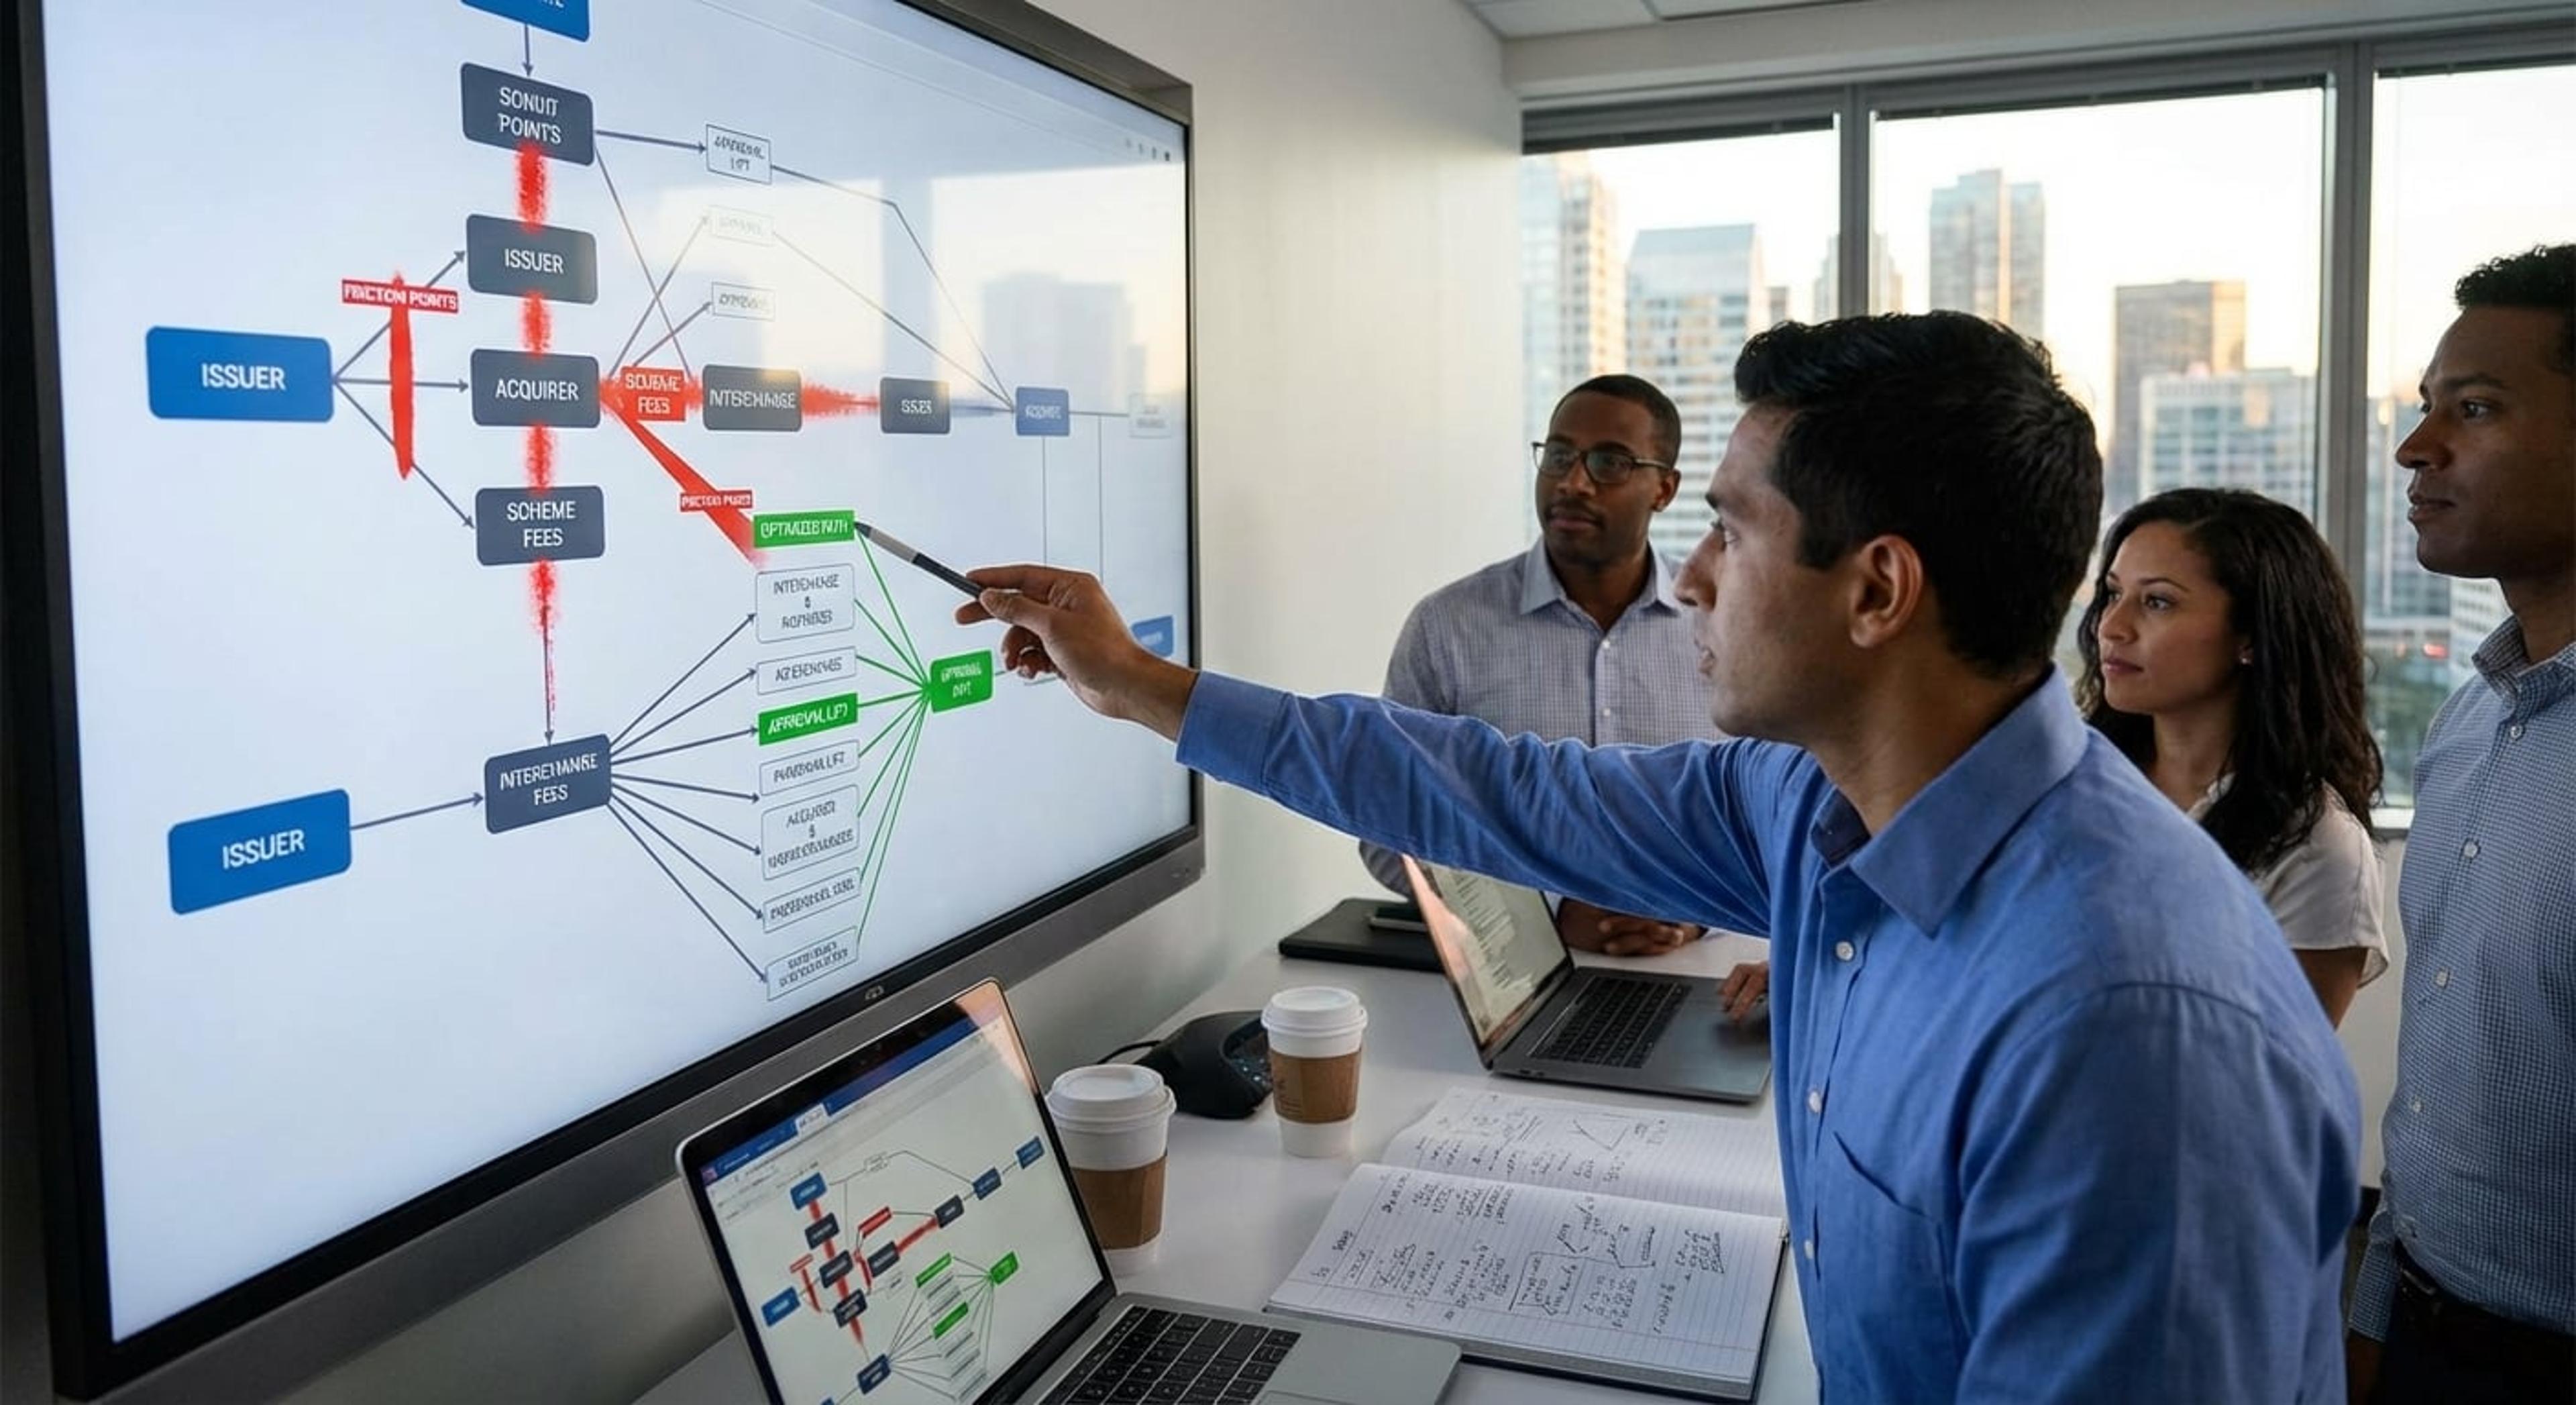
Before releasing the capital, the acquiring bank deducts the merchant discount rate, which includes interchange fees, card scheme assessments, and the acquirer’s markup. If the business operates with elevated dispute exposure, the acquirer may also hold back a rolling reserve inside the account. Finally, the remaining net settlement funds are swept via ACH or wire into the merchant’s primary operating bank account on an agreed schedule, typically ranging from one to three business days.
Why does a merchant account matter for payment teams?
The structure of a merchant account directly governs a business’s authorization rates, processing costs, and settlement liquidity. Early-stage companies often use a payment facilitator (PayFac) that aggregates thousands of sub-merchants under a single master account. However, scaling enterprises require a dedicated merchant account for ecommerce to gain granular control over their MID reputation, descriptors, and interchange-plus pricing.
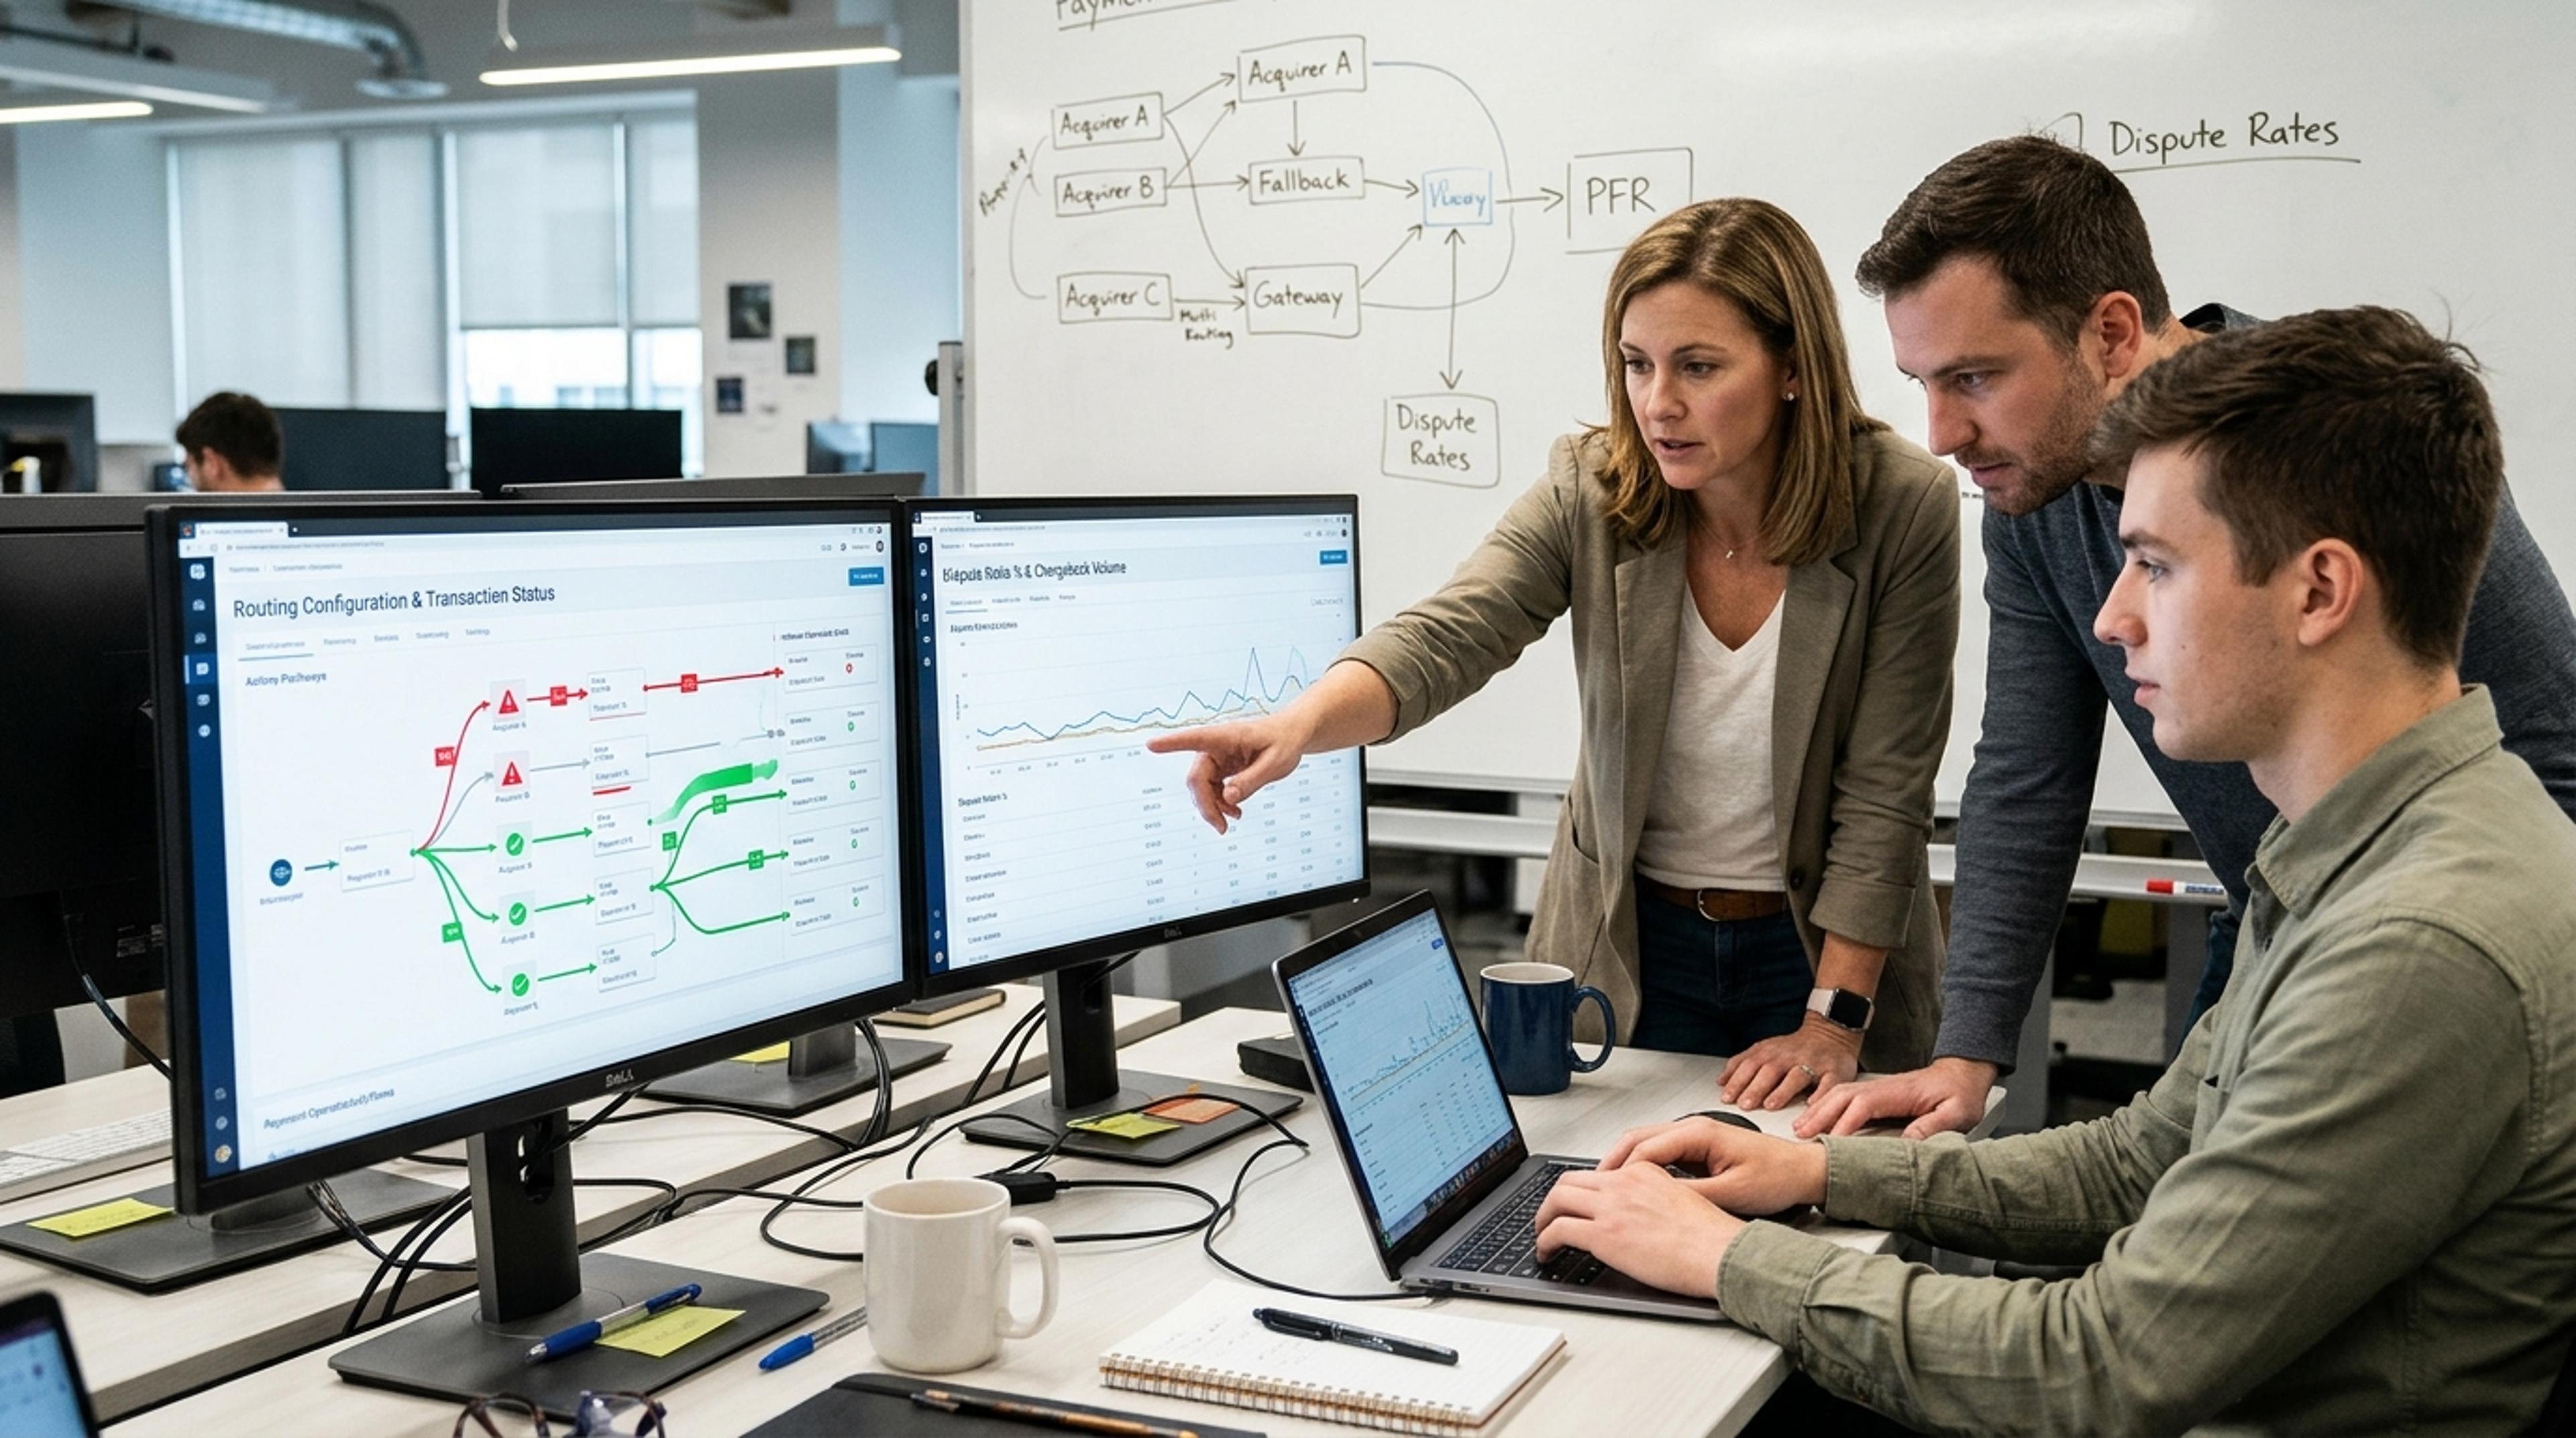
Relying on a single acquiring relationship creates operational vulnerability and sub-optimal cross-border performance. To enhance payment flexibility, maximize authorization rates, and expand geographic coverage, eCommerce merchants typically use 3 to 4 acquiring banks and payment gateways on average (Merchant Risk Council). Distributing volume across multiple accounts prevents a single risk review or technical outage from halting revenue collection.
What are common use cases for a merchant account?
- SaaS and subscription businesses: Provisioning dedicated accounts to separate initial customer-initiated transactions (CITs) from recurring merchant-initiated transactions (MITs), protecting baseline approval rates from recurring billing churn.
- Global ecommerce retail: Establishing local accounts in target regions, such as the UK, EU, and North America, so transactions process domestically rather than triggering cross-border issuer declines and extra scheme fees.
- Nutraceutical, gaming, and CBD businesses: Securing a specialized high risk merchant account with an acquirer that tolerates higher dispute thresholds in exchange for rolling reserves and customized fraud controls.
- Travel and online travel agencies (OTAs): Maintaining high-limit accounts underwritten specifically for long fulfillment windows, where cardholders pay months in advance of the actual flight or hotel stay.
How does a merchant account payment gateway differ from a merchant account?
Payment teams frequently evaluate a merchant account payment gateway alongside their acquiring setup, though the two serve separate functions in the transaction lifecycle.
| Attribute | Merchant Account | Payment Gateway |
|---|---|---|
| Primary Function | Underwrites financial risk, receives settled funds from issuers, and disburses net payouts. | Encrypts card data at checkout and routes authorization messages between merchant and processor. |
| Layer Type | Financial and regulatory banking entity (assigned a MID). | Technical software infrastructure and API layer. |
| Custody of Funds | Temporarily holds transaction funds and reserves before bank payout. | Never touches, holds, or settles monetary funds. |
What are best practices for managing a merchant account?
- Segment MIDs by business model: Isolate high-dispute product lines or trial offers onto their own dedicated MIDs so elevated chargebacks do not contaminate the approval rates of core revenue streams.
- Monitor dispute ratios per MID: Track Visa and Mastercard dispute thresholds at the individual account level rather than blending metrics across the company, ensuring no single account enters card network monitoring programs.
- Communicate volume spikes in advance: Notify your acquirer’s risk team before major seasonal sales or product launches to prevent automated velocity filters from freezing settlement payouts.
- Avoid aggressive retry loops on a single MID: Repeatedly retrying declined cards on the same account signals desperation or fraud to issuers, which degrades the reputation of that specific MID.
How does SmartRetry help with merchant accounts?
SmartRetry helps payment teams maximize the revenue recovered across their acquiring infrastructure while protecting the health of each underlying MID. When a transaction declines, SmartRetry analyzes the specific issuer response code, card brand, and transaction context to determine whether a retry is viable and exactly when to execute it. By suppressing unrecoverable hard declines and spacing out soft decline retries using machine learning, SmartRetry prevents merchants from tripping network retry limits and damaging their standing with acquiring banks. Explore the SmartRetry intelligent payment recovery platform to see how optimized retry logic increases approval rates across your acquiring stack.