
A recurring payment is an automated transaction in which a customer grants a merchant ongoing permission to charge their payment method on a predetermined schedule. Once the initial mandate is established, subsequent charges process automatically as merchant-initiated transactions without requiring active customer authentication for each billing cycle.
How does a recurring payment work?
In technical payment operations, the recurring payment meaning centers on two distinct phases: the initial setup and subsequent renewals. During the setup phase, the customer completes a checkout flow and agrees to a billing mandate. This first transaction is flagged as a Customer-Initiated Transaction (CIT), which typically requires Strong Customer Authentication (SCA) in regulated regions and establishes the stored credential framework.
Once authorized, the Payment Service Provider (PSP) or card network replaces the sensitive payment data with a secure token and generates a network Transaction ID (TID). For every subsequent billing cycle, the merchant’s billing engine triggers a Merchant-Initiated Transaction (MIT). The merchant submits the stored token along with the original network TID to prove to the issuing bank that a valid recurring agreement exists. Because the customer is not present at checkout, these automated renewals bypass 3D Secure challenges, shifting the burden of approval optimization entirely onto proper credential flagging and retry logic.
How do a recurring credit card payment and a recurring ACH payment differ?
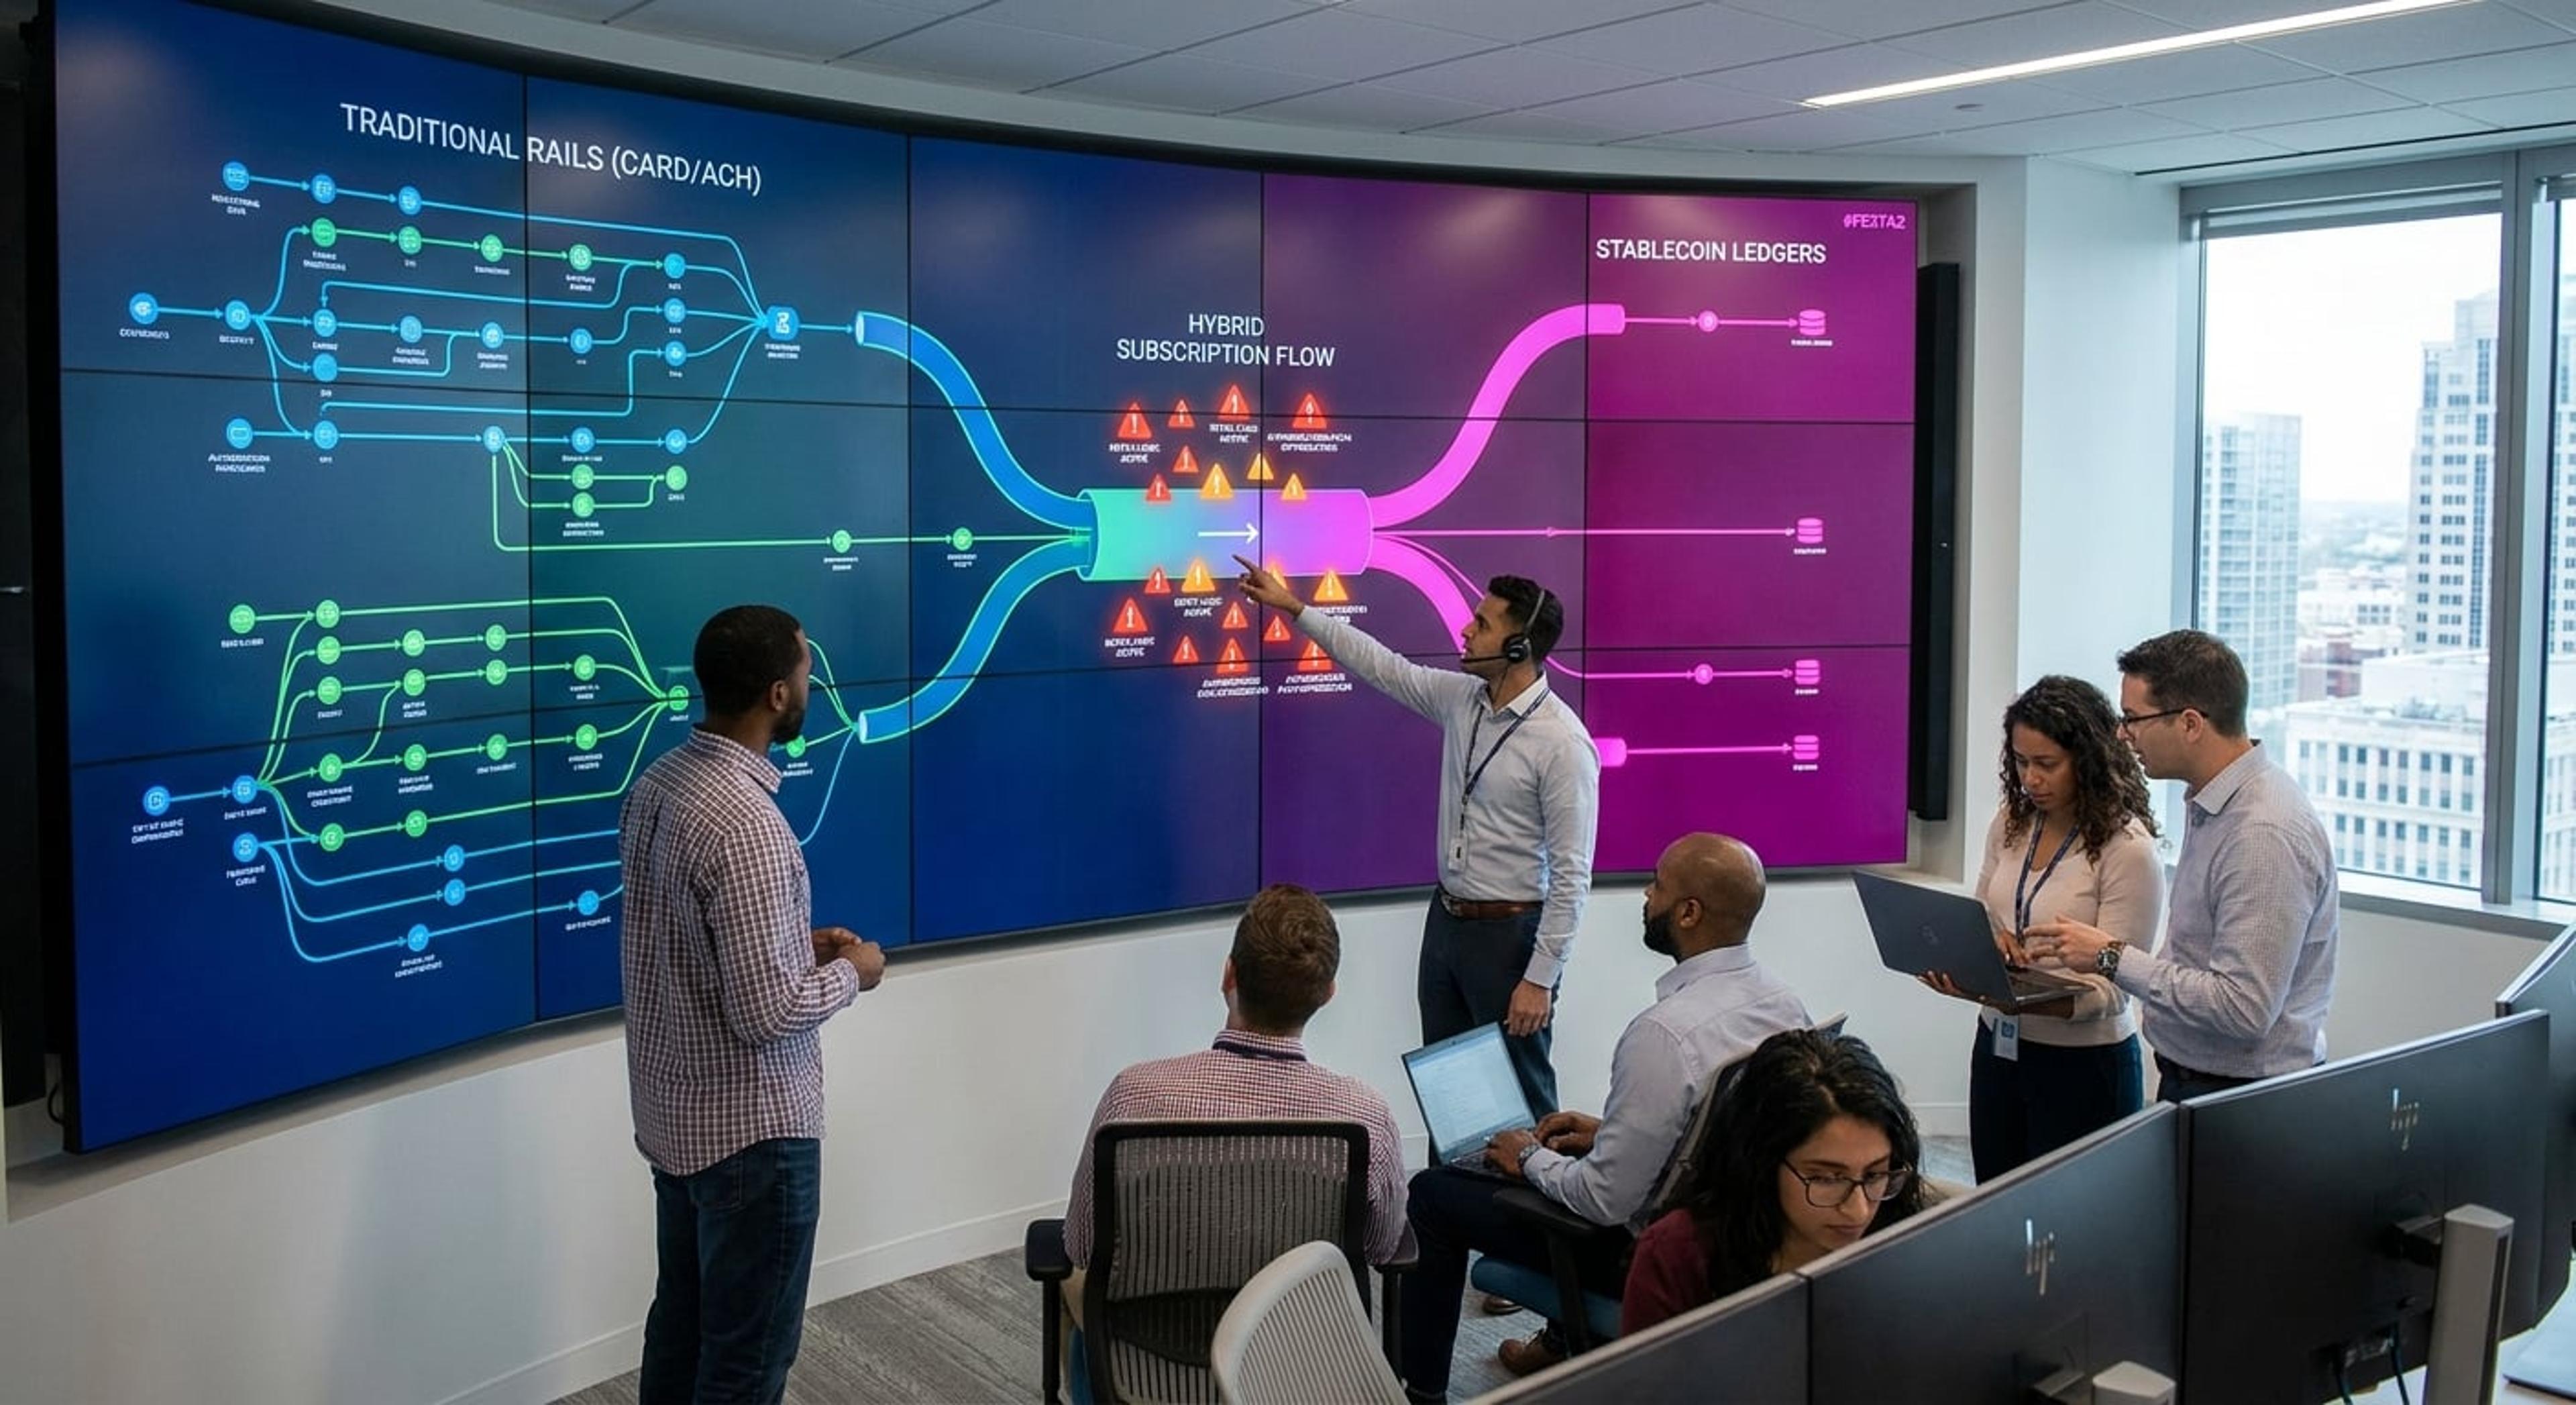
A recurring credit card payment runs over card network rails like Visa and Mastercard, providing instant authorization responses. However, cards are highly susceptible to involuntary churn caused by expiration dates, lost or stolen card replacements, and strict issuer fraud filters.
Conversely, a recurring ACH payment (or regional bank debit equivalent like SEPA or Bacs Direct Debit) pulls funds directly from a customer’s bank account. While bank debits have lower processing costs and do not expire, settlement takes several business days. An ACH transaction can appear successful initially only to return a failure code days later due to insufficient funds or revoked mandates.
Why does a recurring payment matter for payment teams?
Recurring billing models provide predictable cash flow and higher customer lifetime value, but they introduce severe operational fragility. Because renewal transactions occur without the customer present, any payment decline stops revenue collection immediately unless the merchant has an automated recovery workflow.
Subscription businesses currently face an average monthly churn rate of 20% (Mastercard, 2026). A substantial portion of this attrition is involuntary churn, where a loyal customer intends to keep their subscription, but their recurring monthly payment fails due to a soft decline like insufficient funds, issuer velocity limits, or temporary network outages. Payment teams must balance aggressive recovery strategies against card network compliance rules, which penalize excessive retry attempts and high chargeback ratios.
What are common use cases for a recurring payment?
- SaaS and B2B software: Cloud platforms bill businesses a fixed monthly or annual fee for seat licenses, often combining base recurring charges with usage-based overages.
- Digital media and streaming: Video, music, and news platforms process high-volume, low-ticket monthly renewals across global consumer card portfolios.
- Ecommerce retail subscription boxes: Direct-to-consumer brands charge customers on a scheduled cadence to ship physical consumables like coffee, cosmetics, or pet supplies.
- Fitness and wellness memberships: Gyms and health apps collect scheduled membership dues, frequently utilizing a mix of credit cards and recurring bank debits.
Recurring Payment vs One-Time Payment
| Attribute | Recurring Payment | One-Time Payment |
|---|---|---|
| Transaction Type | Customer-Initiated (setup) followed by Merchant-Initiated (renewals) | Customer-Initiated Transaction (CIT) |
| Authentication | SCA required at setup; renewals are exempt via MIT flags | Subject to 3DS/SCA on every transaction |
| Credential Storage | Mandatory tokenization and network TID chaining | Optional (only if saved for future unscheduled use) |
| Decline Recovery | Automated background retries and customer dunning emails | Real-time checkout prompts for an alternative payment method |
What are best practices for a recurring monthly payment?
- Pass accurate CIT/MIT indicators: Always include the original network Transaction ID and correct recurring flags in the authorization payload so issuers recognize the exemption and do not decline the charge for missing authentication.
- Enable Network Account Updaters: Integrate Visa Account Updater (VAU) and Mastercard Automatic Billing Updater (ABU) to automatically refresh expired card dates and replaced PANs before the billing date arrives.
- Classify declines before retrying: Distinguish between hard and soft declines. Never retry a hard decline (such as stolen cards or invalid accounts), as doing so violates scheme rules and incurs penalty fees.
- Use clear billing descriptors: Configure dynamic descriptors that clearly display your brand name and support contact to prevent customers from disputing unrecognized recurring charges.
How does SmartRetry help with a recurring payment?
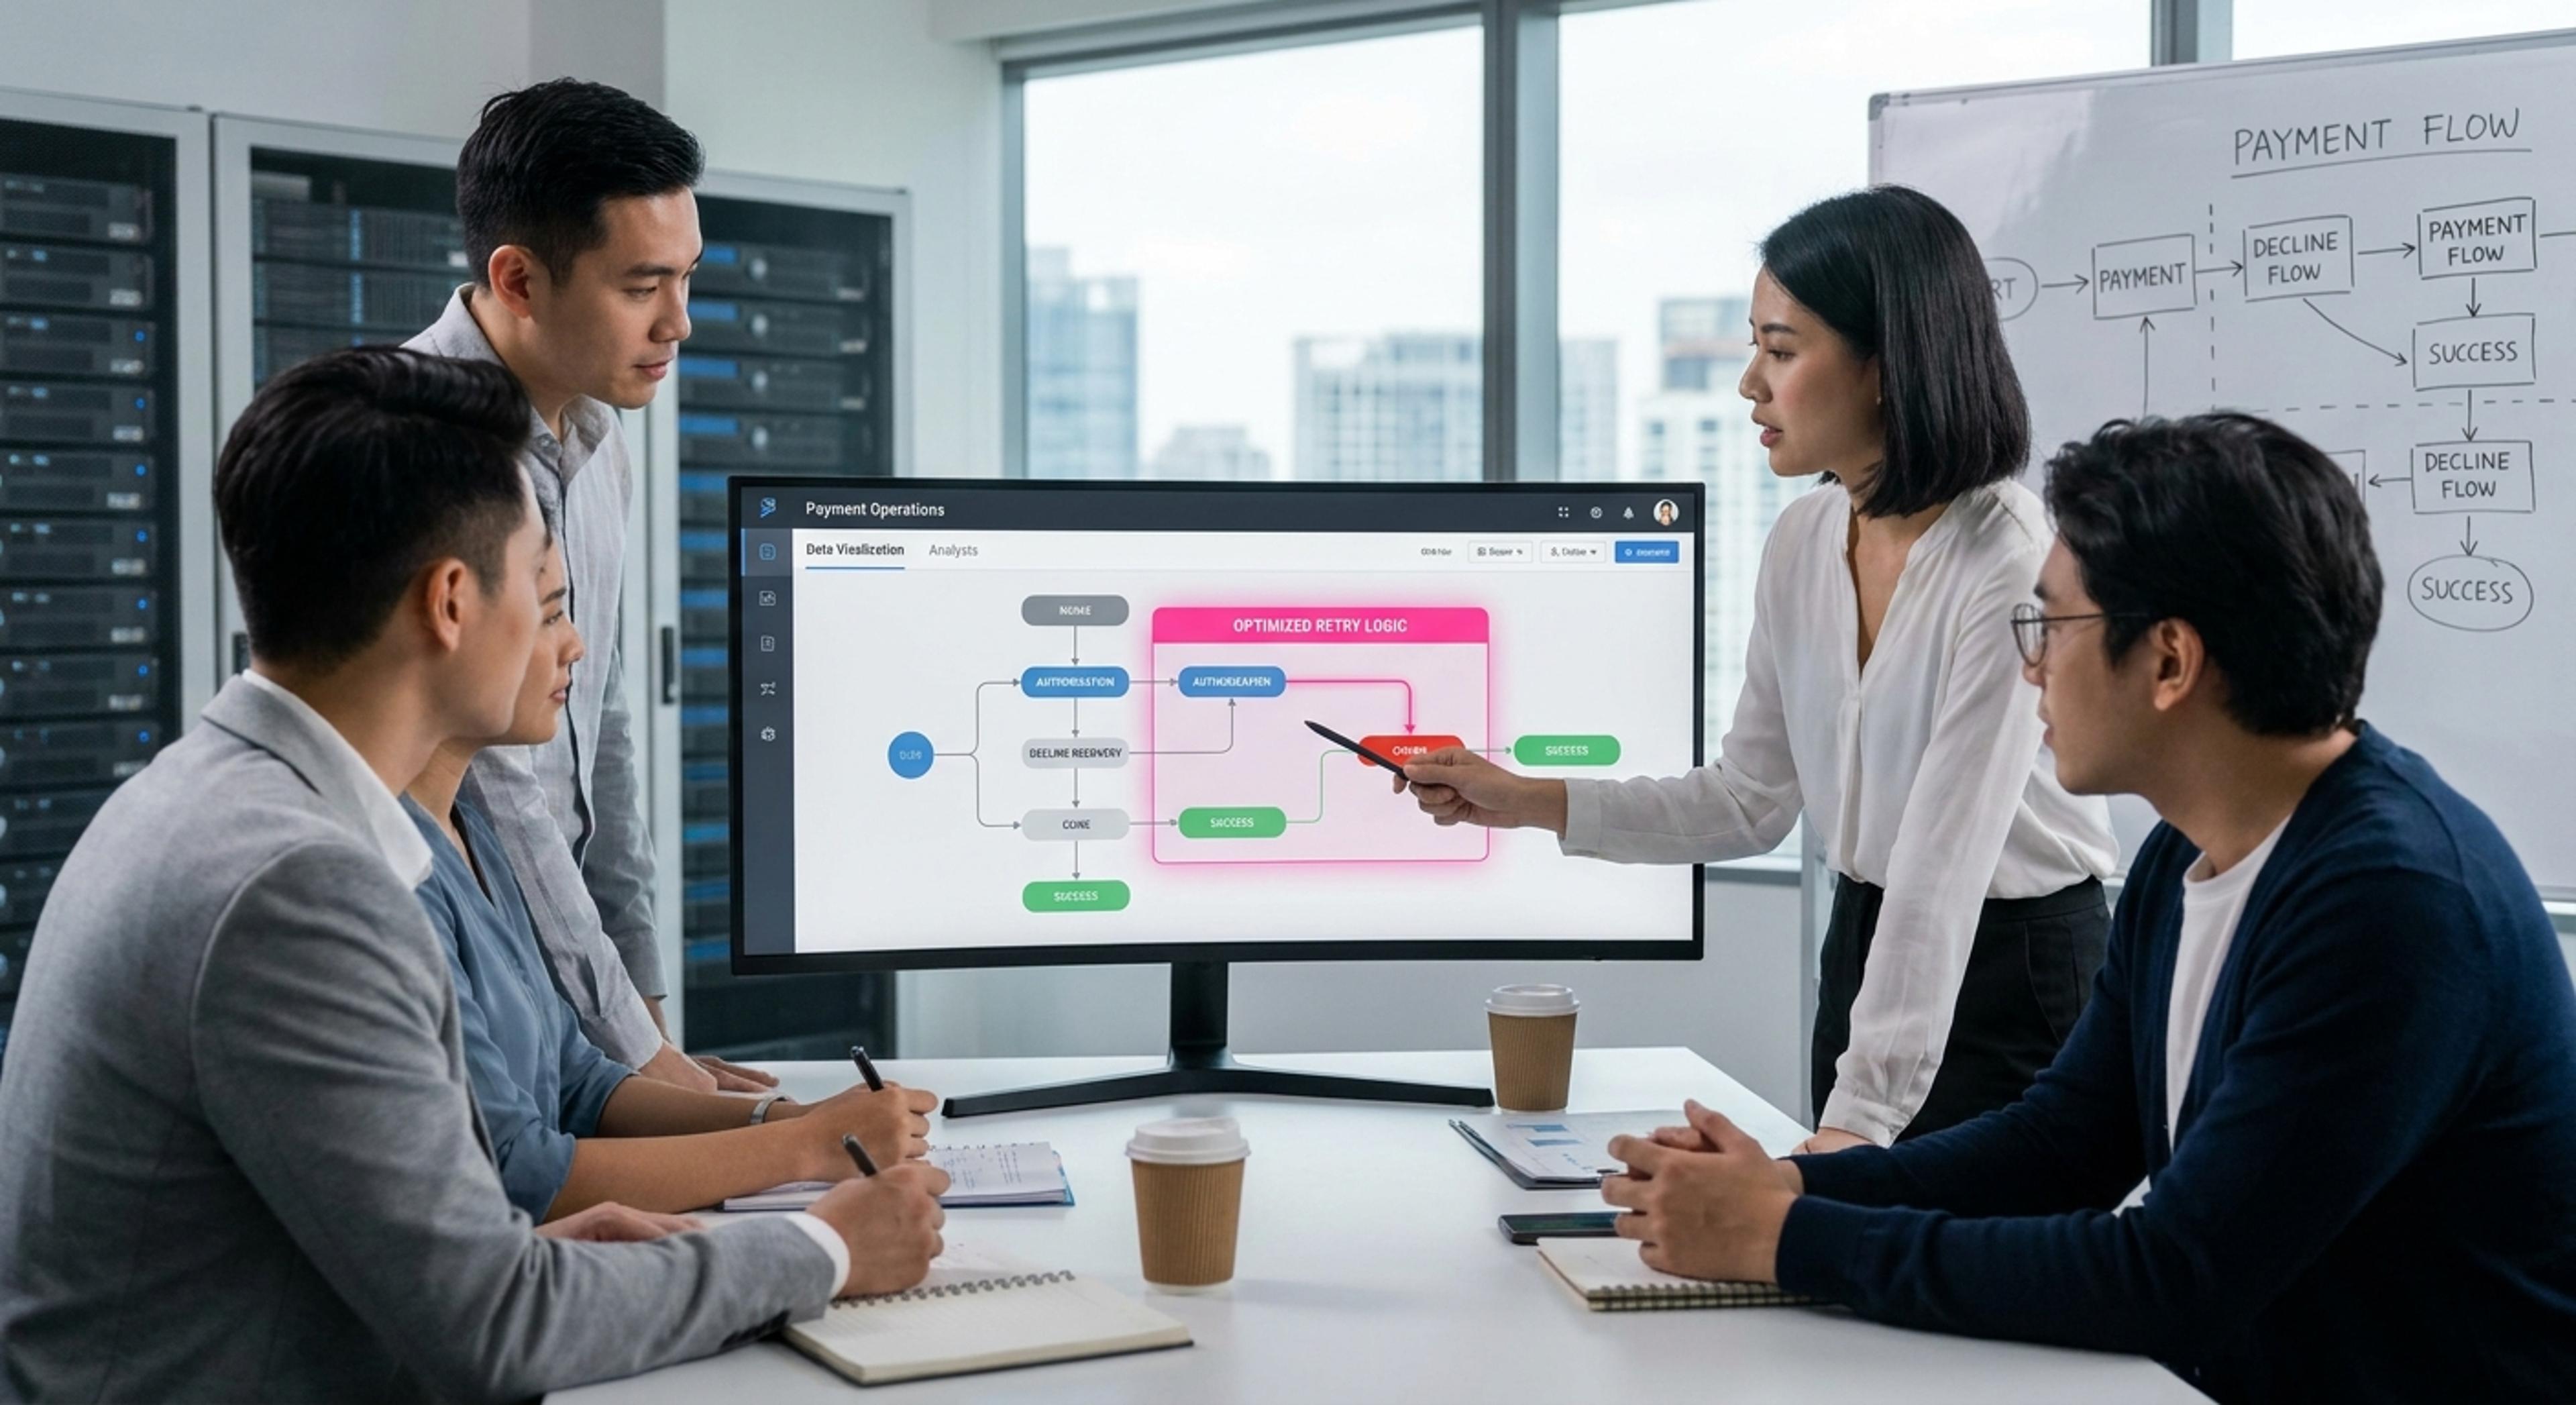
SmartRetry maximizes revenue recovery for recurring billing operations by replacing static, rule-based retry schedules with machine learning optimization. When a scheduled renewal fails due to a soft decline, SmartRetry analyzes issuer behavior, decline reason codes, and historical transaction data to determine the exact day and time a retry is most likely to succeed. Explore SmartRetry’s intelligent retry engine to reduce involuntary churn and lift recurring approval rates across your payment stack.