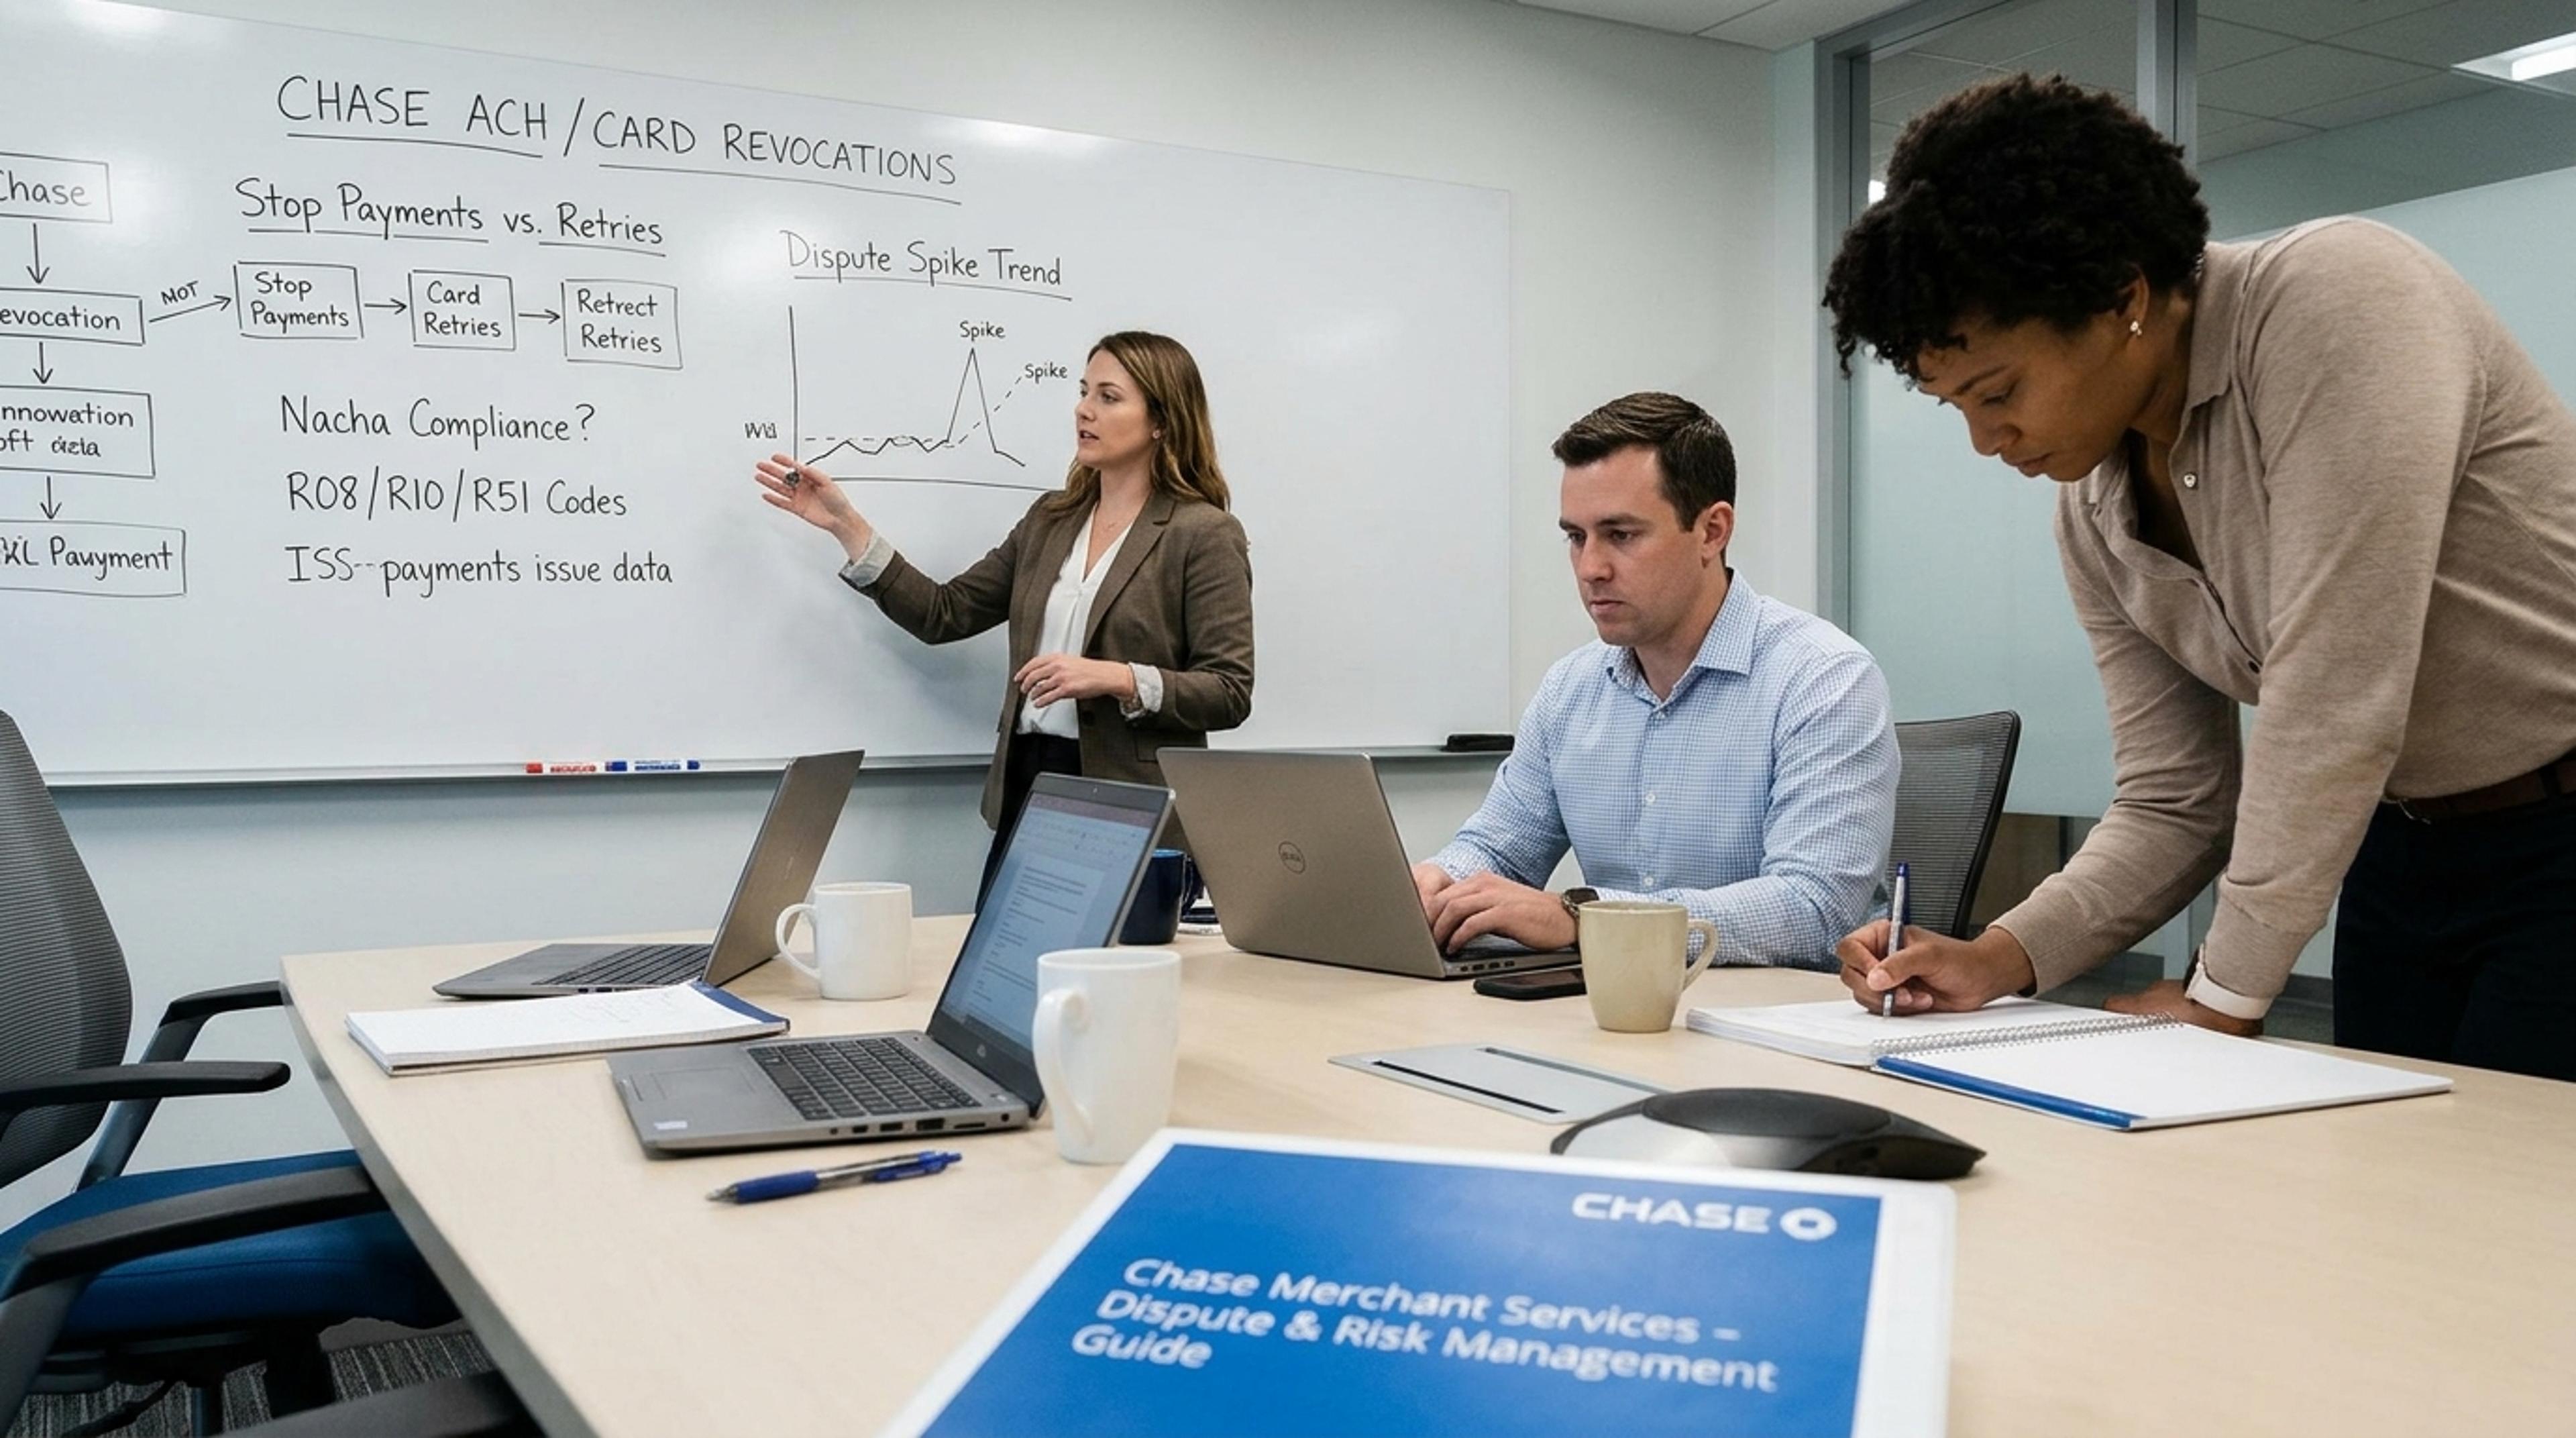

A stop payment is a formal instruction from an account holder to their financial institution to cancel a pending check, ACH debit, or recurring card authorization before settlement occurs, causing the issuing bank to reject the transaction and return a hard decline or return code to the merchant.
How does a Stop Payment work?
A stop payment order intercepts a transaction before funds are permanently settled between the customer’s bank and the merchant’s acquiring bank. When a consumer contacts their bank to stop a payment, the financial institution places a block in its authorization or clearing system matching the specific merchant identifier, check number, or transaction amount. If the payment has already cleared and settled, a stop payment cannot be executed, and the account holder must pursue a dispute or chargeback instead.
What happens when a customer asks how to stop an ACH payment or check?
In bank-to-bank and paper rails, account holders can stop a check payment or revoke an automated clearing house authorization by notifying their depository institution at least three business days before the scheduled settlement. When a customer researches how to stop an ACH payment and submits the request, the Receiving Depository Financial Institution (RDFI) rejects the incoming debit entry and sends an R08 (Payment Stopped) or R07 (Authorization Revoked by Customer) return code back through the network to the merchant’s Originating Depository Financial Institution (ODFI).
What happens when a customer asks how to stop payment on credit card?
Card networks handle revocation orders differently than traditional bank rails. When a cardholder asks their issuer how to stop an automatic payment or how to stop payment on credit card billing, the issuing bank places an issuer-level block on the merchant’s specific Merchant ID (MID) or Visa/Mastercard token. When the merchant’s payment gateway submits the next recurring authorization request, the issuer automatically rejects it with a hard decline code, such as Visa Decline Code R0, R1, or R3 (Stop Payment Order or Revocation of Authorization).
Why does Stop Payment matter for payment teams?
Stop payment orders directly impact merchant churn, payment operational costs, and acquirer compliance. Consumers frequently bypass merchant cancellation flows and instruct their banks to block future charges directly; 25% of global consumers have blocked a payment they believed was fraudulent (Mastercard, 2026). When a merchant receives a stop payment decline or return code, card network and Nacha rules strictly prohibit retrying that specific transaction.
Ignoring a revocation code and continuing to rebill the customer through automated retry logic triggers severe penalties. Card networks levy non-compliance fines for retrying after a revocation code, and issuers will escalate subsequent authorization attempts into formal chargebacks. Payment operations teams must configure their retry engines to immediately recognize stop payment decline codes and cease billing.
What are common use cases for Stop Payment?
- SaaS and Subscription Merchants: A B2B or B2C subscriber forgets to cancel a free trial before conversion or finds the online cancellation flow too complex, prompting them to call their issuer to block the recurring card charge.
- Digital Goods and Gaming Platforms: A parent notices recurring microtransactions or season-pass renewals on their bank statement that they do not recognize and instructs their bank to block the merchant ID.
- Ecommerce Retail (BNPL and Installments): A shopper disputes the quality of delivered physical goods and places an ACH stop payment on the remaining scheduled installment debits.
- Property Management and B2B Marketplaces: A tenant or commercial buyer initiates a check or ACH transfer for an invoice, realizes the amount is incorrect, and submits an order to stop a check payment before it clears.
Stop Payment vs Chargeback
| Attribute | Stop Payment | Chargeback |
|---|---|---|
| Timing | Executed before transaction authorization or settlement is finalized. | Executed after the transaction has cleared and funds have settled. |
| Primary Mechanism | Proactively blocks an upcoming check, ACH debit, or recurring card charge. | Reverses a completed transfer of funds back to the consumer’s account. |
| Network Signals | Returns hard decline codes (e.g., Card R0/R1/R3) or ACH return codes (R07/R08). | Generates formal dispute reason codes (e.g., Visa 10.4 or 13.2) via the acquirer. |
| Fee Bearer | The consumer typically pays a stop payment fee to their bank. | The merchant pays a non-refundable chargeback fee to their acquirer. |
What are best practices for handling a Stop Payment?
- Halt automated retries immediately: Map card network decline codes R0, R1, R3 and ACH return codes R07 and R08 as terminal hard declines in your payment orchestration layer so your system never retries them.
- Automate subscription status updates: Connect your payment gateway webhooks directly to your billing CRM so that a stop payment decline automatically pauses the customer’s subscription and triggers an outreach email requesting an alternative payment method.
- Simplify self-serve cancellation flows: Provide clear, one-click cancellation and pause options within your customer portal to prevent users from turning to their issuing bank to block payments.
- Use clear billing descriptors: Configure recognizable dynamic descriptors on both card and ACH statements so customers do not mistake legitimate recurring charges for unauthorized fraud.
How does SmartRetry help with Stop Payment declines?
SmartRetry protects merchants from network compliance penalties by automatically distinguishing between recoverable soft declines and terminal revocation orders like stop payments. When an issuer returns a stop payment or revocation code, SmartRetry immediately suppresses further retry attempts on that transaction while routing recoverable declines through machine-learning-driven schedules. Explore SmartRetry’s intelligent retry engine to learn how automated decline classification maximizes recovery without risking compliance fines.