
A credit card is a payment instrument issued by a financial institution that enables a cardholder to purchase goods and services using a revolving line of credit, routing transaction requests through card networks for real-time issuer authorization before settling funds to the merchant’s acquiring bank.
How does a Credit Card work?
Credit card processing operates through a four-party or three-party payment model involving the cardholder, merchant, acquiring bank, card network, and issuing bank. When a customer initiates a transaction at checkout, the merchant’s payment gateway encrypts the card details, including the Primary Account Number (PAN), expiration date, and card verification value (CVV), and sends an authorization request to the acquiring processor.
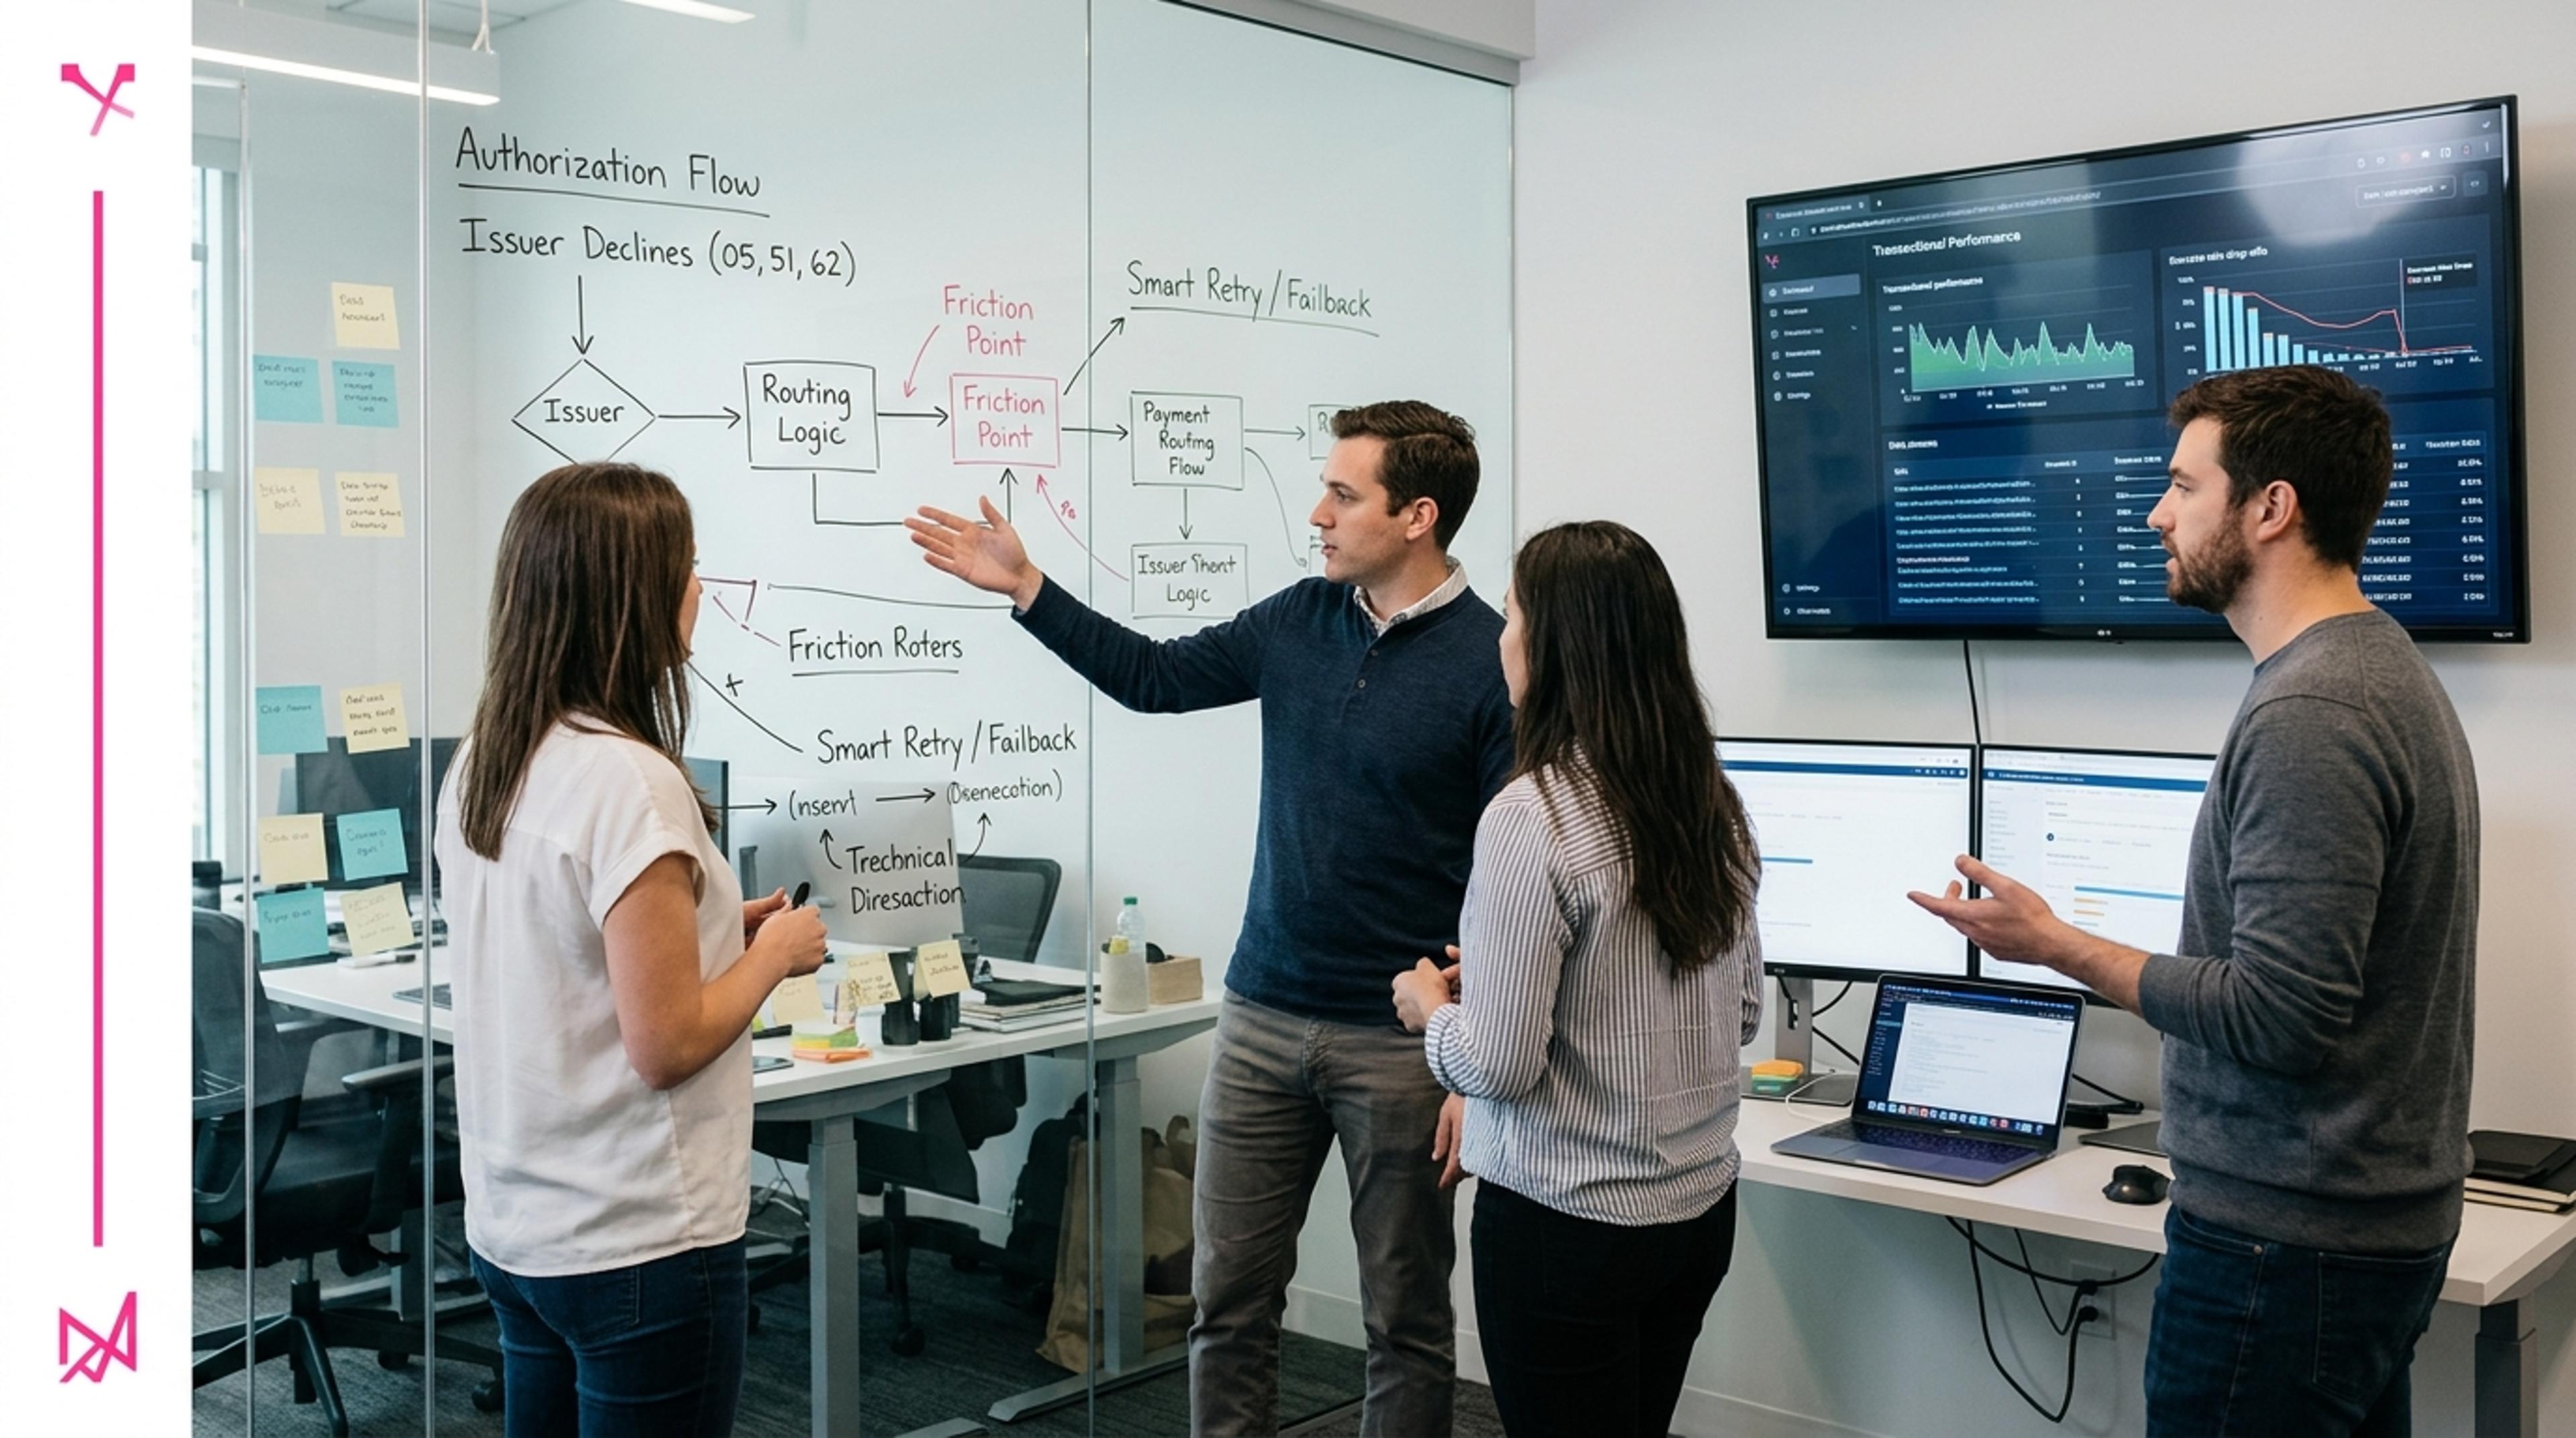
The acquirer routes this payload through the relevant card scheme, such as Visa, Mastercard, or American Express, to the issuing bank. For example, if a consumer uses a Chase credit card or a Capital One credit card, JPMorgan Chase or Capital One acts as the issuer evaluating the transaction. In retail environments, merchants might also process a co-branded or private-label Best Buy credit card, which routes through specialized retail financing rails.
The issuing bank verifies the cardholder’s identity, checks the account for sufficient open-to-buy credit, and runs real-time fraud scoring algorithms. If approved, the issuer places a temporary hold on the cardholder’s credit line and returns an authorization code to the merchant. If rejected, the issuer returns a specific decline code indicating the reason, such as insufficient credit or suspected fraud. Approved transactions are later batched for clearing and settlement, where the issuer transfers the funds, minus interchange fees, through the network to the merchant’s acquiring bank.
Why do Credit Cards matter for payment teams?
Credit cards are a primary driver of global commerce, with global network brand cards generating $36.741 trillion in purchase volume worldwide in 2024 (Nilson Report, 2025). For payment operations teams, managing credit card acceptance requires balancing high conversion rates against processing costs and fraud exposure.
Because credit card transactions rely on an issuer’s risk appetite and the cardholder’s available credit limit, they are susceptible to false declines and involuntary churn. Issuers apply stricter risk rules to credit products than to authenticated bank transfers, meaning legitimate transactions frequently fail due to velocity triggers, cross-border flags, or expired credentials. Furthermore, credit cards carry higher interchange fees than debit cards and expose merchants to chargeback liability if a cardholder disputes a billing statement.
What are common use cases for Credit Cards?
- SaaS and subscription billing: Recurring revenue businesses store tokenized credit card credentials on file to automate monthly or annual billing cycles, relying on automated retry logic when credit limits are temporarily exhausted.
- Travel and OTA platforms: Airlines, hotels, and online travel agencies utilize credit cards to place pre-authorization holds for incidentals and high-ticket bookings, capturing the final settlement amount only upon checkout or itinerary completion.
- Ecommerce retail: Online retailers accept credit cards for immediate checkout conversion, leveraging network tokenization and 3D Secure authentication to shift fraud liability on high-value physical goods.
- Digital goods and gaming: Gaming platforms process high-velocity microtransactions on saved credit cards, requiring fine-tuned fraud filters to prevent card testing without blocking legitimate in-game purchases.
Credit Card vs Debit Card
| Attribute | Credit Card | Debit Card |
|---|---|---|
| Funding Source | Revolving line of credit extended by the issuing bank. | Pre-deposited funds in the cardholder’s checking or bank account. |
| Primary Decline Drivers | Credit limit exceeded, suspected fraud, or expired card credentials. | Insufficient account funds (NSF) and daily withdrawal limits. |
| Interchange Cost | Higher percentage fees to compensate issuers for credit risk and rewards programs. | Lower, often regulated fees due to immediate fund availability and lower default risk. |
| Retry Timing Strategy | Responds well to retries timed around monthly statement closing dates when credit lines reset. | Responds best to retries aligned with traditional bi-weekly or monthly payroll deposit dates. |
What are best practices for Credit Card processing?
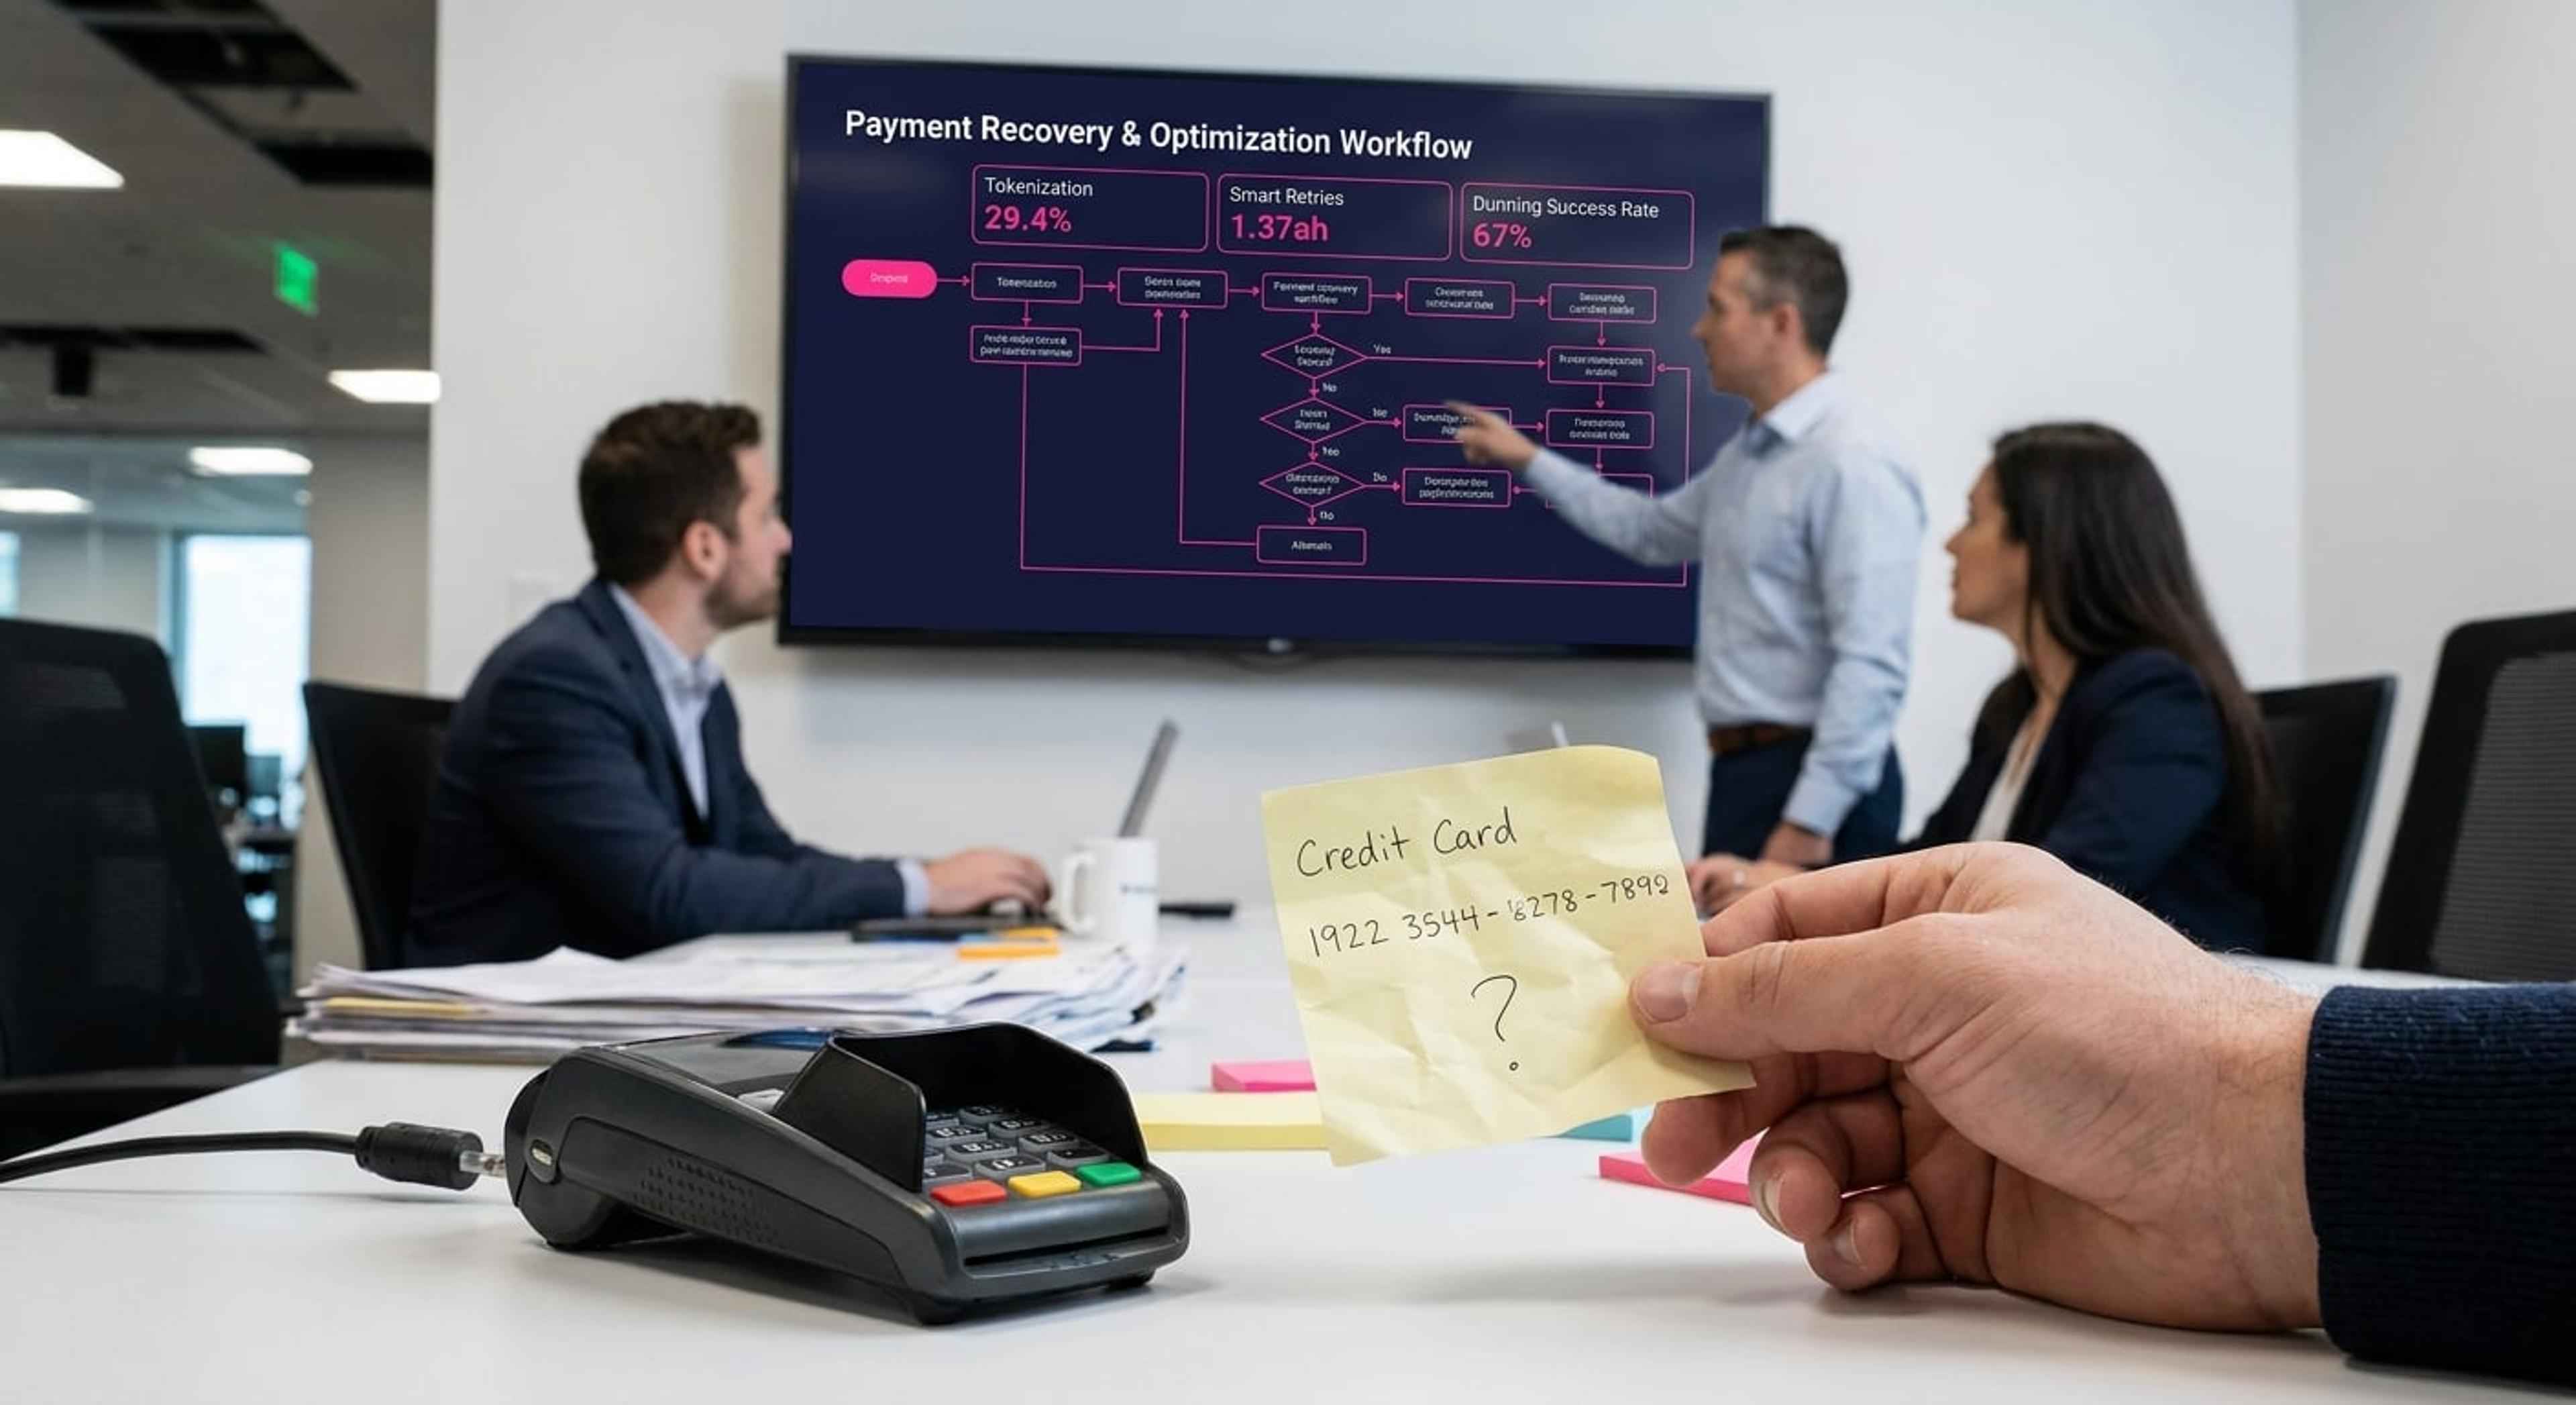
- Implement network tokenization and account updaters: Replace raw PANs with network tokens and enable Card Account Updater (CAU) services to automatically refresh expired credit cards or replaced lost cards without interrupting recurring billing.
- Segment retry schedules by BIN data: Inspect the Bank Identification Number (BIN) to distinguish credit cards from debit or prepaid cards, aligning retry attempts with credit statement reset cycles rather than payroll dates.
- Optimize authorization payloads: Pass rich transaction data, including Address Verification Service (AVS) details, CVV, and proper merchant category codes (MCC), to improve issuer trust and lift baseline approval rates.
- Adhere to network retry mandates: Monitor response codes to separate hard declines from soft declines, ensuring your payment stack immediately halts retries on permanent failure codes to avoid scheme penalty fees.
How does SmartRetry help with Credit Card transactions?
SmartRetry maximizes revenue recovery on declined credit card transactions by analyzing issuer-level decline codes, BIN attributes, and historical authorization patterns. Rather than relying on static retry intervals, the platform dynamically schedules payment retries for the exact moments when a cardholder’s credit line is replenished or when issuer fraud filters are most likely to approve the request. Explore SmartRetry’s intelligent payment recovery engine to see how machine-learning retry strategies can reduce involuntary churn and lift your credit card approval rates.