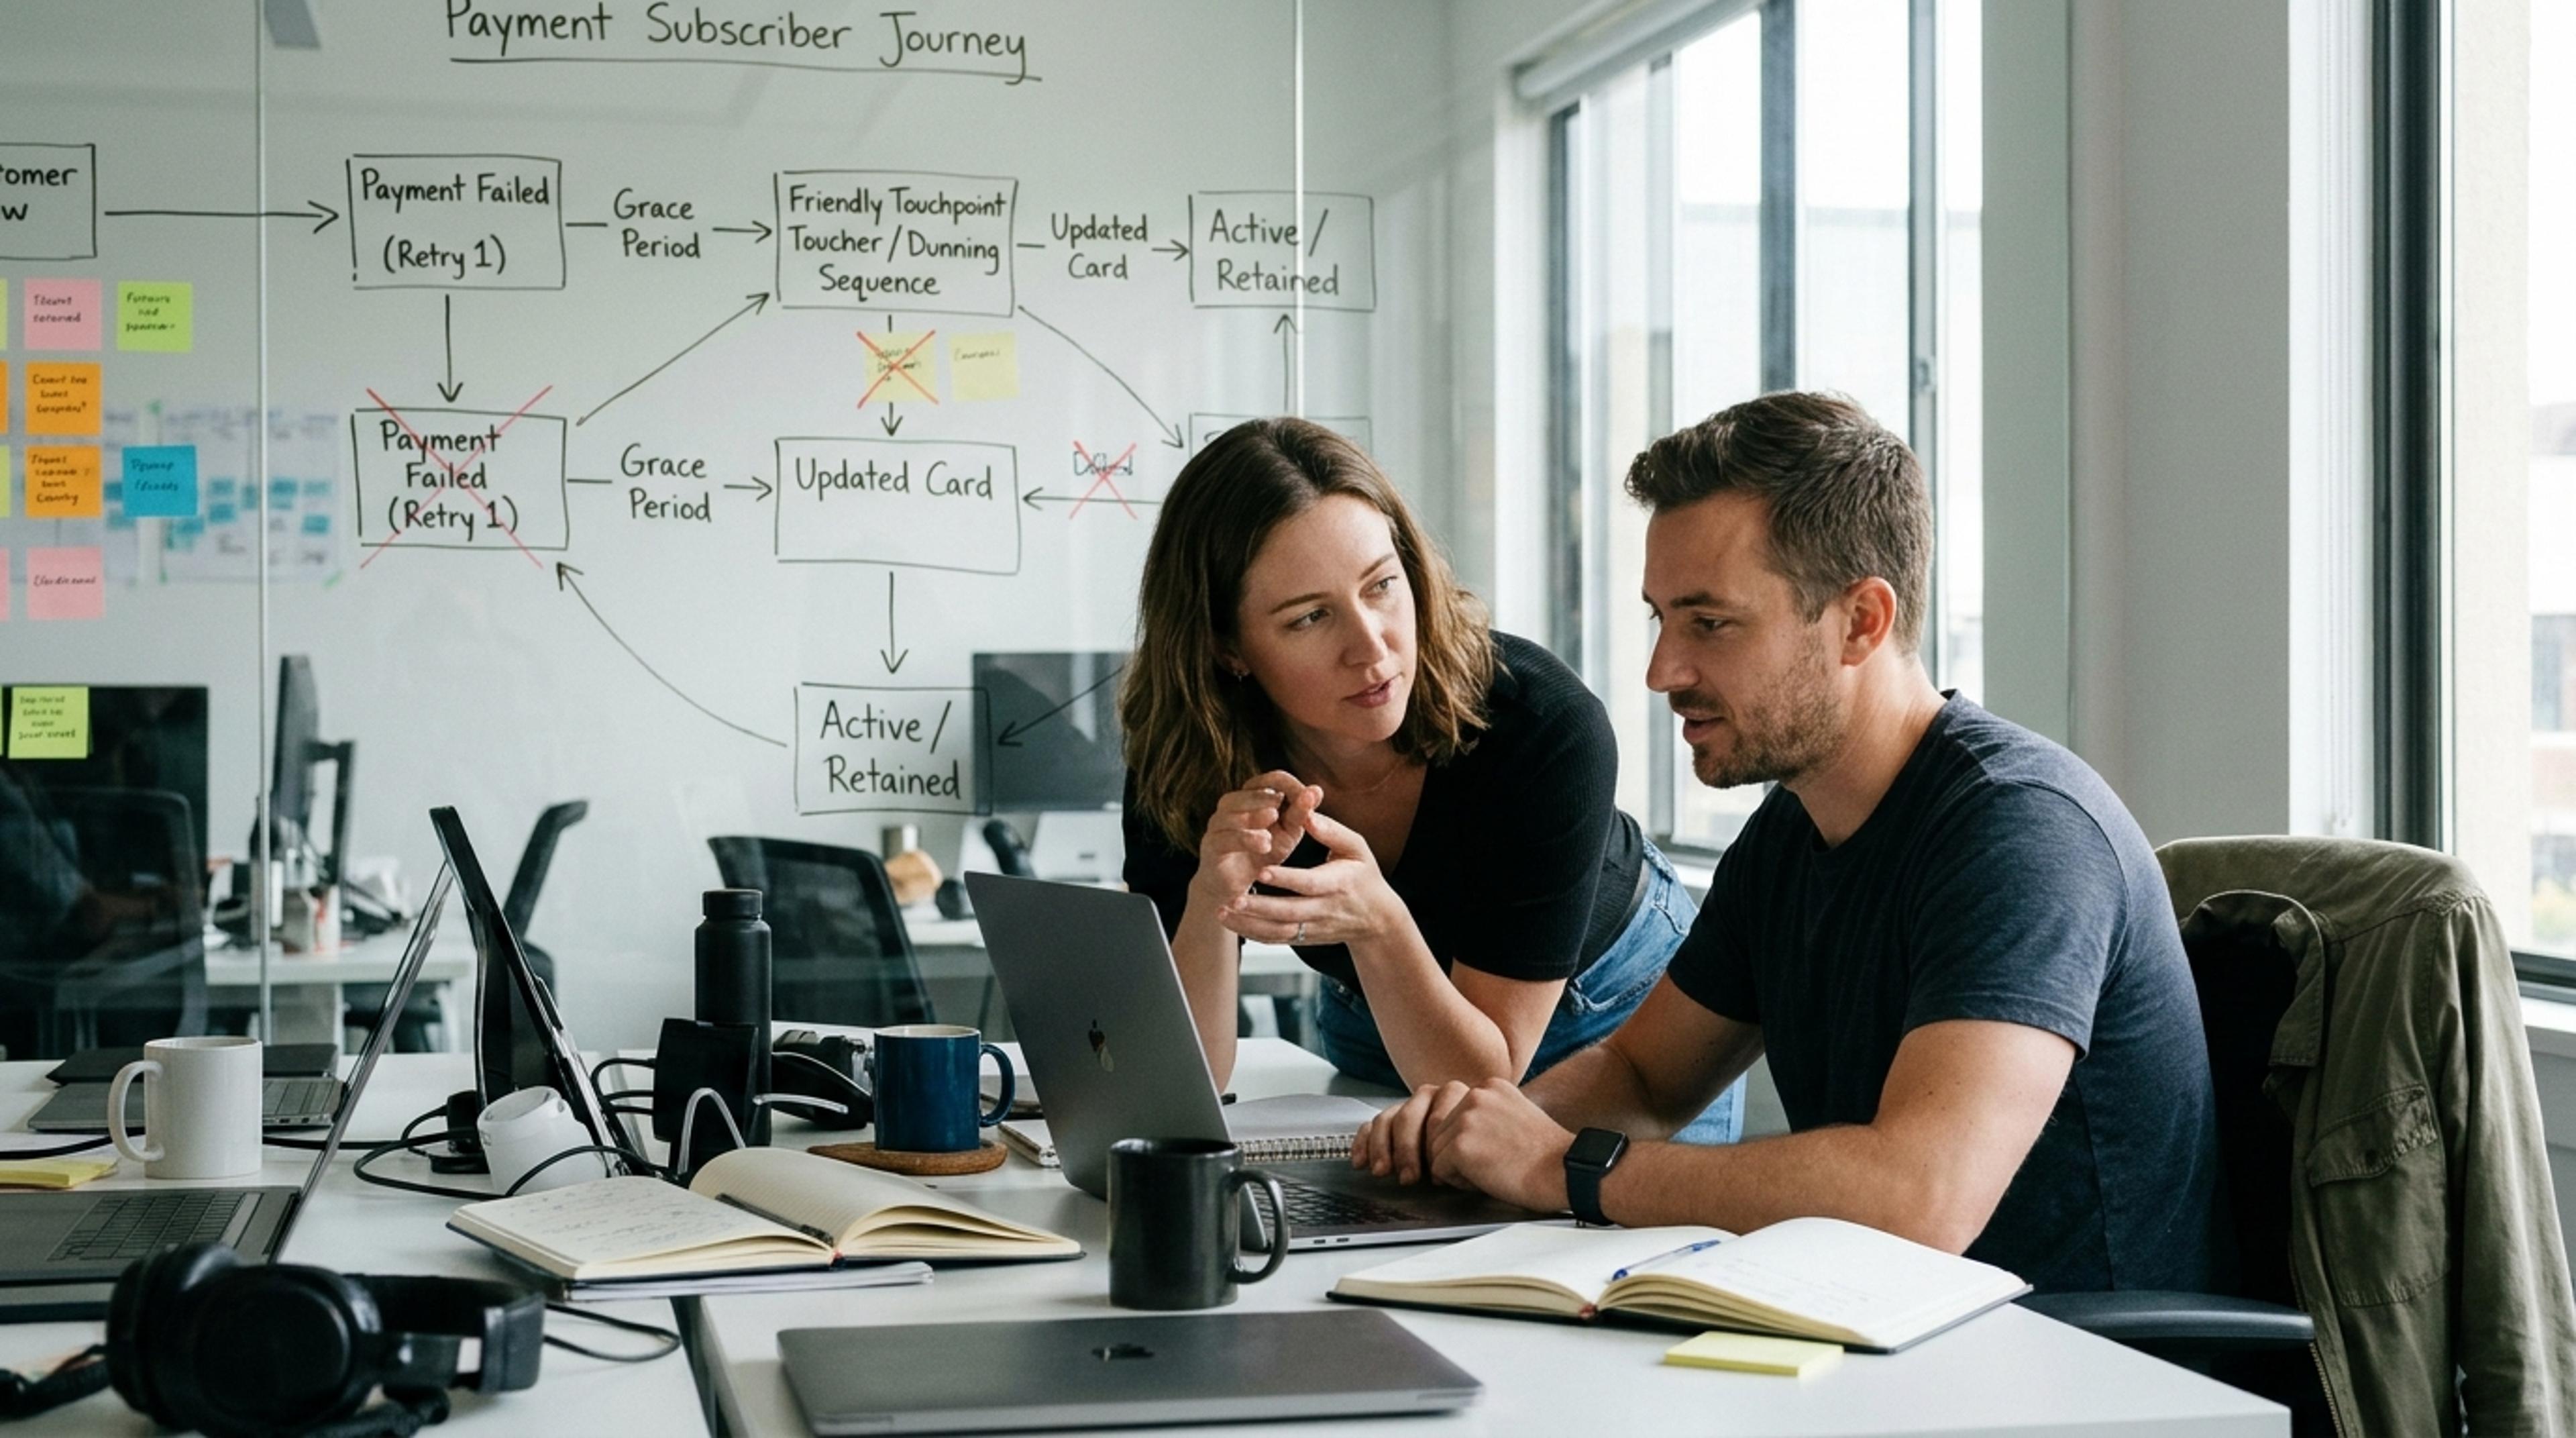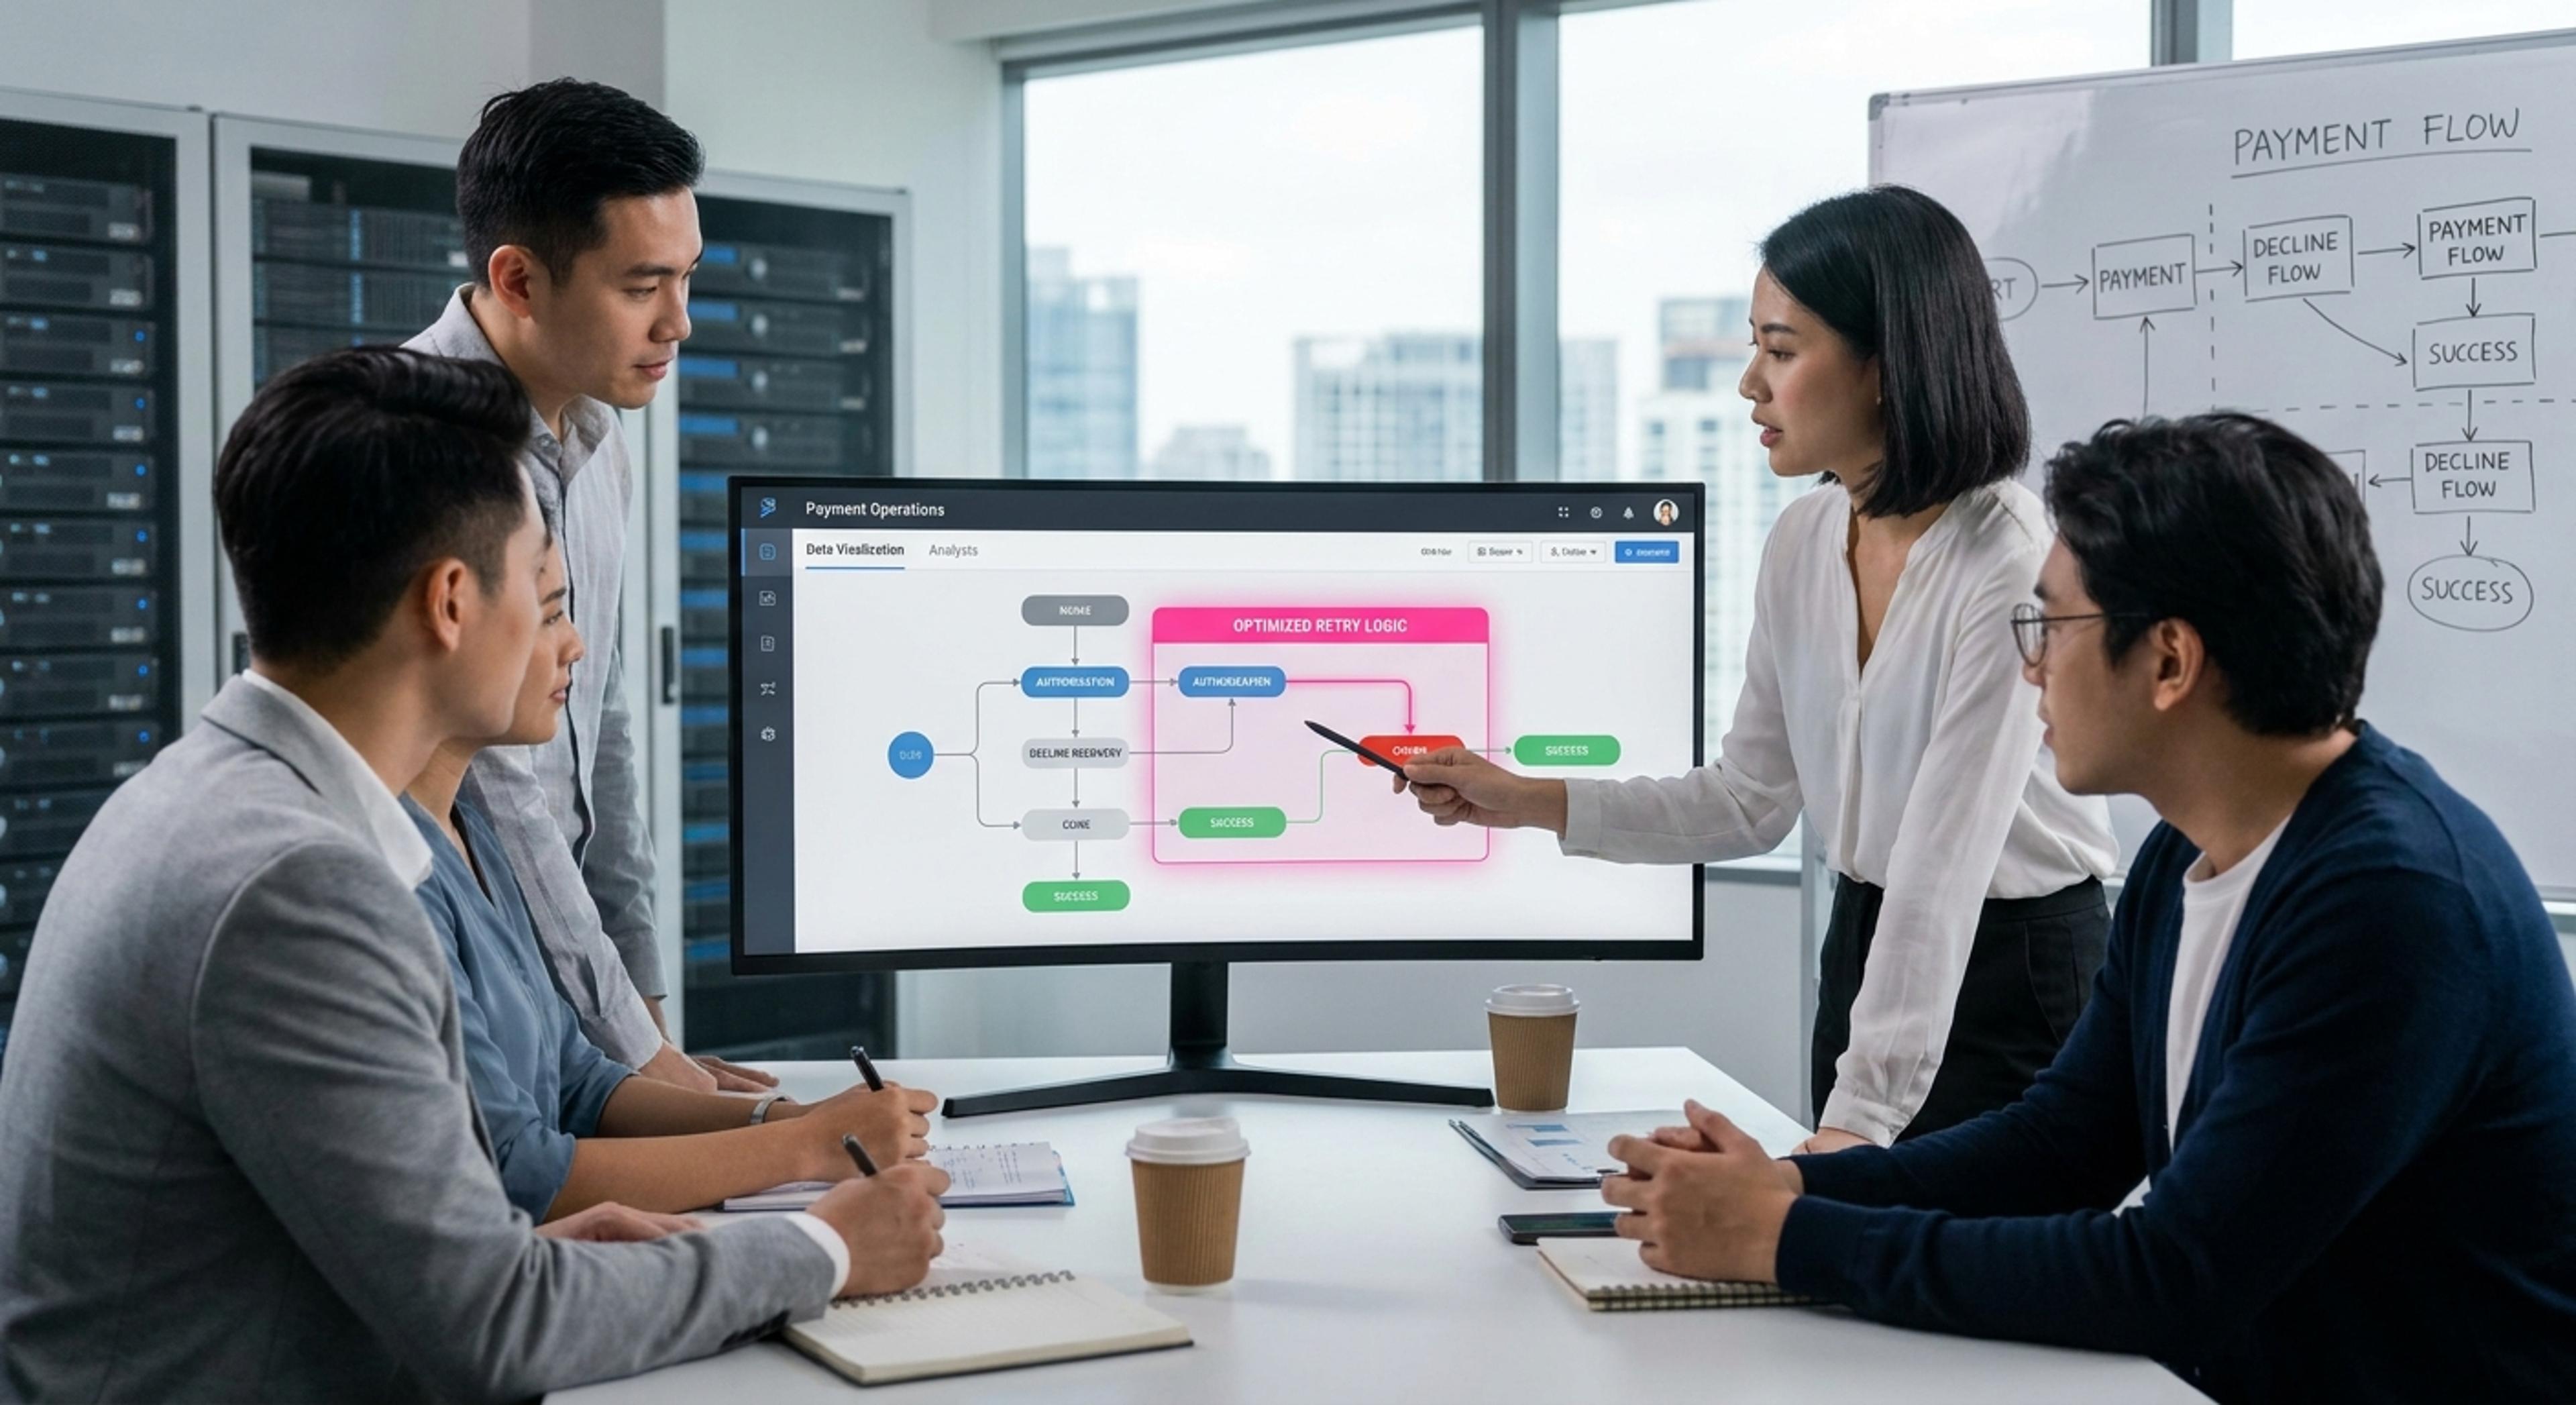

Involuntary churn is the unintended cancellation of a recurring customer subscription caused by billing and payment execution failures rather than an active cancellation decision. It typically stems from expired card credentials, insufficient funds, processor network errors, or outdated billing metadata, terminating active accounts while customer intent to subscribe remains intact.
What is involuntary churn and how does it work?
Understanding what is involuntary churn requires examining the sequence of an automated recurring charge. In a typical subscription billing run, the merchant billing engine dispatches a merchant-initiated transaction (MIT) using cardholder credentials stored on file. The transaction traverses the gateway, acquirer, card scheme, and issuing bank for authorization.
If the issuing bank rejects the authorization request, the transaction results in a decline code. Declines generally fall into two categories:
- Soft declines: Transient failures where the underlying account remains valid, such as temporary insufficient funds, network connection timeouts, or momentary risk-scoring alerts.
- Hard declines: Permanent structural failures where the payment credential cannot be reused, such as reported stolen cards, invalid account numbers, or closed accounts.
When merchants lack automated remediation or deploy naive retry cadences, soft declines remain uncollected. Once a merchant billing schedule exhausts its retry attempts and customer dunning period without capturing funds, the billing platform revokes user access and marks the subscription as churned.
Why does involuntary churn matter for payment teams?
Involuntary churn directly suppresses customer lifetime value (LTV) and inflates customer acquisition cost (CAC) payback windows. Unlike voluntary departures, passive cancellations abandon customers who actively consume and value the merchant product. In 2024, 24% of churn was attributed to involuntary churn, primarily caused by failed payments (Adyen, 2025).
When silent payment drop-offs occur, acquiring replacement customers requires fresh marketing spend to replenish baseline monthly recurring revenue. Eliminating payment friction at renewal is substantially cheaper than acquiring new pipeline volume.
What are common use cases for involuntary churn?
Passive subscriber loss affects recurring business models through distinct structural triggers:
- SaaS and B2B subscriptions: Expired corporate purchasing cards and corporate credit limit ceilings trigger repeated end-of-month authorization rejections on high-value business contracts.
- Digital goods and streaming services: Low-average-order-value consumer subscriptions experience frequent soft declines from temporary insufficient funds during mid-month balance troughs before standard payroll cycles.
- Ecommerce replenishment retail: Physical box subscriptions suffer high turnover when consumers receive replacement debit cards following local bank re-issuances without synchronized credential updates.
- Gaming platforms: Micro-subscription accounts run into automated fraud blocks when sudden geographical routing changes or device shifts trigger aggressive issuer anti-fraud heuristics.
Involuntary Churn vs Voluntary Churn
| Dimension | Involuntary Churn | Voluntary Churn |
|---|---|---|
| Customer Intent | Customer intends to remain active and continues using the service. | Customer consciously decides to cancel or downgrade service. |
| Root Cause | Payment processing declines, expired credentials, or bank fraud blocks. | Poor product fit, high pricing, low usage, or customer dissatisfaction. |
| Detection Point | Payment gateway error codes and uncollected authorization receipts. | Cancellation flow submission, survey answers, or support tickets. |
| Recovery Mechanism | Algorithmic retries, card account updaters, and network tokens. | Product feature improvements, discount offers, and save desks. |
How is involuntary churn measured?
Payment and revenue operations teams quantify involuntary churn using three primary calculations:
- Involuntary Churn Rate: (Involuntarily Lost Subscribers in Period / Total Active Subscribers at Period Start) × 100
- Involuntary Churn Share: (Involuntary Churn Count / Total Churn Count) × 100
- Failed Payment Recovery Rate: (Successfully Recovered Transactions / Total Failed Recurring Authorizations) × 100
What are best practices for involuntary churn?
Preventing payment-induced churn requires a defense-in-depth approach spanning credentials, transaction routing, and recovery schedules:
- Automate credential management: Connect to Visa Account Updater (VAU) and Mastercard Automatic Billing Updater (ABU) to refresh expired card primary account numbers and expiration dates seamlessly.
- Implement network tokenization: Replace raw card credentials with network tokens to benefit from automatic lifecycle updates and issuer approval lifts.
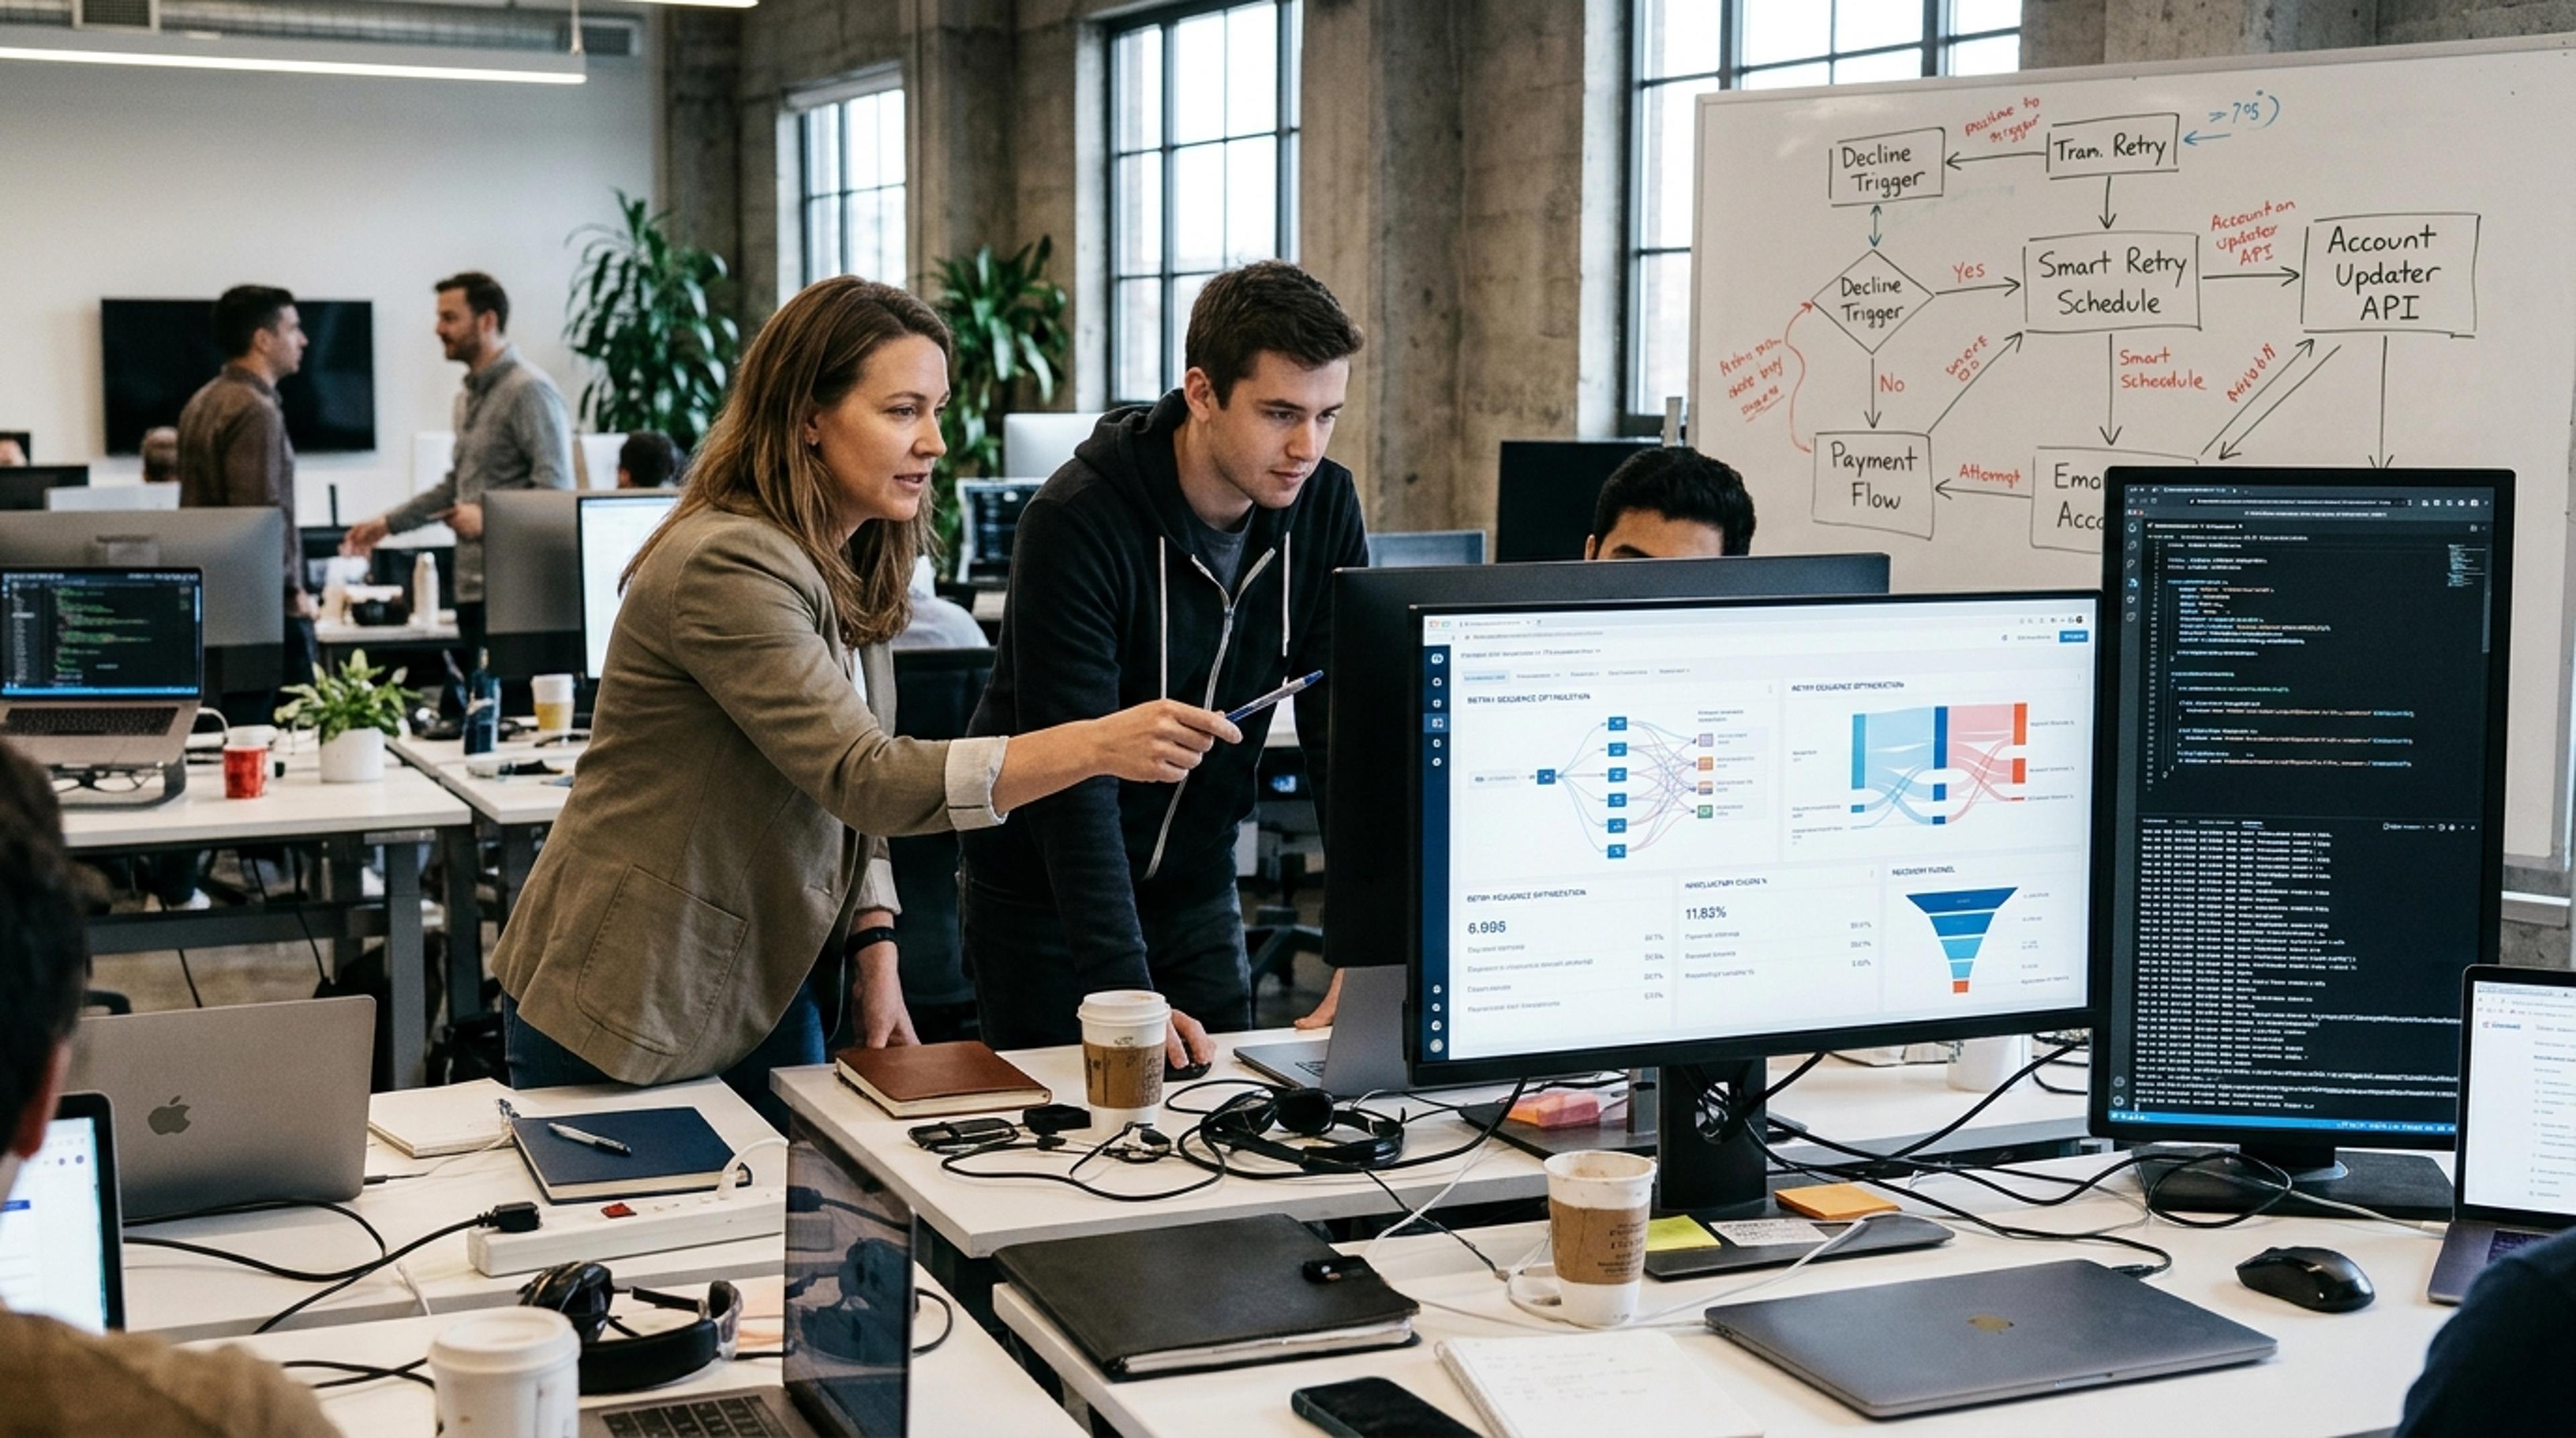
- Deploy smart retry schedules: Abandon static retry intervals in favor of dynamic schedules that align retries with cardholder paydays, issuer banking hours, and specific decline response codes.
- Differentiate soft and hard declines: Immediately halt retries on hard declines to avoid scheme fines, while targeting soft declines with tailored reattempt logic.
- Trigger pre-dunning notices: Notify subscribers about impending card expirations inside the application interface before billing dates arrive.
How does SmartRetry help with involuntary churn?
SmartRetry stops involuntary churn before subscriptions lapse. By analyzing raw ISO 8583 response codes and issuer authorization habits, SmartRetry routes each failed recurring transaction through machine-learning models that calculate the optimal retry timestamp. This approach recovers soft declines without manual merchant intervention or subscriber friction. Schedule a consultation to discover how SmartRetry helps recurring businesses recover lost revenue and secure subscriber retention.